

The first data centre study by the HypZert Industry Expert Group highlights the key factors regarding location, technical infrastructure and the valuation of specialised properties.
With the study “Data Centres – Insights into a New Asset Class”, HypZert’s Industry Expert Group presents its first analysis of this segment.
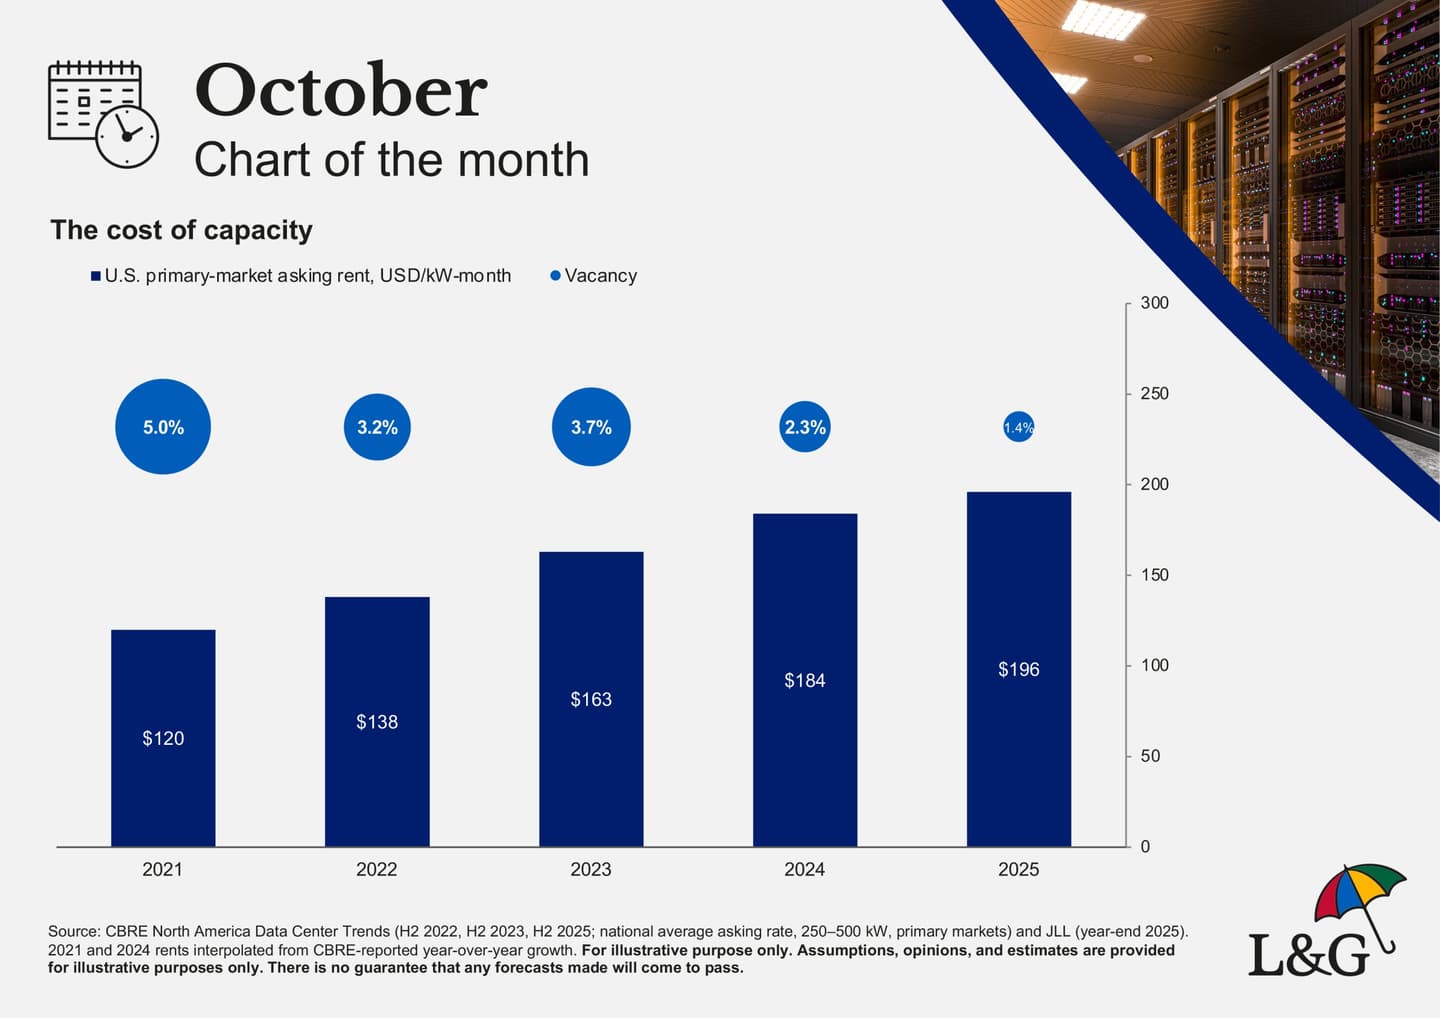
In particular, the use of artificial intelligence and machine learning is leading to an exponentially growing demand for data centre capacity. “This development is increasingly establishing data centres as a distinct asset class within the property investment market. The requirements for these properties are complex and are constantly evolving in line with technological progress. Location, building, technical infrastructure and operational concept must always be considered in conjunction with one another,” says Nina Babic, Deputy Chair of the Supervisory Board at HypZert, summarising the study’s findings.
Electricity and fibre-optic connectivity are key location factors
When selecting and assessing locations for data centres, the first crucial factor is whether a sufficiently large-scale energy supply is available or can be provided. Equally relevant are the timing of supply, regional electricity costs and the prospect of a reliable long-term supply.
Redundant electricity and fibre-optic connections are required to meet high availability requirements. Proximity to key internet hubs and to the respective users can create additional location advantages.
In established markets such as Frankfurt am Main and Berlin/Brandenburg, high demand is met with limited space and electricity capacity. This can lead to price increases, but may also boost the attractiveness of alternative locations.
Frankfurt am Main: the number one location in Germany
In general, investment in data centre property has risen in Germany. “Owing to its strong economic power, central location and existing energy and network infrastructure, the Rhine-Main region – and Frankfurt am Main in particular, with the DE-CIX internet exchange – is one of the most important data centre markets in Europe,” Nina Babic continued.
Although the transaction volume is still lower compared to established asset classes such as offices, residential or logistics, individual data centre transactions often reach volumes in the hundreds of millions, thereby in some cases significantly exceeding the transaction sizes of other asset classes. Due to the fundamental drivers of demand, data centres exhibit above-average growth potential in the medium to long term.
Building services play a key role in determining construction costs
The construction costs of a data centre are largely determined by the building services and the specific IT infrastructure, or rather the preparations for it. The costs for the technical infrastructure (energy supply, cooling, security) can exceed the pure construction costs of the building structure many times over.
At the same time, energy efficiency, water requirements and the potential for utilising waste heat must be taken into account during planning and operation. Regulatory requirements regarding energy consumption and efficiency therefore also influence the choice of location, the technical concept, and construction and operating costs.
Specific requirements for valuation
Data centres exhibit characteristics of both an operator-managed property and a high-tech infrastructure facility.
The valuation of data centres is currently carried out almost exclusively for investors and operators, and is undertaken by a small number of specialist firms with the relevant expertise and access to transaction data. Standardised methods, such as the income approach in accordance with the ImmoWertV, reach their limits here, as their key figures – such as remaining useful lives, maintenance costs and property capitalisation rates – cannot yet be reliably derived from the market.
The potential for alternative use is severely limited if there is not a sufficiently large pool of potential buyers for the same use; alternative uses are often only possible at considerable cost of conversion. Furthermore, particularly in the case of enterprise data centres and single-tenant concepts, the creditworthiness and likelihood of the tenant or operator remaining in the property are crucial.
Another key factor is technological obsolescence: Higher power densities and new cooling technologies can lead to technical components – or even the entire operational concept – becoming economically obsolete, even though the building structure itself could still be used for a long time to come. The operator is therefore regularly responsible for reinvestments.
A nuanced approach is also necessary when determining income and yields. The study cites, for stabilised data centre properties, depending on
level of development, net initial yields within a indicative range of approximately 4.5 to 6.5 per cent. In particular, properties let on long-term tenancies at established data centre locations with a secure power supply, tenants or operators with strong credit ratings and limited landlord obligations fall at the lower end of the range. For lenders, it is also crucial to determine which income can actually be attributed to the property and which revenues stem from operator or service contracts.
About HypZert and the Industry Section
HypZert GmbH is the largest accredited certification body for property valuers in Germany. It is a joint venture of all the leading associations in the German financial sector and has been certifying property valuers since 1996 in accordance with the internationally recognised criteria of ISO/IEC 17024. Currently, more than 2,600 valuers are certified, primarily in Germany but also abroad.
HypZert brings together the specialist knowledge of valuers in specific fields within twelve specialist groups. The Industry Specialist Group was founded in 2012. It currently comprises eight members.
We would be happy to send you the study ‘Data Centres – Insights into a New Asset Class’ free of charge upon request for your reporting purposes. It can be purchased here.