

The Nordex Group (ISIN: DE000A0D6554) reported strong business performance in the third quarter of 2026.
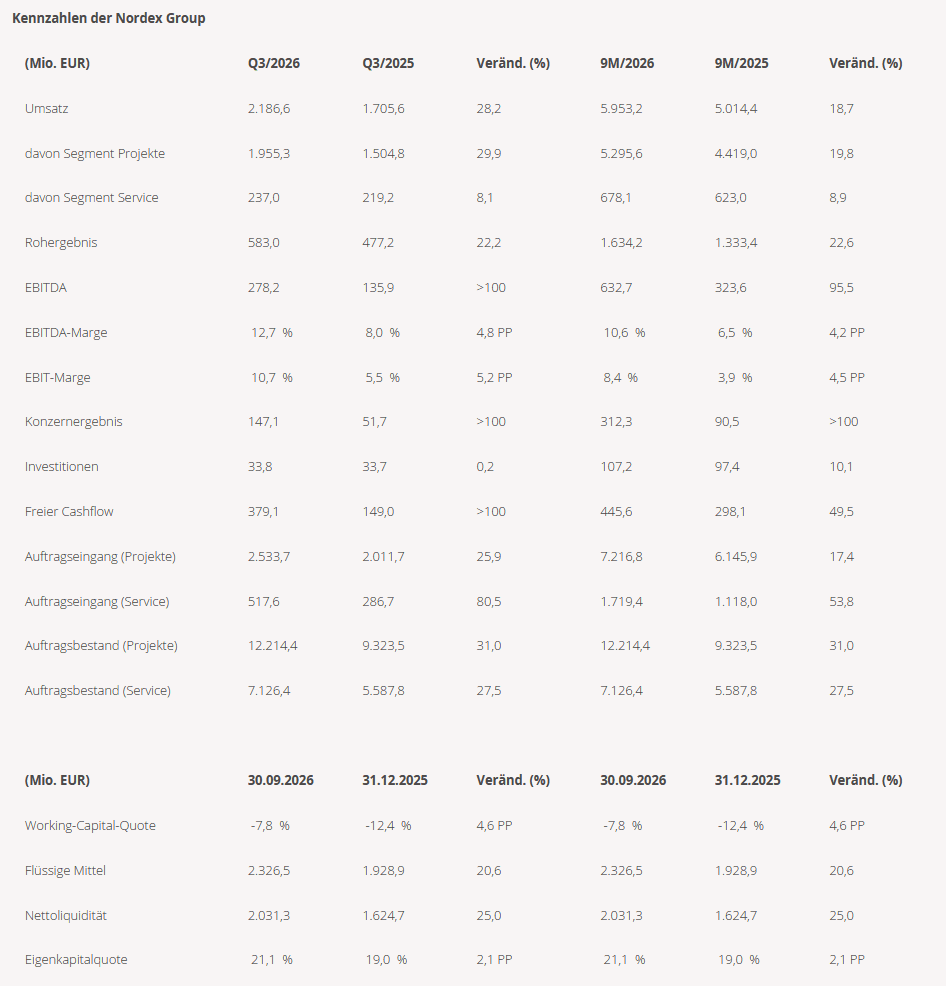
Revenue stood at around 2.2 billion euros in Q3 2026, up 28.2 per cent on the same quarter of the previous year (Q3 2025: 1.7 billion euros).
Earnings before interest, tax, depreciation and amortisation (EBITDA) more than doubled to €278.2 million in the third quarter of 2026 (Q3/2025: €135.9 million), resulting in an improved EBITDA margin of 12.7 per cent (Q3/2025: 8.0 per cent).
As a result, consolidated profit has almost tripled to €147.1 million, compared with €51.7 million in the third quarter of 2025.
"The third quarter marked an important milestone for us. We have raised our forecast for the EBITDA margin in the 2026 financial year to between 11.5 and 12.5 per cent and have further expanded our global presence, with orders from the US and, most recently, from New Zealand in October. This is the result of disciplined execution in the Projects and Service segments. Our forecast is therefore at the upper end of our medium-term target range, and we will continue to focus on delivering reliably,” explains José Luis Blanco, CEO of the Nordex Group.
Operating performance
In the third quarter of 2026, the Nordex Group recorded order intake of 2,810 MW in the Projects segment, an increase of 29.5 per cent compared with the same quarter of the previous year (Q3/2025: 2,170 MW). The orders came from ten countries and comprised various turbine models. The total order value reached €2.5 billion (Q3/2025: €2.0 billion). The average selling price in euros per megawatt of capacity (ASP) remained stable at €0.90 million/MW (Q3/2025: €0.93 million/MW).
Operating performance
As at 30 September 2026, the order book stood at 19.3 billion euros (30 September 2025: 14.9 billion euros), of which 12.2 billion euros were in the Projects segment (30 September 2025: 9.3 billion euros) and 7.1 billion euros in the Services segment (30 September 2025: €5.6 billion).
Production figures
In the third quarter of 2026, Nordex produced wind turbines with a total capacity of 2,363 MW. This represents a decrease of 7.0 per cent compared with the previous year (Q3/2025: 2,541 MW) and was therefore in line with the project plan. Rotor blade production rose by 16.8 per cent to 1,311 units (Q3/2025: 1,122 units). Of these, 337 rotor blades were produced in-house (Q3/2025: 366 units) and 974 units (Q3/2025: 756 units) were sourced from external suppliers.
Production figures
As expected, the Nordex Group installed 331 wind turbines in 15 countries in the third quarter of 2026, with a total capacity of 2,021 MW. By way of comparison, in Q3/2025, 420 wind turbines were installed in 16 countries, with a total capacity of 2,576 MW. The lower installation volume was mainly due to delays on the part of customers, in obtaining transport permits and in connection with rotor blade production in Turkey. Of the installed capacity (MW), 79 per cent was in Europe and 21 per cent in North America.
Segment reporting
Revenue in the Projects segment amounted to €2.0 billion in the third quarter of the year, representing an increase of 29.9 per cent compared with the same quarter of the previous year (Q3/2025: €1.5 billion). Revenue in the Services segment rose by 8.1 per cent to €237.0 million (Q3/2025: €219.2 million). At 20.6 per cent, the EBIT margin in the Services segment exceeded the target of 20 per cent. The EBIT margin in the Projects segment improved by 2.0 percentage points year-on-year to 13.1 per cent.
Key financial figures
As at 30 September 2026, total assets stood at €7.6 billion, representing an increase of 12.5 per cent compared with the figure at the end of 2025 (31 December 2025: €6.8 billion). As at the reporting date, the Group’s cash and cash equivalents totalled €2,326.5 million, representing an increase of 20.6 per cent (31 December 2025: €1,928.9 million). This resulted in a solid net cash position of €2,031.3 million (31 December 2025: €1,624.7 million). The equity ratio stood at 21.1 per cent (31 December 2025: 19.0 per cent) and the working capital ratio as a percentage of Group turnover was minus 7.8 per cent (31 December 2025: minus 12.4 per cent).
Key financial figures
In the third quarter of 2026, the Nordex Group generated a positive free cash flow of €379.1 million (Q3/2025: €149.0 million), which was primarily attributable to strong operating performance.
Outlook for the financial year
As announced in the preliminary announcement (ad hoc) of 15 October 2026, the Nordex Group now expects an EBITDA margin of between 11.5 and 12.5 per cent for the 2026 financial year (previously: 8.0 to 11.0 per cent). All other elements of the annual forecast remain unchanged:
- Revenue: EUR 8.2 to 9.0 billion
- EBITDA margin: 11.5 to 12.5 per cent (previously: 8.0 to 11.0 per cent)
- Working capital ratio: below minus 9 per cent
- Capex: around EUR 200 million
Information on reporting
The quarterly report for the first nine months of 2026 is now available on the Nordex Group website in the Investor Relations section under ‘Publications’ (ir.nordex-online.com). Neither the quarterly report nor the condensed interim financial statements have been audited or reviewed by an auditor.