

What returns do institutional investors expect from different real assets? And how does the required rate of return change when risks are assessed individually rather than collectively?
An analysis of more than 50 fully completed questionnaires from institutional market participants reveals a striking discrepancy.
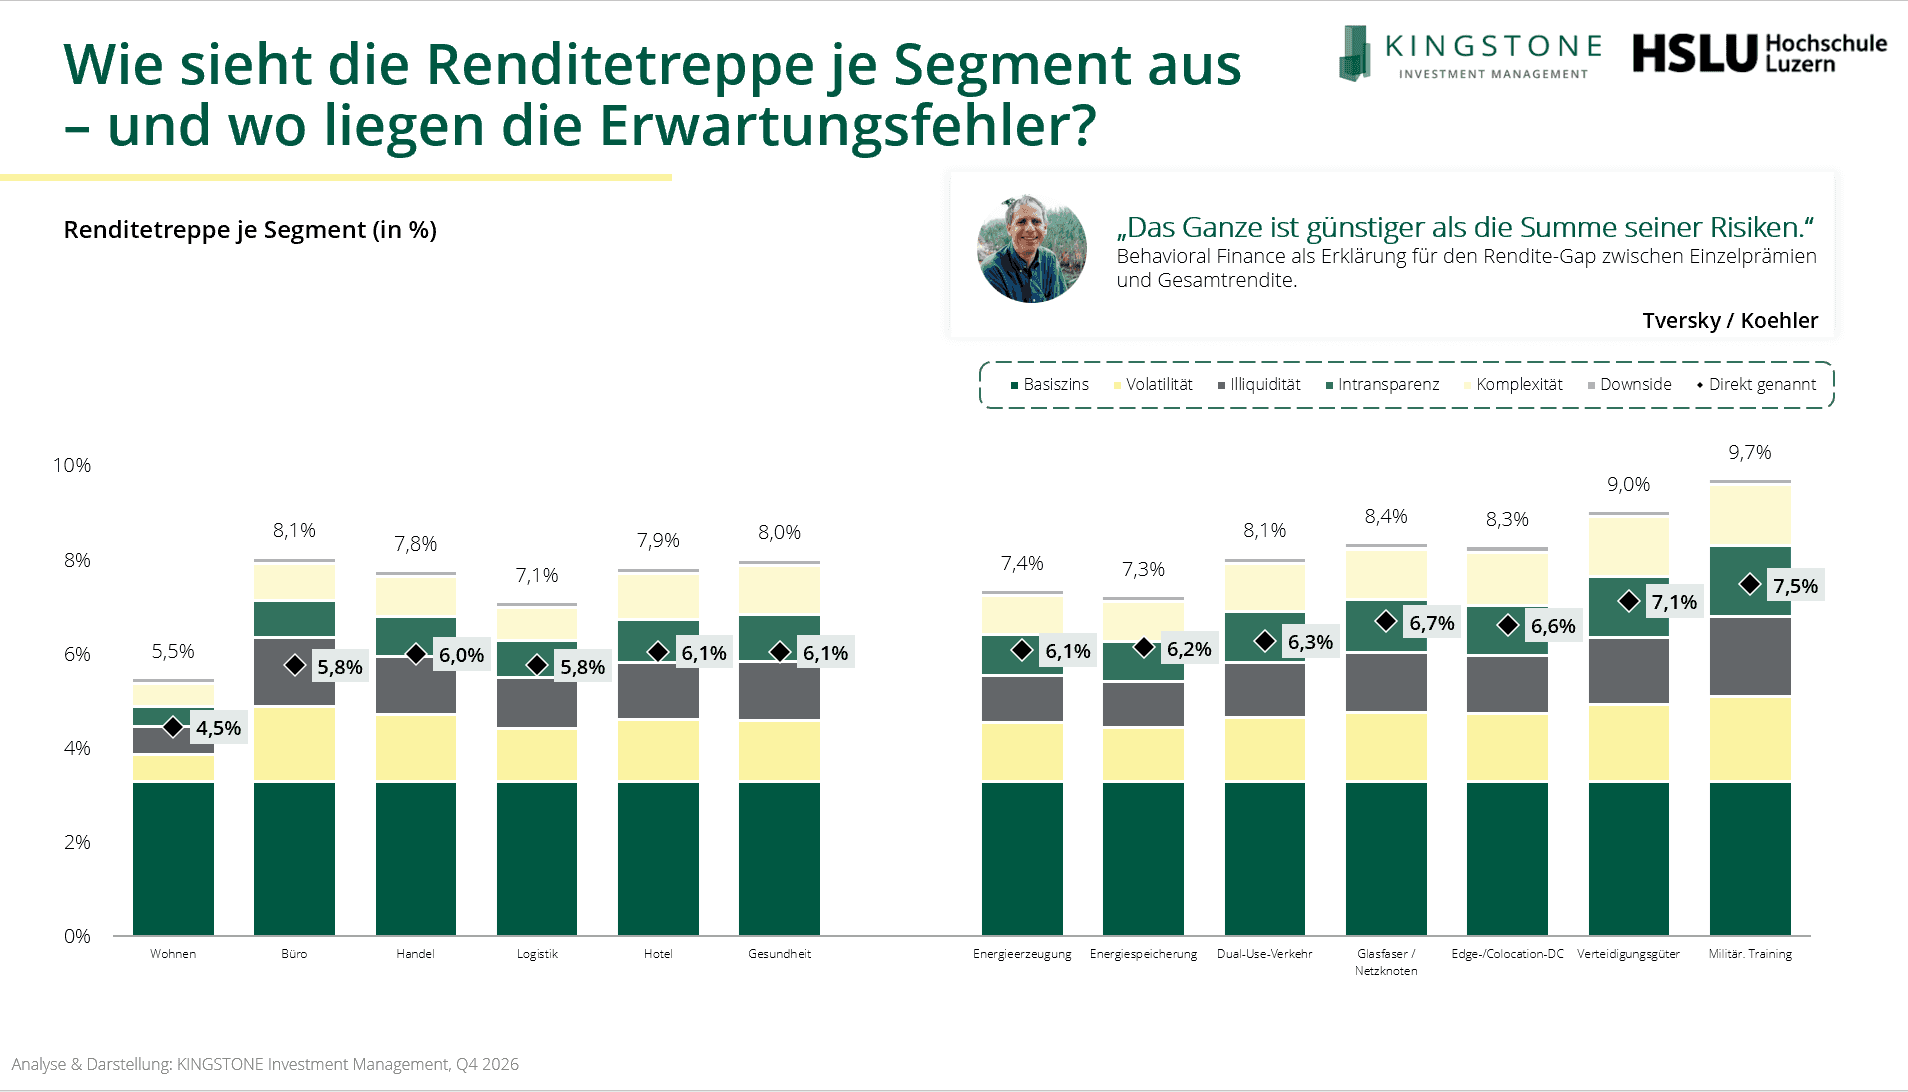
📊 Yield ladder: infrastructure with higher risk premiums
The chart compares the explicitly stated minimum total return with the sum of the base rate and premiums for volatility, illiquidity, opacity and complexity. For energy generation, a directly required return of 6.1 per cent contrasts with a calculated figure of 7.4 per cent. For fibre-optic cables and network nodes, the figures are 6.7 per cent versus 8.4 per cent; for military training infrastructure, 7.5 per cent versus 9.7 per cent. The sum of the individual premiums is consistently higher than the explicitly stated required return.
🧠 Behavioural Finance: Why the whole seems cheaper
One possible explanation is provided by the unpacking or subadditivity effect described by Tversky and Koehler. Risks considered in isolation tend to be weighted more heavily. When viewed as a whole, however, overlaps can be intuitively taken into account.
The return gap may therefore indicate both inflated individual premiums and underestimated overall risks.
⚡ Infrastructure: From individual risk to sector coupling
Particularly in the case of infrastructure, an isolated analysis of individual segments falls short. Energy generation, storage, grids and digital infrastructure are increasingly intertwined. It is crucial to distinguish between systematic risks, which affect multiple segments, and unsystematic risks, which can be reduced through diversification. Sector coupling creates mutual dependencies, but at the same time opens up potential for diversification and value creation.
Different business models along a value chain can complement one another in terms of their cash flow profiles.
⚖️ Risk pricing becomes an investment competence
A robust return requirement must combine the assessment of individual risks with an economic analysis of the overall investment. For infrastructure investors, this means not assessing risks in isolation by segment, but taking into account interactions and diversification effects at portfolio level. What matters is not the sum of individual risk premiums, but the actual risk profile of the portfolio and its appropriate remuneration.
🎙️ Want to know more about risk premiums and real assets?
You can find the recording of our latest ‘Macro Matters’ webinar with Prof. Dr Michael Trübestein in our media library, whilst on 27 November we’ll be taking a look ahead at the economy and property markets with Paul Richter from Helaba
#KingstoneSpotlight #RiskPremiums #RealAssets #Infrastructure #BehaviouralFinance #SectorIntegration #Diversification #MacroMatters