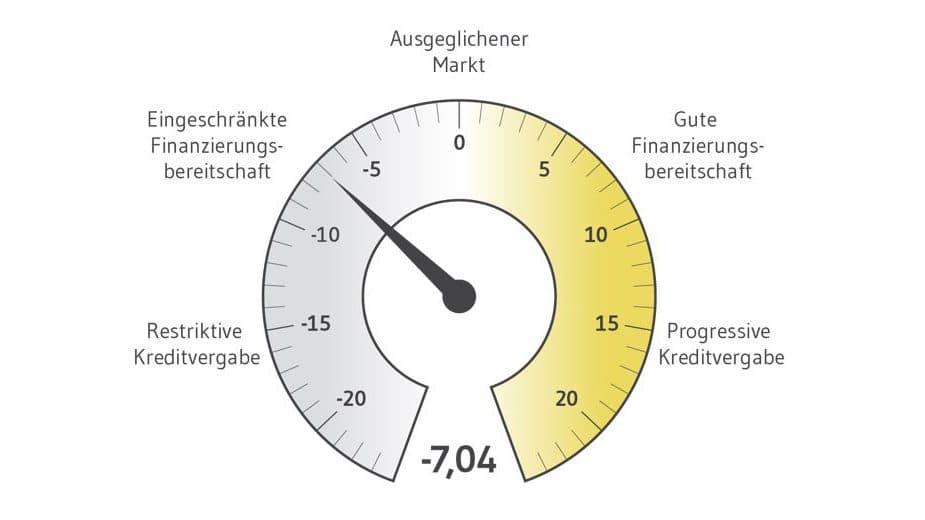


The Catella Residential Market Overview for Q3 2026 shows that, across Europe, a declining proportion of approved new-build flats are being completed. This points to increasing constraints on future housing supply. Higher financing costs and a sharp rise in construction costs are likely contributing to this decline. At the same time, gross yields have risen, whilst rental growth for new tenancies has slowed compared with the previous report. The findings confirm the structural undersupply on which Catella House View’s conviction regarding affordable housing is based. The biannual report covers 59 cities in 16 European countries.
- Completion rate: The average completion rate (defined as housing completions over a three-year period relative to planning permissions granted in the three preceding years) fell from 99.7 per cent to 80.1 per cent, whilst construction costs rose more sharply.
- Gross yields rose in most of the 59 cities. The aggregate European gross yield increased from 4.54 per cent in Q1 2026 to 4.67 per cent.
- Rents and prices are rising only moderately. New let rents average €20.81 per square metre per month (Q1 2026: €20.68), whilst prices for owner-occupied flats average €5,921 per square metre (Q1 2026: €5,859). Dublin remains Europe’s most expensive rental market, followed by London, Geneva and Zurich.
“The completion rate shows that planning permission is no longer a reliable indicator of future housing supply. Rising construction costs between the granting of planning permission and completion could partly explain why projects are not being started or are being further delayed,” says Dr Lars Vandrei, Head of Research at Catella Investment Management GmbH (CIM).
Focus: Fewer approved homes are being completed
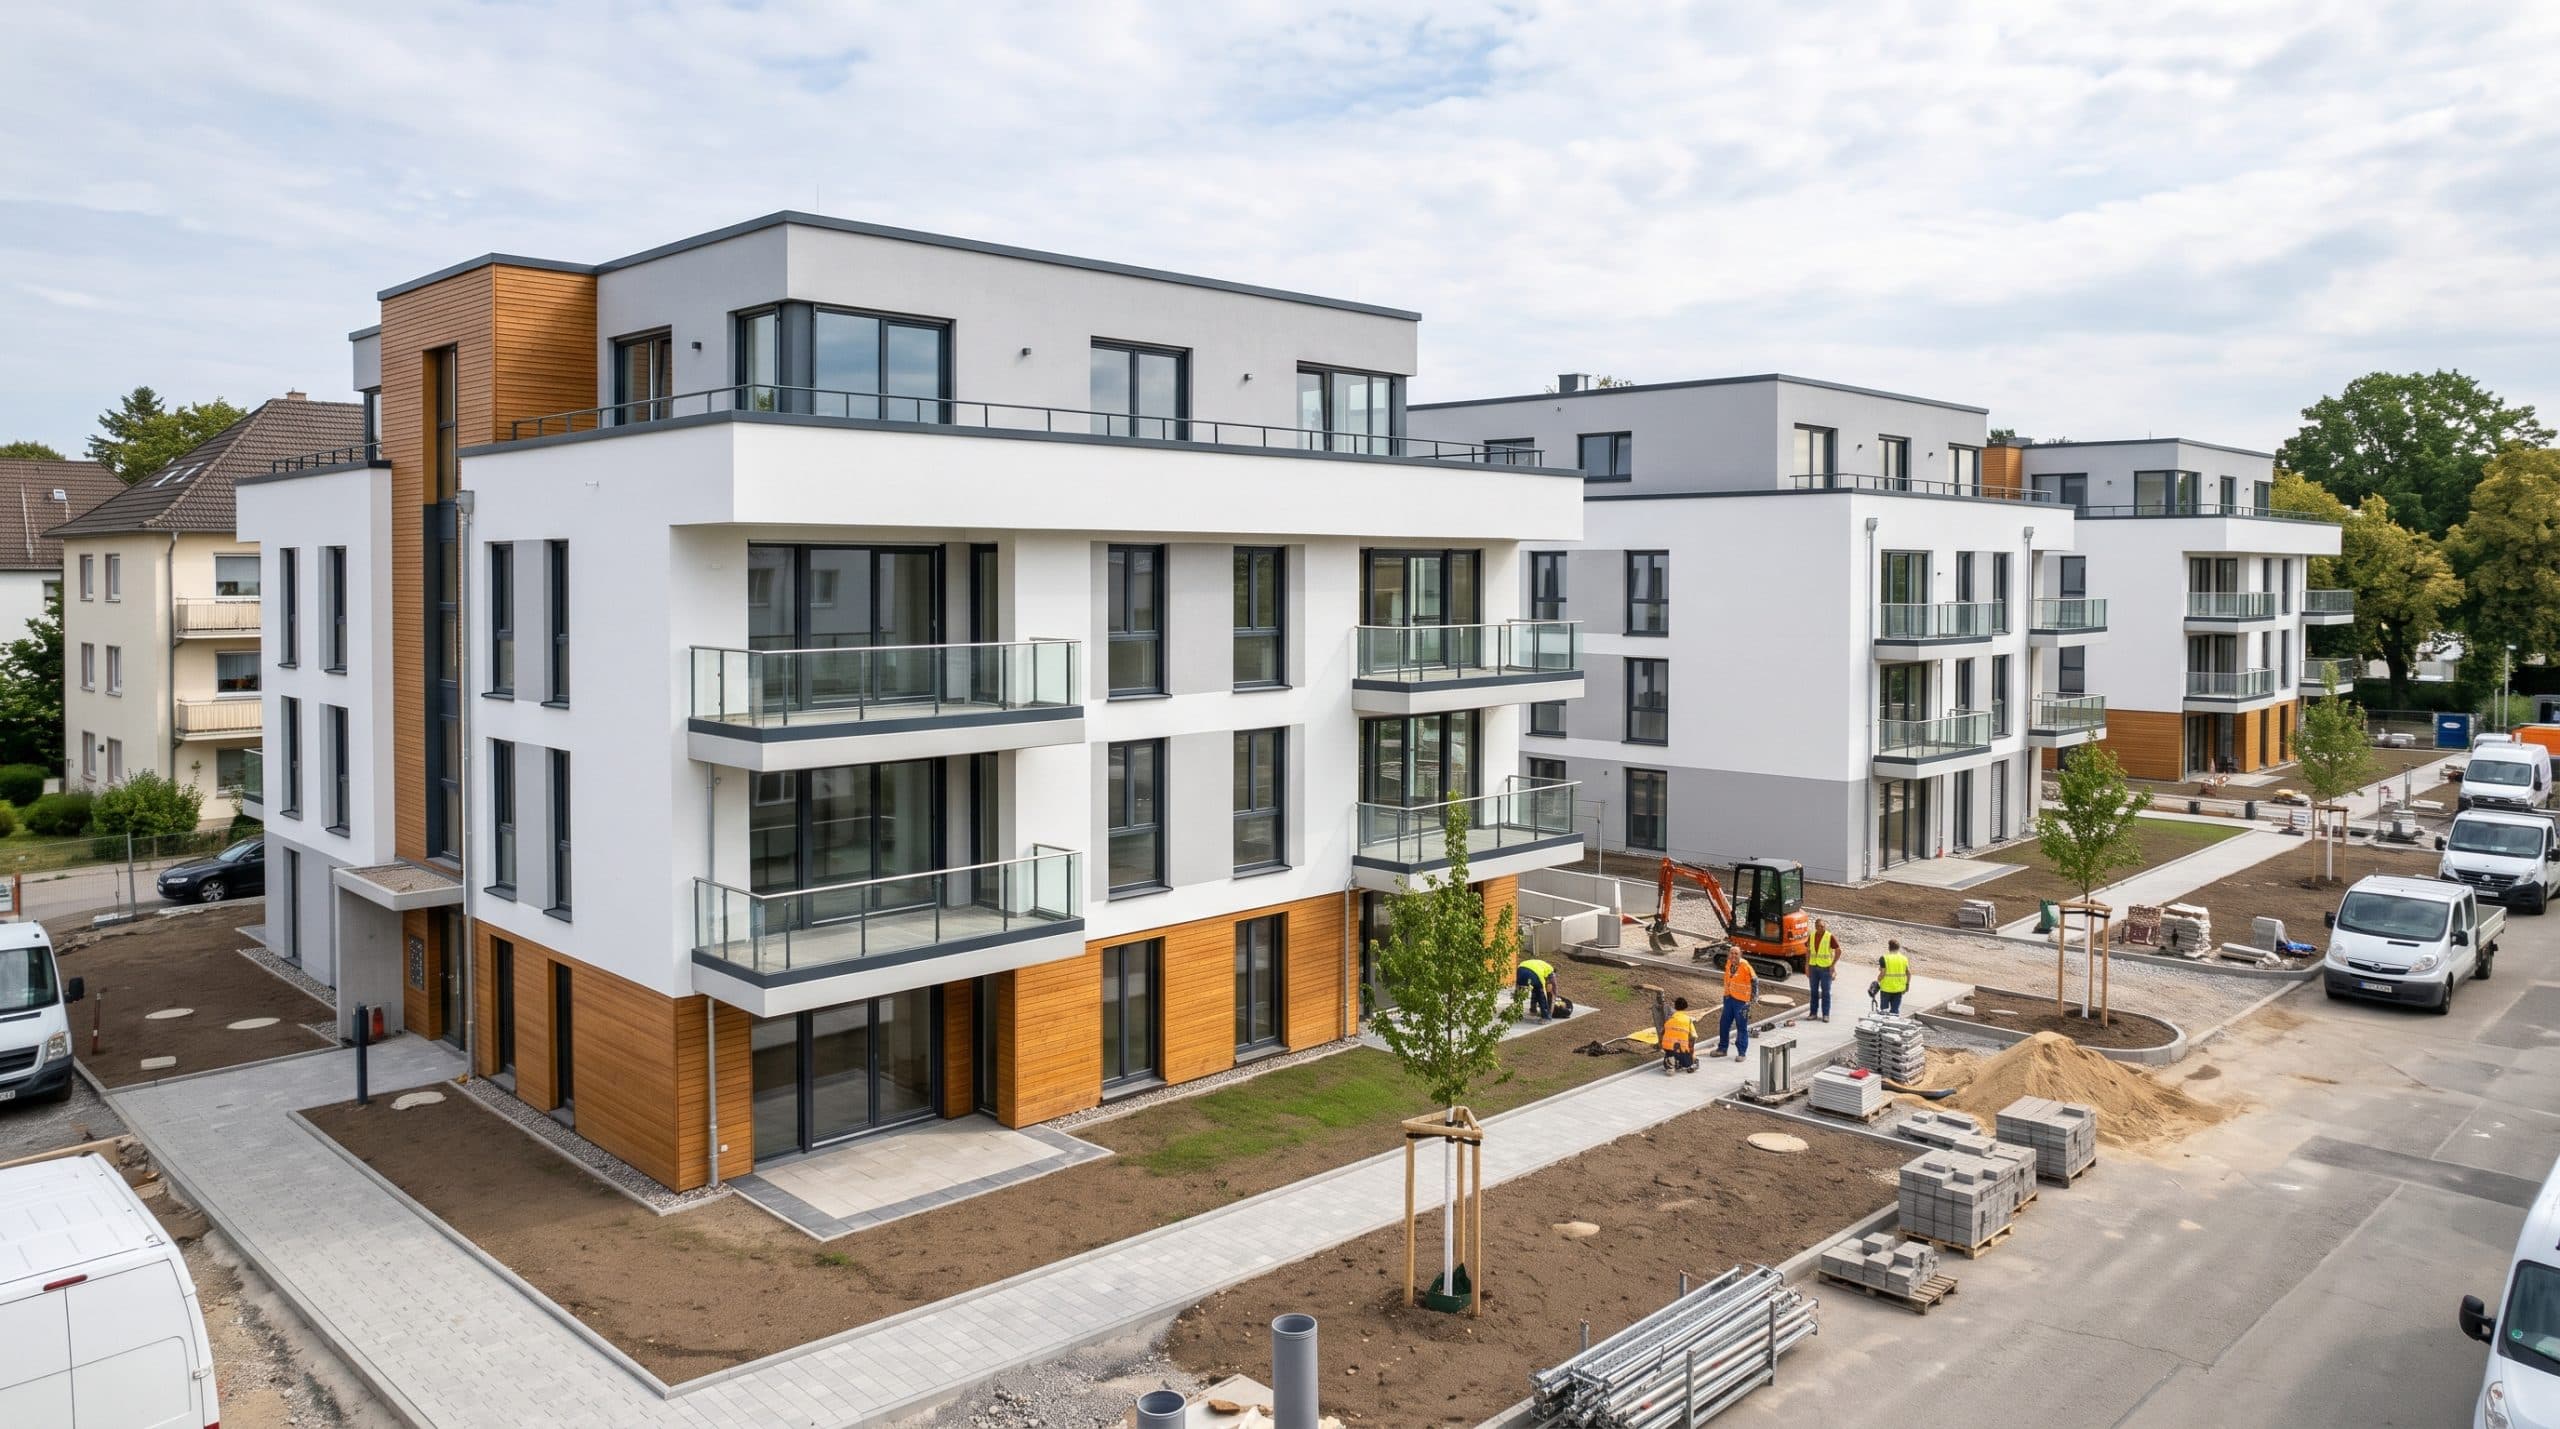
The completion rate is defined as the ratio of completions over a three-year period to the building permits issued in the three preceding years. On average, it fell from 99.7 per cent to 80.1 per cent and declined in all 16 countries surveyed. The current rate compares completions in the years 2023–2025 with planning permissions granted in the years 2020–2022. It suggests that supply bottlenecks are becoming more acute across Europe.
Only the Netherlands and Spain remain above 100 per cent; in the previous period, there were still six countries in this category. A rate above 100 per cent can arise because completions may also relate to planning permissions granted outside the relevant three-year window. This includes both older permissions and more recent projects that were completed more quickly.
At the same time, construction costs rose by 21 per cent between the granting of planning permission and completion, compared with 11 per cent in the previous period. Together with higher financing costs, this could explain why some approved projects have not yet started or are being further delayed. This puts additional pressure on the housing supply.
Gross yields are rising in most markets
In response to rising interest rates and limited liquidity, gross yields have risen over the past six months. The average European gross yield rose to 4.67 per cent, up from 4.54 per cent in Q1 2026. Only three cities recorded lower yields. Looking ahead to Q4 2026, Catella expects yields to remain stable due to low transaction activity in most markets.
“The decline in completion rates is placing further strain on the already tight European housing market. If fewer approved projects result in completed homes, supply is likely to remain tight. This underpins the long-term fundamentals of the residential property investment market and demonstrates why affordable housing is a structural necessity rather than a cyclical opportunity,” says Petra Blazkova, Head of Market Research and Product Development at the Catella Group.
Deep Dive Germany: Yields rise in all eight major cities
Gross yields rose in all eight major German cities, with the average increasing to 4.61 per cent (Q1 2026: 4.42 per cent). Munich (4.20 per cent) and Berlin (4.25 per cent) remain the markets with the lowest yields, whilst Leipzig (5.25 per cent) is the market with the highest. Average rents in the eight cities fell by 1.0 per cent compared with Q1 2026. This is primarily due to a change in the mix of properties on the market: there are currently fewer new-build flats on offer than six months ago. This is linked to the fact that Germany, too, is affected by the decline in completions: the completion rate fell from 103.4 per cent to 81.4 per cent.