Denne artikel er automatisk oversat.


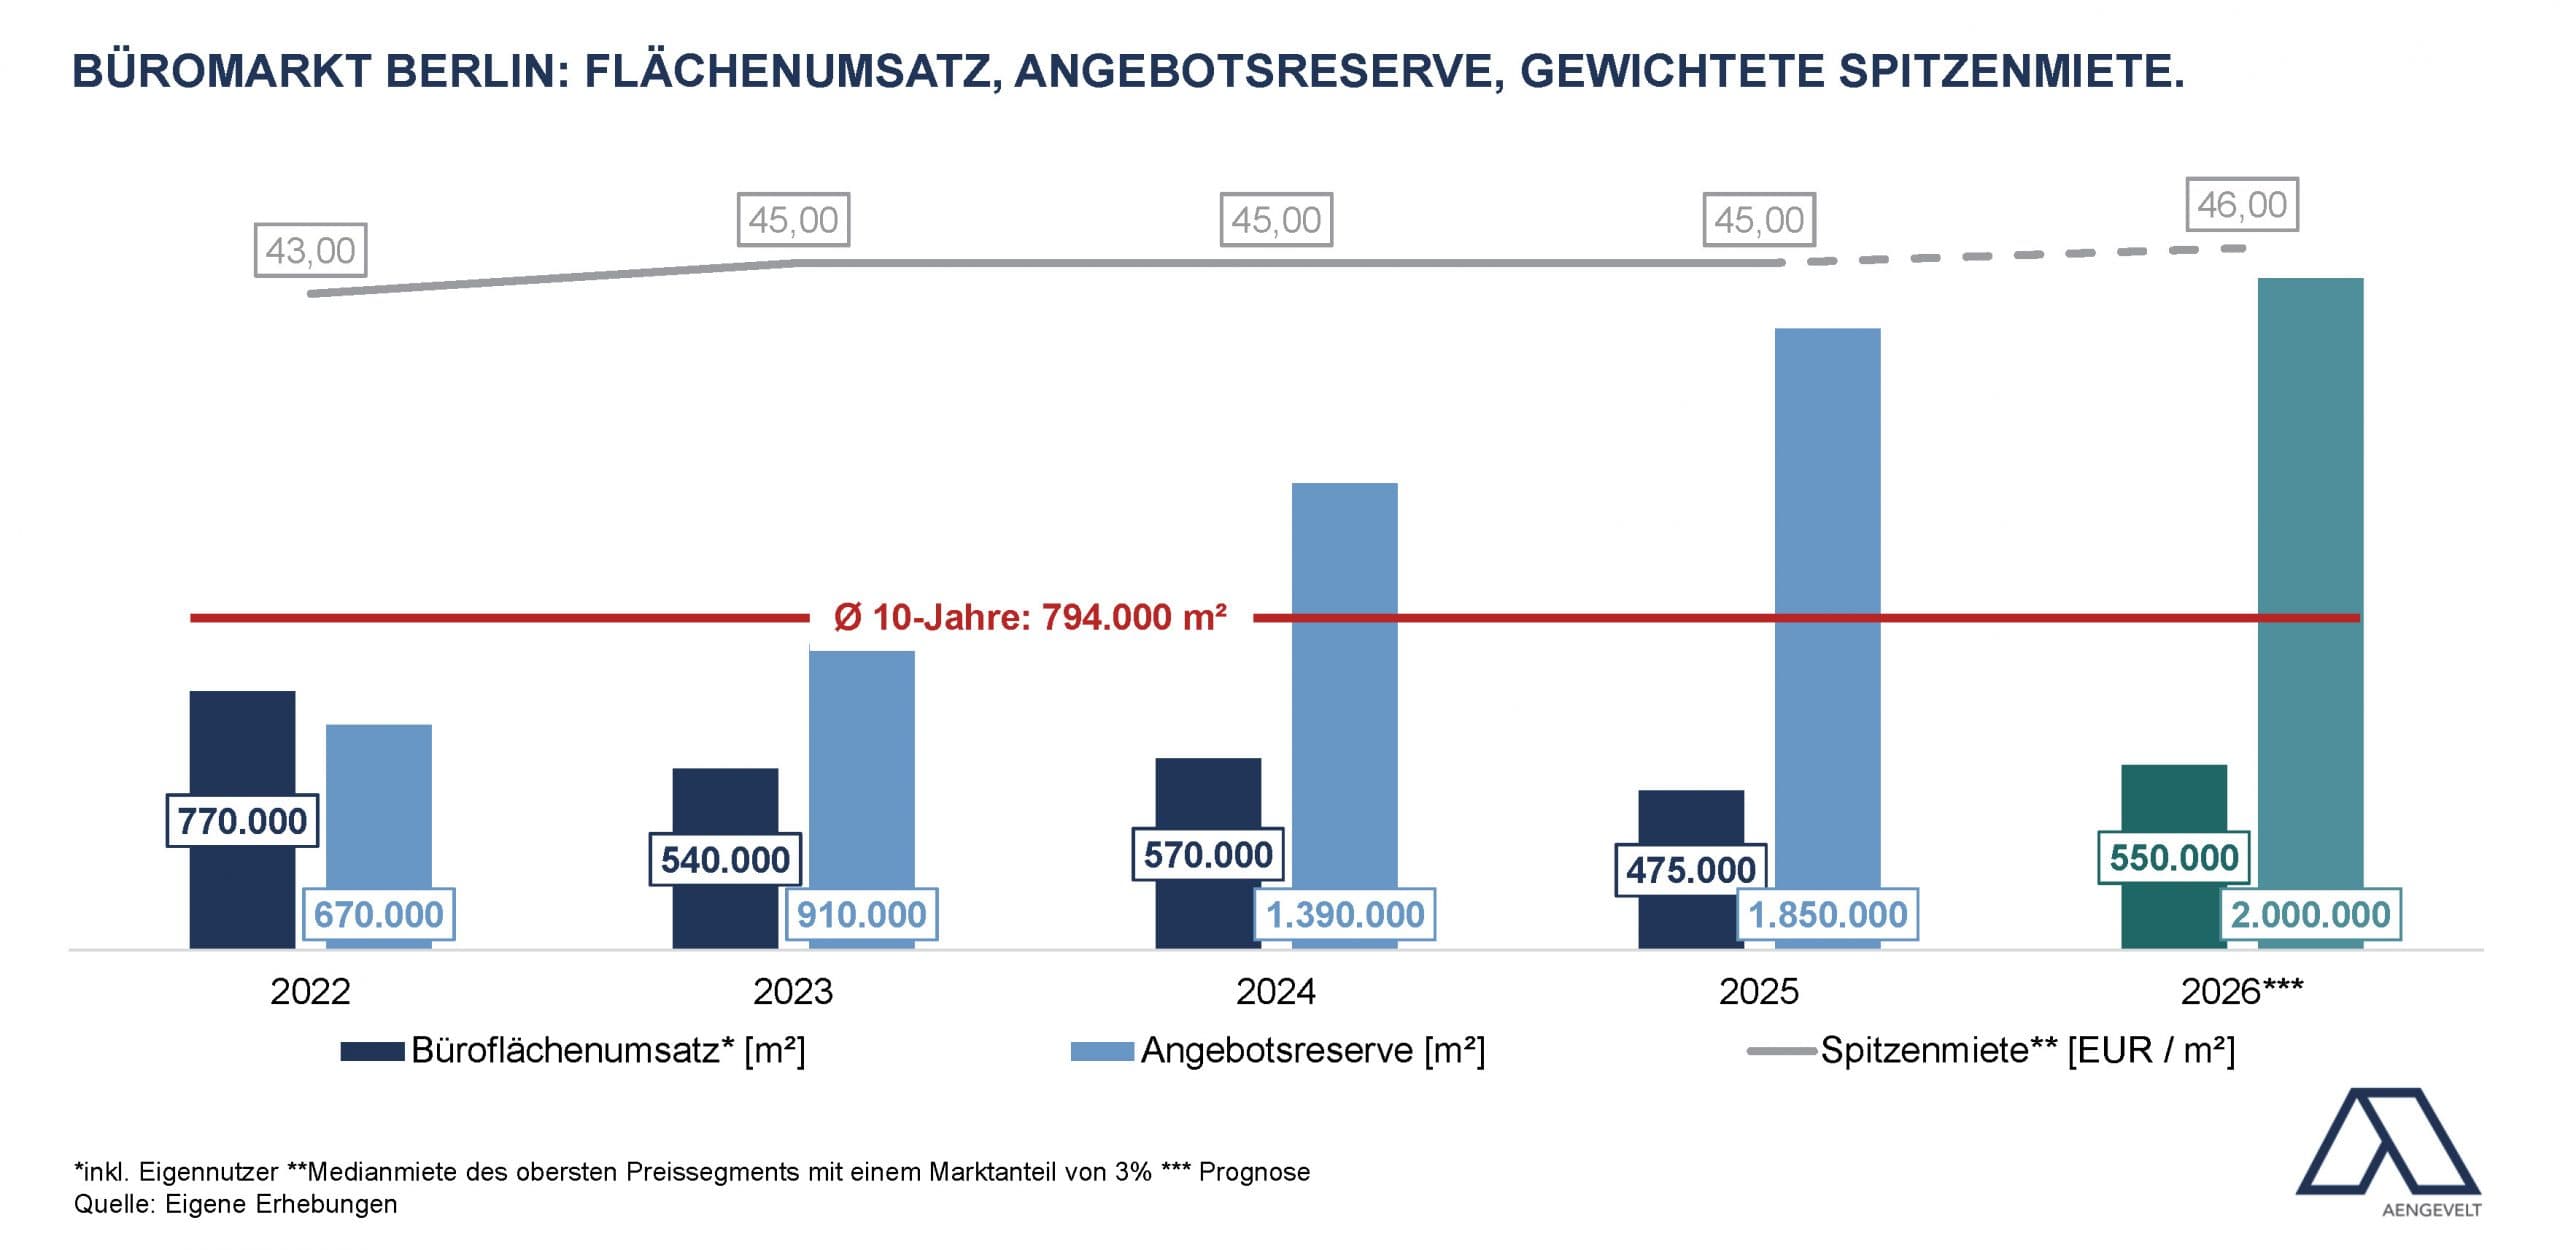
According to analyses by Aengevelt Research, the Berlin office market achieved office space take-up of around 475,000 m² in 2025, which is around 17% below the previous year's figure (2024: 570,000 m²), while remaining around 40% below the decade average (Ø 2015-2024: 794,000 m² p.a.).
With this result, Berlin ranks third nationwide behind Frankfurt (approx. 564,000 m²) and Munich (approx. 550,000).
For 2026 , Aengevelt Research forecasts an increase in office space take-up of 550,000 m² and thus a gradual recovery of the Berlin office market.
This is also confirmed by take-up in the first quarter of 2026 , with office space take-up of around 151,000 m², which is around 51% higher than in the same period of the previous year (Q1 2025: approx. 100,000 m²), but still remains around 10% below the Dakaden average (Ø 1st Q 2015-2024: approx. 168,400 m²).
In 2019, the short-term supply reserve (available within three months) fell to a completely inadequate 280,000 m². Since then, it has risen again and stands at around 1,850,000 m² at the beginning of 2026 (beginning of 2025: around 1,390,000 m²). The vacancy rate has thus increased to around 8.4% (beginning of 2025: 6.4%) with a total office space stock of around 22 million m².
If one subtracts from this the fluctuation reserve of around 900,000 m² required for the smooth functioning of the market as well as the latent and structural vacancy rate (185,000 m² and 170,000 m² respectively), the surplus of around 600,000 m² is rising again after years of supply deficit.
By the end of 2026 , Aengevelt Research expects the supply reserve to increase further to around 2 million m² .
Since 2020, the volume of new or extensively renovated office space has grown significantly and significantly exceeded the 500,000 m² mark between 2021 and 2023 (2021: approx. 580,000 m², 2022: approx. 750,000 m²; 2023: approx. 617,000 m²). In 2024, there was significantly less new construction space at around 495,000 m².
For 2025 , Aengevelt Research analyses a further decline in completion volume of around 400,000 m² , which is moderately below the decade average (Ø 2015-2024: approx. 422,000 m²).
According to the current state of registration, a completion volume of around 400,000 m² of new office space is expected for 2026.
This means that the supply of sustainable, ESG-compliant office space continues to grow – a positive development, as this space is also the focus of demand for broad, especially international user groups. On the other hand, older, energy-suboptimal properties are losing their attractiveness and are becoming increasingly difficult to market.
The weighted prime rent is stable compared to the previous year at currently around EUR 45/m². This puts Berlin in third place behind Munich (EUR 58/m²) and Frankfurt (EUR 54/m²). The median rent in central locations is also unchanged at around EUR 29/m².
In the course of 2026 , Aengevelt Research forecasts a slight increase in prime rents of around EUR 46/m².