A market commentary by Jürgen Michael Schick
After two years of restraint, confidence is returning to the German residential investment market. Long-term interest rates have stabilized at a level of around 3.5 to 3.7 percent, prices have adjusted, and buyers and sellers meet on an equal footing. This creates what has been missing for a long time: a market with reliable fundamentals.
Stability instead of stagnation
The number of transactions has been increasing noticeably since 2024. Many investors who waited during the high-interest phase are returning to the market. After the price exaggerations at the end of the super cycle, there are now good buying conditions again. In the seven largest cities in Germany, the purchase price factor is now 24 times the annual net cold rent. This is nine annual rents less than at the peak in 2021/2022.A-cities have the same factor today as C-cities in 2021.
The leverage effect returns
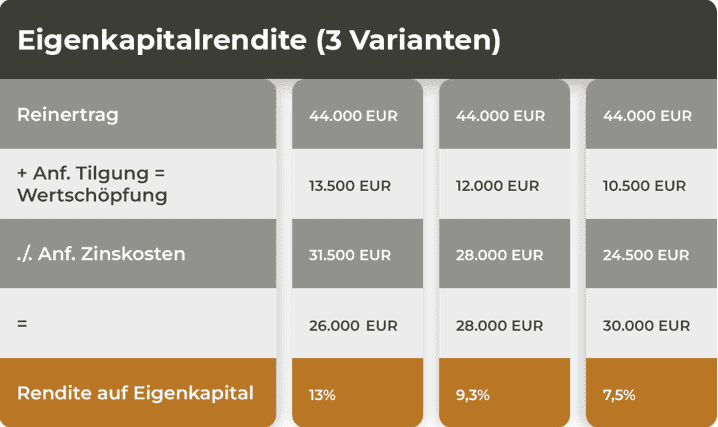
The decisive factor here is that the classic leverage effect is once again effective in residential investments. Returns on equity employed are usually in the high single-digit range, and in the double-digit range with higher debt financing.
An example of an apartment building in a B-town for a purchase price of EUR 1,000,000 and an annual net rent of EUR 55,000 (factor of 18.2) shows it clearly: