

Este artículo se ha traducido automáticamente.


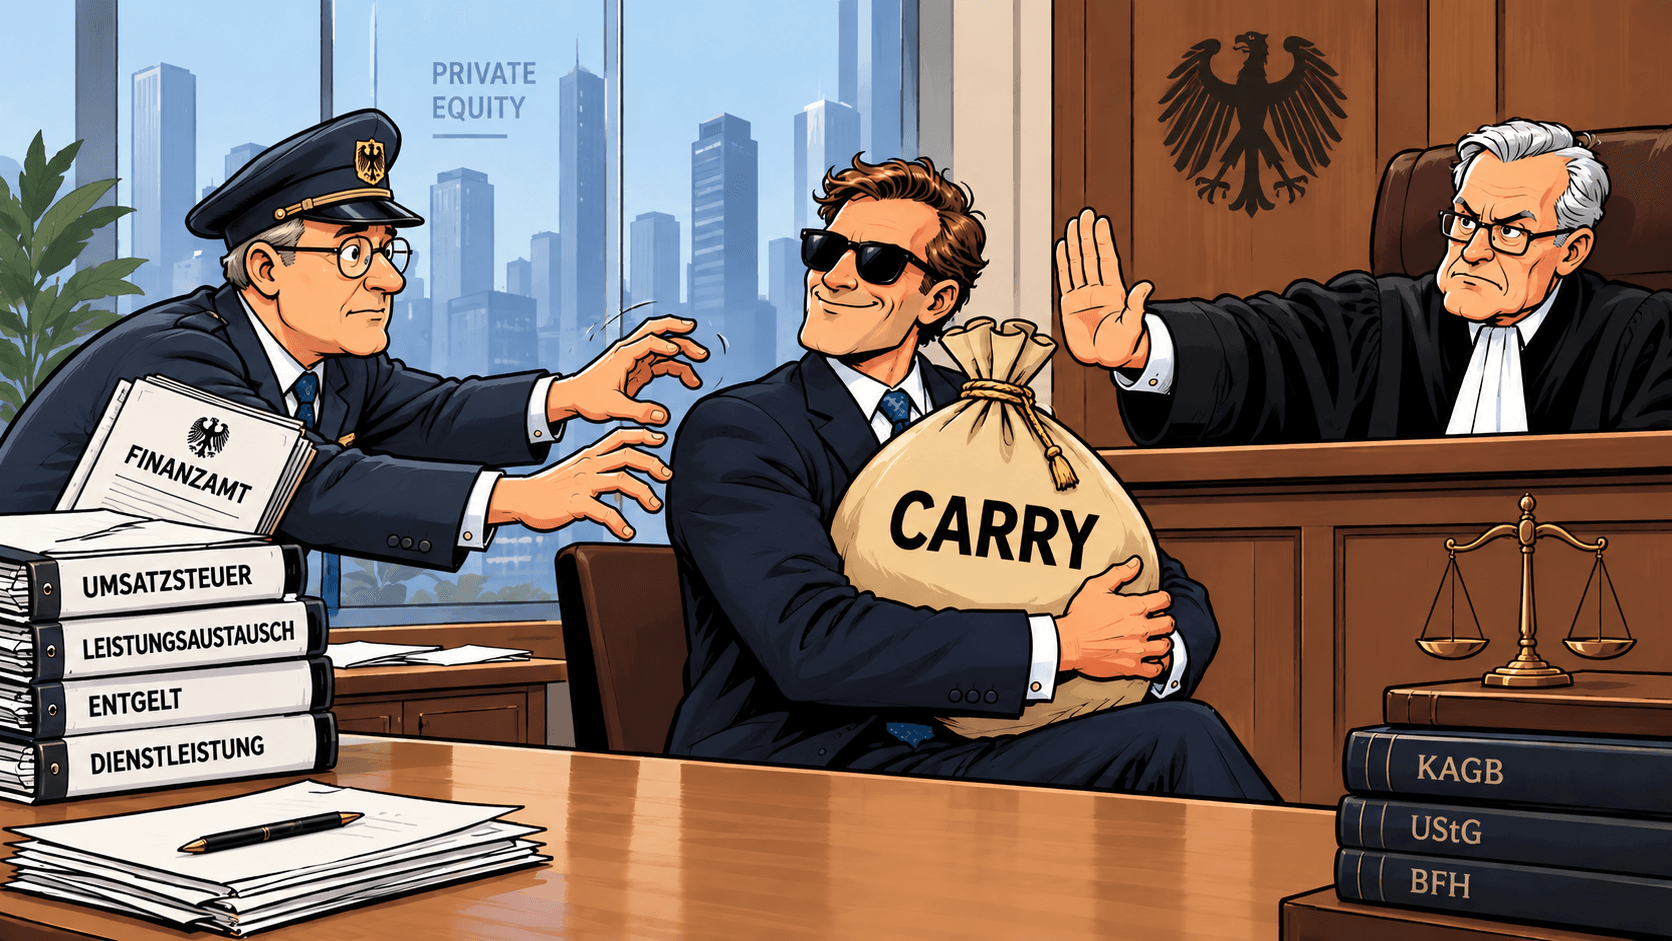
Carried interest is one of the defining remuneration mechanisms of private markets. A recent ruling by the Lower Saxony Fiscal Court deals with its VAT treatment. More interesting than the tax question, however, is the court's reasoning. Because it leads to a more fundamental question: What is Carry actually – remuneration for an activity or participation in joint success?
The basic principle of carried interest is quickly explained. If a fund manager invests capital in a fund himself, he initially participates in the economic success like any other investor. According to his capital investment, he receives a capital-proportional share of the profit.
The actual carry begins where the manager participates in the success beyond this share of capital. Often, this only happens after the investors have received back their invested capital and have also achieved a certain minimum return. What is earned afterwards is no longer distributed solely according to the capital shares. The carry holder receives a disproportionate share of further success.
The Lower Saxony Fiscal Court recently had to deal with such a construction. However, the question was an unusual one: Is the carry subject to VAT?
The court denied this for the case decided. The carry was a participation in the company's success and not a separate remuneration for a service provided by the manager.
With this, the court basically takes the construction of the carry at its word. Of course, the work of a fund manager influences the economic success of a fund. He selects investments, accompanies them and influences their development. However, the fact that good work can be a prerequisite for economic success does not make participation in this success a remuneration for activities.
Rather, the decisive factor is how the payment is measured. In the case of carry, this is not the type and scope of individual services, but the overall economic success of the fund. And in addition to the work of the manager, this depends on numerous other factors: on the development of the investment companies, the market environment, valuations and finally the conditions of an exit.
The manager thus contributes to the success without the carry being used to pay for a specific individual service. The management fee remunerates the activity. The carry participates in the success. This is precisely where its economic peculiarity lies – and the idea of the "alignment of interests".
The Lower Saxony Fiscal Court only had to decide whether the specific carry was to be regarded as consideration for a service for VAT purposes. The last word on this has not yet been spoken: Due to its fundamental importance, the appeal was allowed.
The decision is a reminder of what carried interest is all about: the manager is rewarded for economic success by being disproportionately involved in this success. VAT law has reminded us of this.