The fourth quarter of 2025 was relatively stable despite some economic challenges. Tariff uncertainty decreased, bond yields remained elevated but controlled, and while the war in Ukraine continues, an official ceasefire is in place in Gaza. The French government persevered without passing a budget, and the British budget was well received by the public and the business community.
The economic development was rather modest. Although a recession was avoided, growth remained low. EU industrial production rose by 2.2 percent year-on-year in December, with German production bottoming out and returning to positive growth. France's economy performed positively throughout the second half of the year, while the UK recorded an industrial recovery in November.
The purchasing managers' indices (PMI) in the manufacturing sector pointed to minor changes compared to the previous months. In contrast, services in the major economies lost some momentum. As a result, eurozone GDP growth slowed to 0.2 percent in the fourth quarter compared to 0.3 percent in the third quarter, impacted by weaker French growth and German stagnation.
The European Central Bank (ECB) has been maintaining its exchange rate policy since June. In the future, too, hardly any change in the interest rate level is expected. The inflation rate in the eurozone reached the target of two percent in December and is expected to remain close to this target throughout 2026.
"Low key interest rates, contained inflation and rising household spending items in 2026 suggest a slight to good economic development, although US trade and security policy poses significant risks," says Hela Hinrichs, Senior Director Research & Strategy JLL EMEA, analysing the economic outlook.
Prime office rents: Only in just under half of the metropolises is the price screw turning
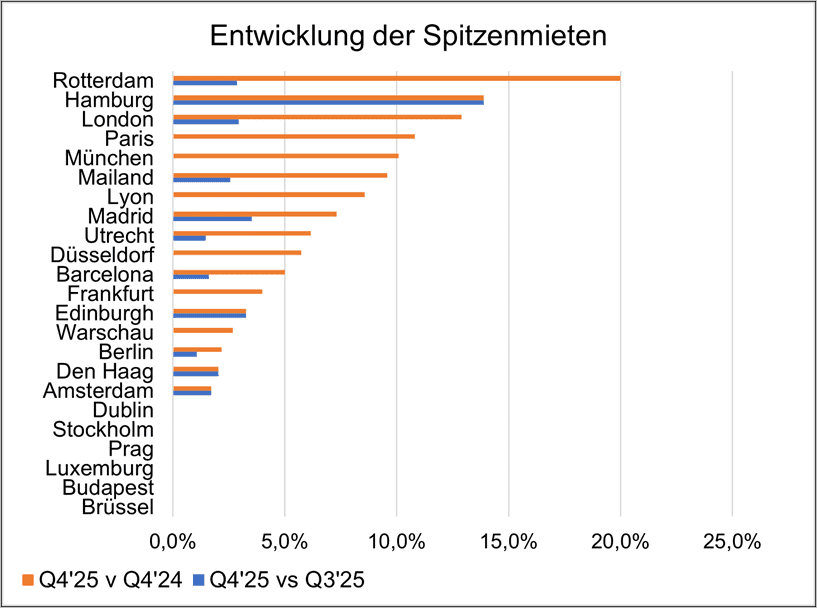
European prime office rents rose by 7.4 percent year-on-year and by 1.7 percent quarter-on-quarter in the fourth quarter of 2025, remaining above the ten-year average.
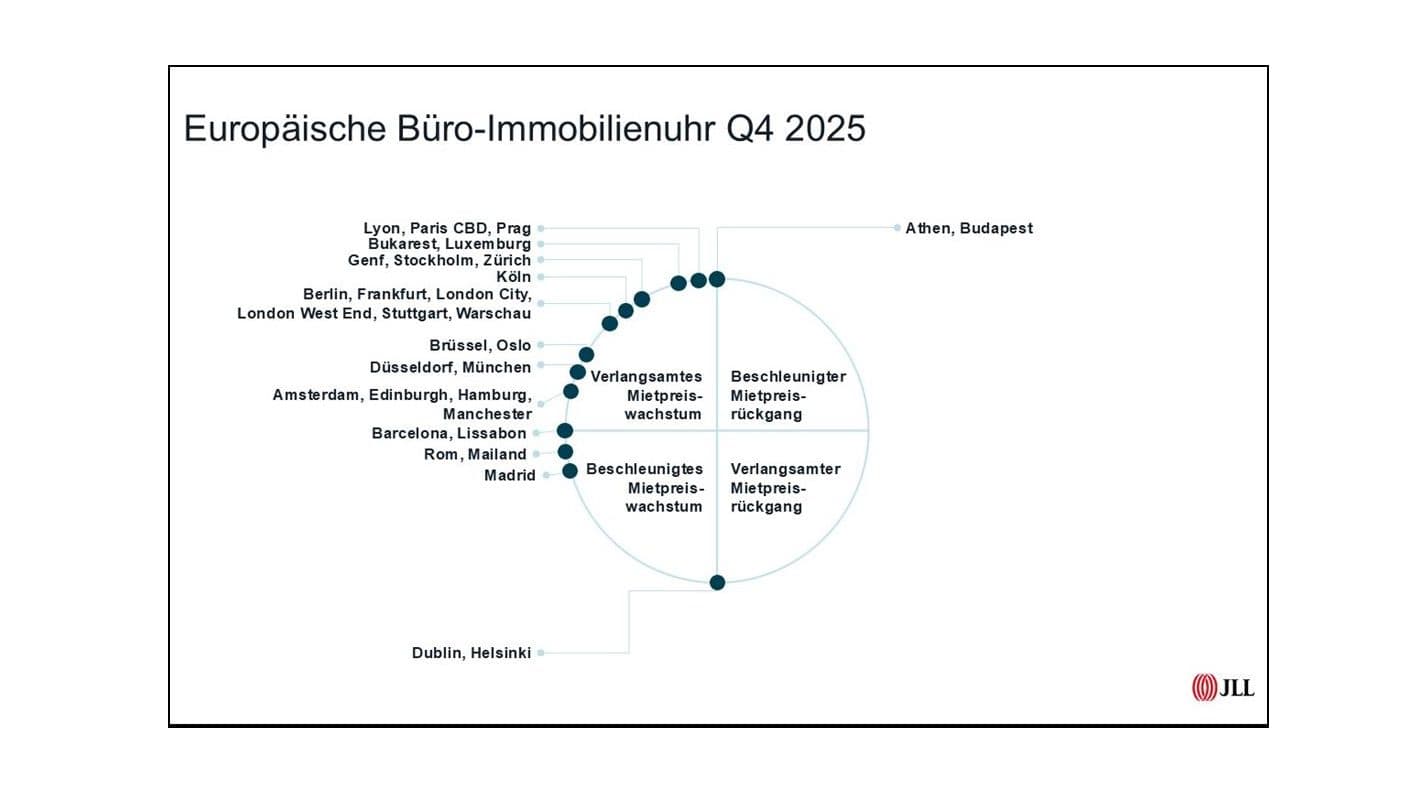
As expected, the increased rents are increasingly playing a role in the location decision and motivating users to consider space outside the central prime locations. Therefore, rental growth is expected to extend from prime office space in central locations as competition in A-locations increases. "The Paris business center is a good example of this. " The market has reached record rents and growth is expected to flatten out or even possibly turn negative by the end of 2026," says Hinrichs.
Rent increases were observed in eleven of the 23 index markets, including Hamburg (up 13.9 percent quarter-on-quarter), Madrid (up 3.5 percent), Edinburgh (up 3.3 percent), London (up 2.9 percent) and Rotterdam (up 2.9 percent). The remaining twelve markets did not record any rental growth in the fourth quarter.