

Yields on prime assets are rising
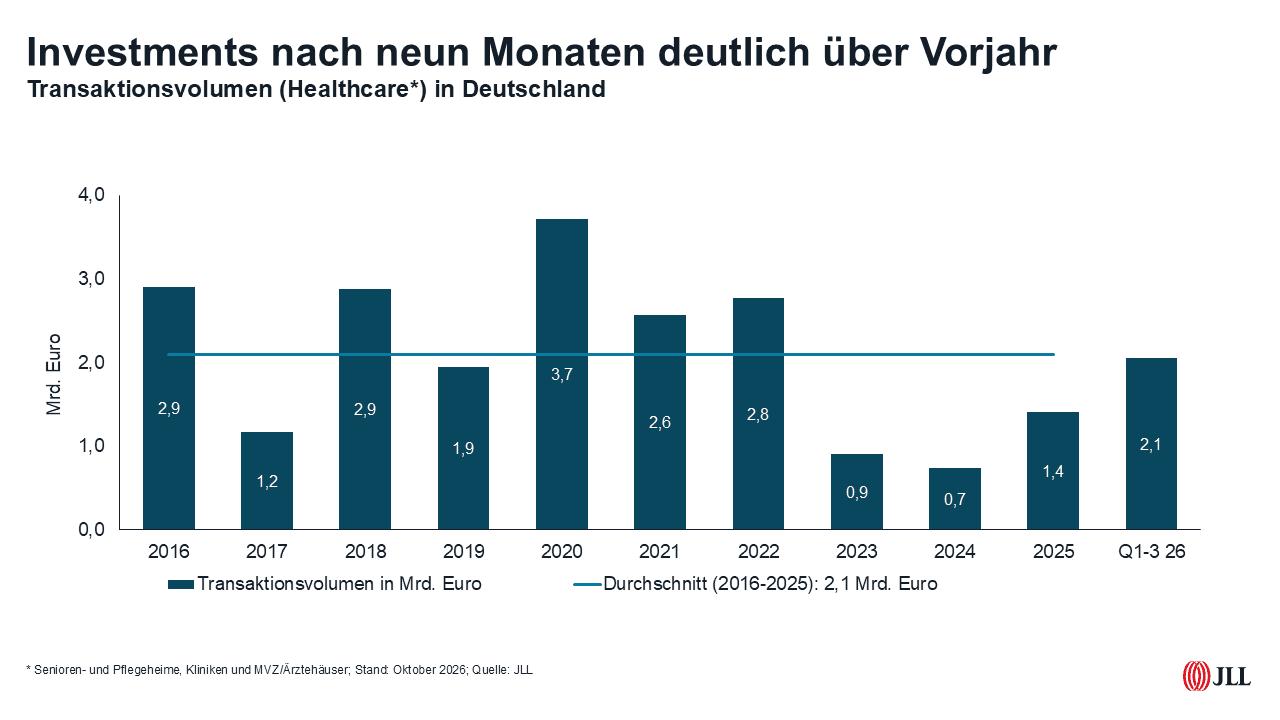
Even after the first nine months, the investment market for healthcare property remains on course for growth. With a transaction volume of 2.1 billion euros, the market has already exceeded the figure for the whole of the previous year by half (1.4 billion euros). Compared with the same period last year (1.24 billion euros), this represents an increase of 70 per cent.
However, the momentum in the third quarter slowed significantly compared with the first two quarters. Between July and September, nine transactions involving care homes, clinics and medical care centres were completed, totalling just around 250 million euros. The first quarter, in particular, had been characterised by major deals, such as the sale of a portfolio comprising 19 medical centres and medical care centres.
The current market conditions are making it difficult to determine prices, particularly for core investments: “Very high-quality assets are the most sensitive to the rise in interest rates. For many, the price calculations simply no longer add up,” explains Peter Tölzel, Senior Director of Healthcare Investment at JLL Germany. Consequently, demand is shifting towards other risk categories with a higher yield profile. “Capital remains available for opportunistic or core-plus properties, and value-add investments in particular are currently in high demand.”
Due to the current market situation, prime yields have been raised. For care homes, the prime yield now stands at 5.25 per cent, which is 15 basis points higher than at the middle of the year.
The high proportion of international business remains striking, standing at 79 per cent after nine months. Among the sub-asset classes, retirement and care homes account for the largest share of total turnover, at 63 per cent. These are followed by hospitals, at 23 per cent, and medical centres and healthcare centres, at 14 per cent.
Interest in medical and outpatient care centres remains strong. However, the right property is often lacking. “It is not uncommon for medical centres to incorporate other uses, such as retail or office space, which is viewed critically by investors. After all, investment managers operate with clearly defined investment profiles and want to avoid any dilution of these criteria for the sake of their end investors,” explains David Keller, Team Leader Healthcare Investment at JLL Germany. As a result, this leads to limited marketability for mixed-use properties in a market phase such as this. “The solution is a yield premium, which in turn attracts a different clientele of buyers.”
He remains confident, however, that further transactions will be finalised in the fourth quarter. There is “volume in the pipeline”, particularly in the field of housing for the elderly. A few small care home portfolios could also find new owners by the end of the year.