

Against the backdrop of ongoing global political tensions, the associated uncertainty and a continuing weakening German economy, there was no year-end rally in the German real estate investment market. Although the 4th quarter was the strongest quarter of the past year with a transaction volume of 9.4 billion euros, sales were at the same time a good quarter below the volume in the final quarter of 2024. For the whole of 2025, sales thus amount to approx. 31.3 billion euros, which represents a decline of 17% compared to the previous year and is only about half as much as the average of the previous ten years.
Karsten Nemecek, Deputy CEO Germany and responsible for Capital Markets, comments on the market as follows: "The last few months reflect the year as a whole: Of the many ongoing transaction processes, only very few resulted in a sale. The others are dragging on or have even been broken off. Although potential buyers and sellers are increasingly converging in their price expectations, there are market segments for practically all types of use in which the gap is still large and hardly any transactions take place. On the other hand, there are definitely segments in which transactions take place reliably. In addition to good existing apartments, this also includes small to medium-sized office buildings in prime locations. In the future, the significant increase in the number of transaction processes in all asset classes last year is also likely to translate into more deals."
Sharpest decline in take-up in logistics and residential real estate
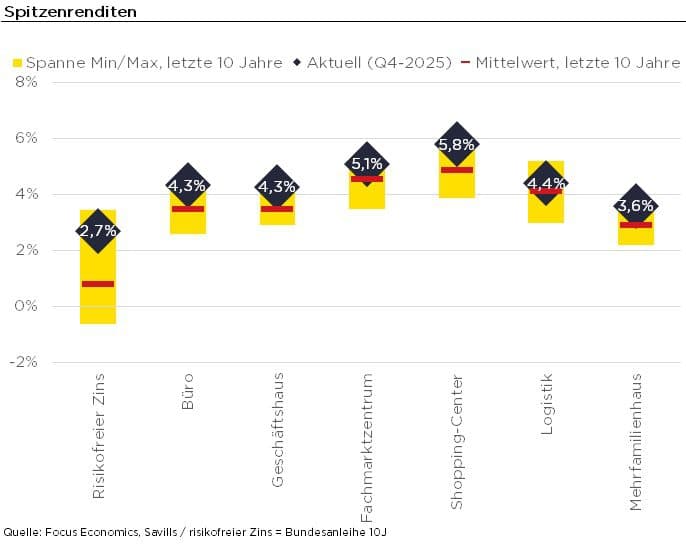
Residential real estate remained by far the type of use with the highest turnover (approx. EUR 8.1 billion), although the transaction volume fell by 23% compared to 2024. The decline in take-up was even more pronounced at -38% only for industrial/logistics properties, which ranked fourth with a transaction volume of approx. 5.1 billion. In the case of retail and office properties, take-up remained stable compared to the previous year. A transaction volume of approx. EUR 6.1 billion and EUR 5.6 billion respectively means rank 2 and 3 in the sales ranking. Revenue from healthcare and social real estate reached EUR 1.2 billion, slightly above the previous year's figure. Prime yields remained largely unchanged. Only in some of the top 6 markets did initial yields for prime office properties fall by a few basis points over the course of the year.