Dit artikel is automatisch vertaald.


Despite the failure of the traffic light coalition, the Bundesrat approved the Annual Tax Act 2024 (JStG 2024) at its meeting on 22 November 2024. The law will generally come into force one day after its promulgation on 2 December 2024 and contains a large number of tax changes in various areas of German tax law. It also includes the following changes, which are of great importance for the real estate industry.
In addition to the Annual Tax Act 2024, there are currently about 20 other tax bills or ordinances, but none of them have yet been passed by the Bundestag. After the "traffic light phase-out", it can be assumed that these legislative projects will no longer be implemented.
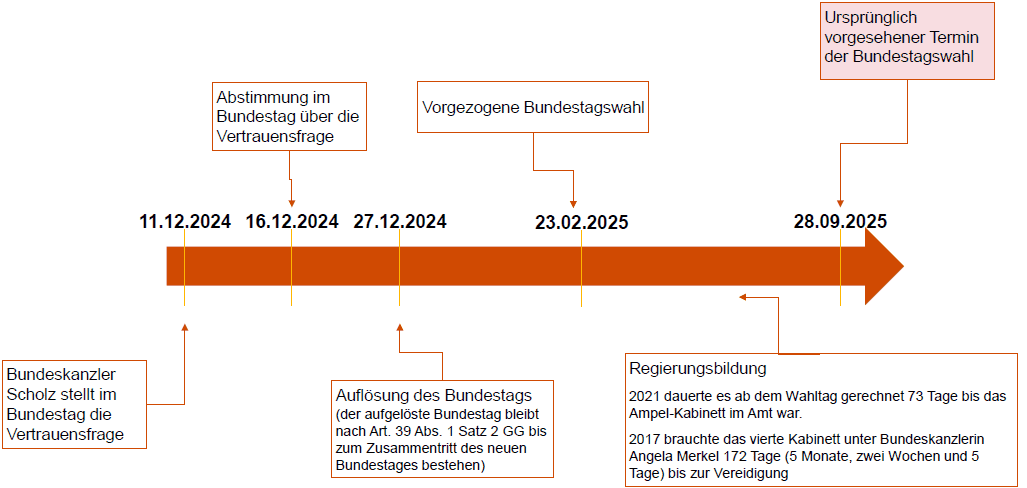
However, on 13 December 2024, the parliamentary groups of the former traffic light surprisingly agreed on the implementation of selected measures from the Act on the Further Development of Tax Law and the Adjustment of the Income Tax Tariff (Tax Development Act) before the early Bundestag election on 23 February 2025. According to reports, the reduced Tax Development Act is essentially only to include an increase in the basic tax-free allowance, the tax-free child allowance and child benefit from 2025. Highly controversial measures such as the introduction of a national notification obligation for tax arrangements are not part of this agreement.
No further tax legislative projects are expected until 23 February 2025. Even after that, it will take several months before a government is formed and new legislative projects are initiated or old legislative projects are reactivated. Particularly relevant for the real estate industry is the question of whether the new government will take up the proposal of the expert commission "Simplified Corporate Tax" to abolish the simple and extended reduction for real estate companies.
Significant tax innovations can be triggered not only by legal changes, but also by court decisions. The following two procedures that could trigger a tax earthquake should be highlighted here.
Regardless of changes in the law and case law, there is a considerable need for taxpayers to take tax action at the turn of the year. Examples of this are:
If you would like to read more, the "Key Tax Issues at Year End for Real Estate Investors" provides an overview of key tax options and deadlines for the turn of the year in Germany and in 35 other countries worldwide. The 2024/2025 edition can be found under www.pwc.com/KTI.
The Annual Tax Act 2024 contains numerous positive innovations for the real estate industry.