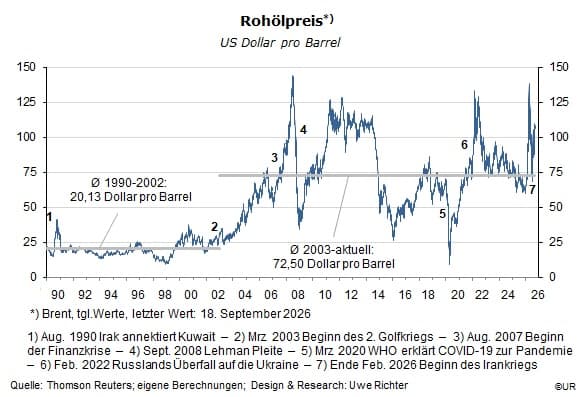
In the decade and a half up to 2002, the oil price for Brent crude oil was reasonably stable on average at around 20 dollars. After that, it embarked on a wild ride, with several large swings, from about 25 to 130 dollars and an average value of around 73 dollars, driven by wars in the Middle East and Ukraine, the Corona pandemic and the global financial crisis of 2007/2008. At the beginning of this year, the world market price was about 60 dollars, which was already very high from a historical point of view, and has now reached 103 dollars. There is no clear trend.
From an economic point of view, $20 seems at first glance to be something like the "equilibrium price", a price at which supply and demand meet most of the time. Today's price of $103 per barrel would therefore be far above its "normal" level. The question is whether it will go back there when peace returns to the Middle East one day and a less erratic government comes to power in the United States.
But perhaps there is no equilibrium price in principle – the only possible statement can only be whether oil is expensive or cheap right now. It is quite expensive compared to the prices of the last decades, and extremely expensive compared to the values of the 1950s and 1960s, when $2 to $3 per barrel was normal on the world market. Oil is a scarce resource that is no longer multiplying, while demand has been increasing year after year.
Meanwhile, for countries that have to import net oil, high oil prices mean that their real incomes are shrinking or growing more slowly than in the past – import prices are rising faster than export prices. Households and businesses have to cut back on spending or cannot increase it as usual. The greater the dependence on oil imports, the more the economy suffers from this so-called terms of trade effect.
Since it is a zero-sum game globally, the net exporters of oil (and natural gas) are the big winners, especially the USA, Iran and the rest of the countries around the Persian Gulf, Nigeria, Venezuela, Norway and, last but not least, Russia. The international distribution of income has changed significantly, mainly to the detriment of the European Union and all other countries that have to import net oil.
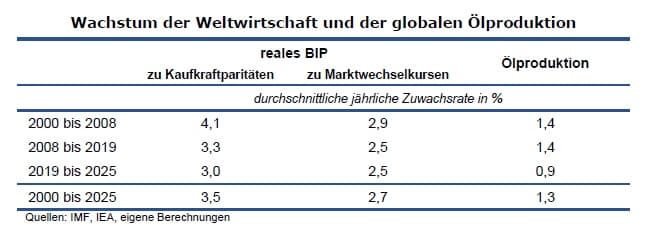
Another effect: If the relative prices for fossil fuels rise, this is of course good news for all those who fear that the earth is heating up too much. After all, the increase in CO2 emissions is a direct consequence of more and more oil and gas being burned. There is no end in sight. For some time now, the rule of thumb has been in place: the world's real GDP (on the basis of purchasing power parities) has been growing comparatively steadily by a good 3 percent per year, and oil production is no less steady by almost 1.5 percent.
However, the goal must be to reduce greenhouse gas emissions. It will not work without even higher prices. Achieving this in a socially acceptable way will be one of the great challenges of economic policy.
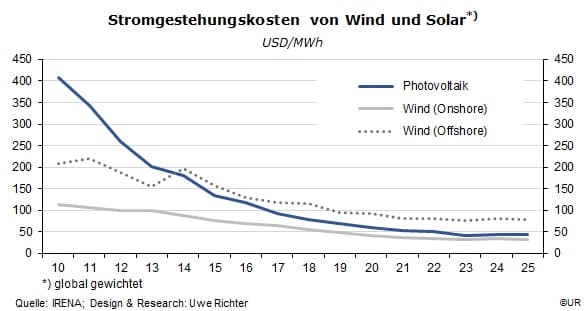
Hope is given by the fact that the global economy is becoming increasingly electrified and that electricity from alternative, environmentally friendly sources is being produced both relative to fossil fuels and increasingly cheaply in absolute terms. The cost of "green" electricity is now also lower than that of nuclear power plants, including those that have already been largely depreciated.
For the time being, however, it can unfortunately be assumed that the climate will continue to deteriorate for decades
So what? Is crude oil expensive or not?
In recent years, political events have been the most important determinant. If the wars in the Middle East and Ukraine continue and intensify, supply chains are likely to rupture, so that even a doubling of prices is conceivable. On the other hand, the climate could deteriorate to such an extent that even die-hard advocates of fossil fuels such as the Americans and Russians will have to step on the brakes and have no choice but to effectively increase duties and taxes on oil and natural gas and expand the electric infrastructure. Bans on internal combustion engines could be added. Both would reduce demand and thus prices on the world market. In the longer term, demand for oil and gas is also likely to decline due to unbeatably low "green" energy costs and the switch to "green" hydrogen.
There is also the question of whether there could soon be a so-called Minsky moment: If oil prices have risen sharply for a while (as has been the case recently), a point is likely to be reached at some point where the momentum comes to its natural end, where further significant price increases become less likely – because, for example, central banks raise interest rates out of concern about even higher inflation rates and there can basically be no unlimited growth in the long term. This would make a switch to money market securities and bonds attractive, trigger profit-taking on the oil market, perhaps followed by panic and a crash. A further decline in the oil price to a value in the neighborhood of 20 dollars would be possible.
I think that in the short term a renewed rise in the price of oil cannot be ruled out for political reasons, but that in the longer term a significant decline is inevitable for the reasons I have mentioned.