

Den här artikeln är automatöversatt.


The line is in place, the tone is friendly but firm: With the "Call for Evidence for an Impact Assessment" called for participation in constructive criticism of the SFDR – and not at some point, but only recently. Under scrutiny: the previous classification system with Articles 8 and 9, the disclosure requirements and the famous Principal Adverse Impacts (PAI). What remains? What could change? What is the further timetable?
The EU Sustainable Finance Disclosure Regulation ("SFDR") is an EU regulation that obliges financial market participants to disclose information about their sustainability performance. The aim is to create more transparency about sustainable investment products and avoid greenwashing.
It is undisputed that the goals pursued by the SFDR are meaningful. However, the regulatory scheme has proven to be far too complicated for the actual achievement of the target. This is associated with sheer application overload and excessive bureaucracy. In response to this, product providers have demonstrated an overcompensating implementation skill, although in some places this has been able to show exaggerated tendencies that miss the focus of measurable effectiveness factors. There is no automatism that well-designed SFDR engineering makes a meaningful contribution to sustainability goals and fund strategy. This critical finding has already been highlighted in another article by the author .
Criticism of this was not kept behind the fence. The commission was open to emerging doubts and dissatisfaction. To channel this criticism from industry, the Commission launched a comprehensive evaluation of the SFDR back in December 2022. These included public consultation, technical workshops with industry and discussions with Member States and regulators. After this past problem assessment, the CfE now focuses on involving the industry through constructive criticism in the form of concrete suggestions for improvement.
The CfE was sent out on 2 May and until 30 May. the participants had time to make their entries . In short, the CfE comprises three main thematic blocks to which participants should refer in terms of content:
The Commission is seeking to streamline and reduce disclosure requirements by focusing on providing investors with only the most important information, which may lead to targeted changes and clarifications to existing SFDR disclosures. In the retail fund industry, for example, there is significant support for simplifying SFDR disclosures and for managers to have more leeway in disclosing the required information instead of having to adhere to a prescribed template.
Simplifying key concepts: Consideration will be given to introducing product categories that are easy for retail investors to understand, take into account different sustainability objectives and take into account current market practices in terms of available data and financial products. In the CfE, the Commission has put forward three possible options for future product classification:
The Commission is also at odds with the PAI indicators. PAI stands for "Principal Adverse Impacts", i.e. the significant negative effects of investment decisions on the environment and society. Financial market participants are to use the PAI indicators to disclose the damage their investments could cause. However, the existing PAI indicators are not always practicable, meaningful and also not consistent with neighbouring regulatory fields (CSRD, EU taxonomy). Therefore, the Commission asked for feedback on whether the PAIs should be clearly focused, e.g. on key KPIs. In addition, the PAIs are to be better aligned with whether data is available for measurement at all, especially for illiquid assets.
A final overview of the exact responses received specifically to this Call for Evidence is not yet publicly available as a complete list. At present, isolated reactions are publicly available, for example from IIGCC (The Institutional Investors Group of Climate Change), EBF (European Banking Federation), Eurosif (European Investment Forum). On the supervisory side, for example, the Autoriteit Financiele Markten AFM (Netherlands), the Federal Financial Supervisory Authority BaFin (Germany) and the Financial Market Authority FMA (Austria) have expressed their views in the Joint Letter to the Commission on the Revision of the SFDR of 27 May 2025 . The full evaluation of all comments by the Commission will probably not be achieved until late summer 2025 .
As a not complete, but nevertheless more far-reaching intersection of the individual public reactions, there are similarities on the following topics:
Autoriteit Financiele Markten AFM (Netherlands), the Federal Financial Supervisory Authority (BaFin) (Germany) and the Financial Market Authority FMA (Austria) have specifically addressed the topic of product categorisation in the Joint Letter to the Commission on the Revision of the SFDR:
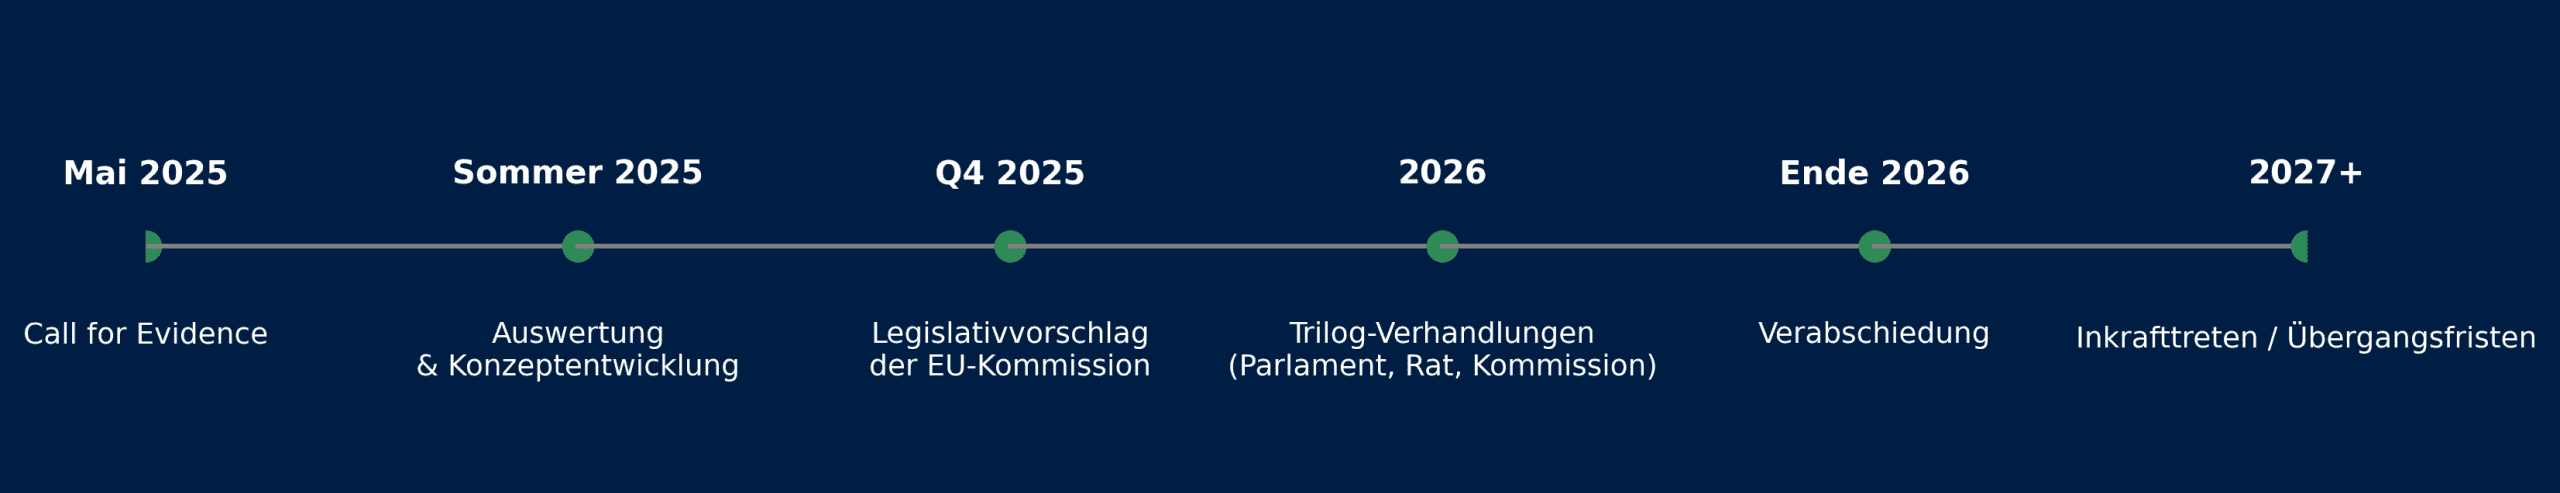
The Call of Evidence was now the kick-off stage in the implementation of SFDR 2.0. Further stages will follow, with the finish line or the entry into force of the new SFDR 2.0 rules announced for the beginning of 2027.