BNP Paribas Real Estate publishes logistics market data for the 1st half of 2026
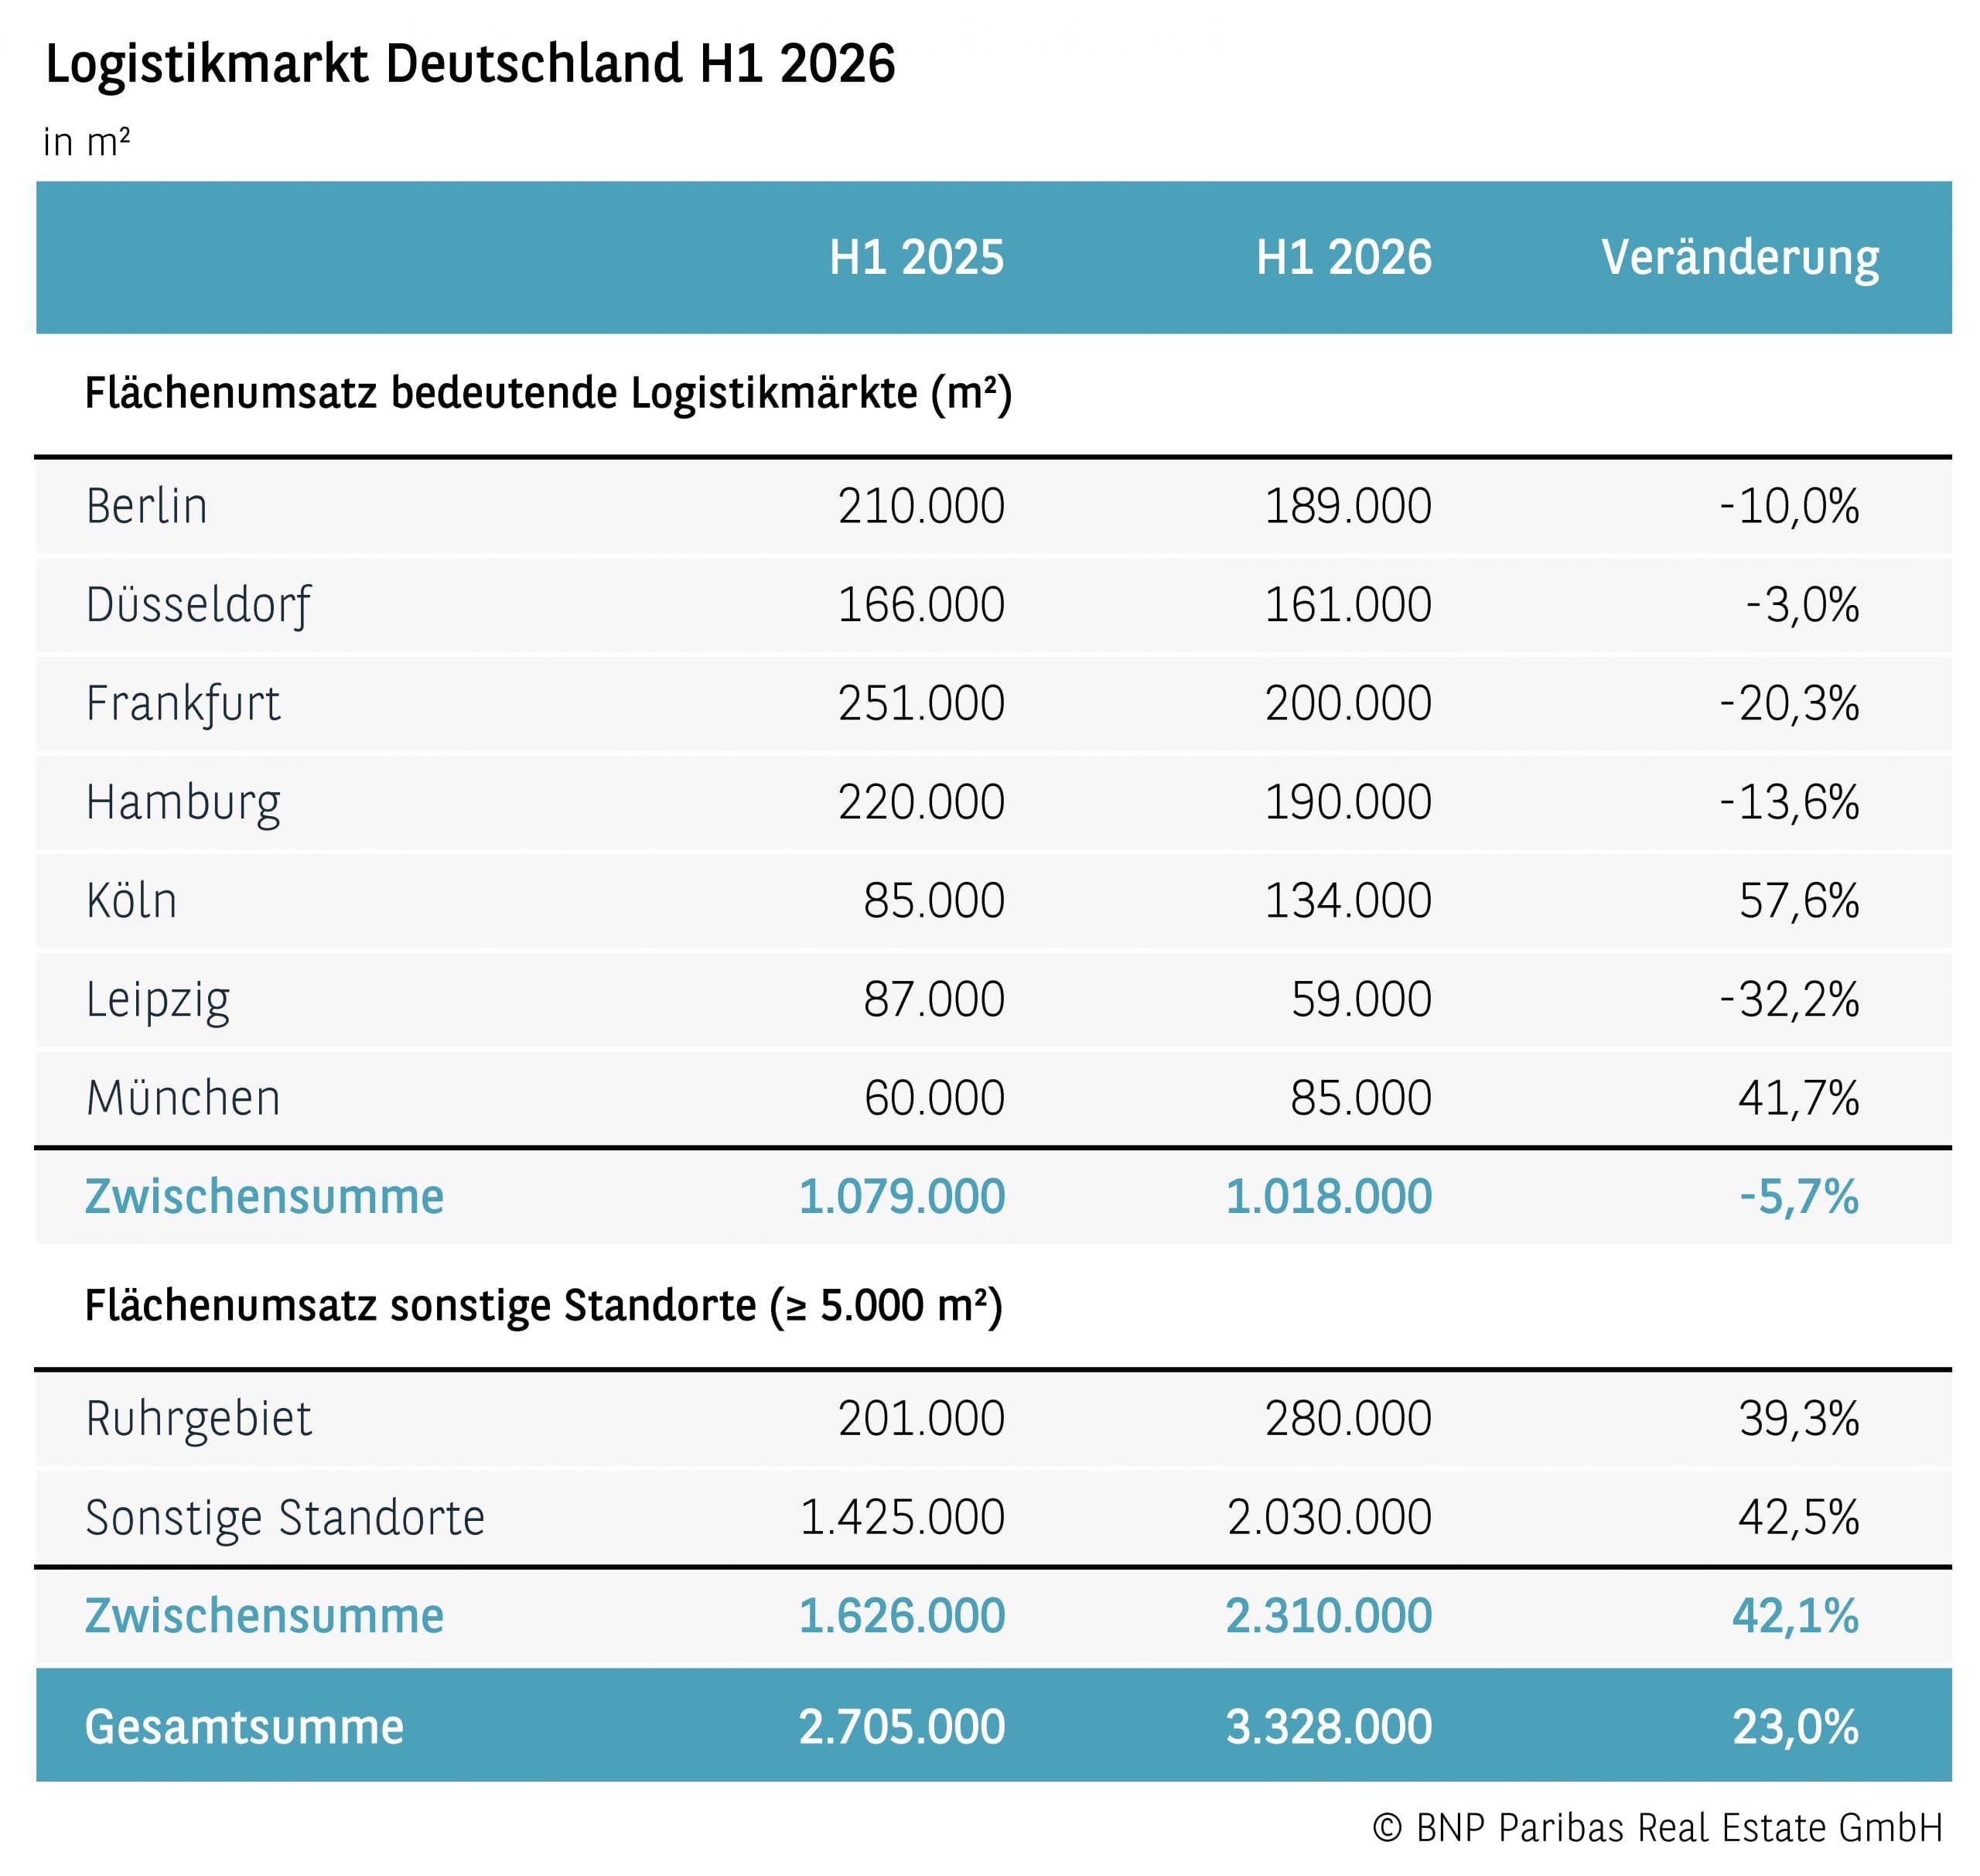
The nationwide warehouse and logistics space market continues its impressive growth trajectory and closes the 1st half of the year with take-up of a good 3.3 million m². This result is around 23% higher than in the previous year and also slightly above the ten-year average (+4%). The second quarter was able to increase by almost 16% compared to the first three months of the year. This result is all the more remarkable in view of the economic and geopolitical conditions, which were further burdened in particular by the Iran war and the conflict over the Strait of Hormuz. This is the result of the analysis by BNP Paribas Real Estate.
"Overall, there is brisk market activity with a high number of contracts, with significantly more large deals of 20,000 m² or more being concluded than in previous years. This segment alone is responsible for around half of the total turnover and is thus at the second-highest level of the past ten years. Only in 2022 was a significantly higher volume sold in this category. Logistics service providers remain by far the largest demand group, with a market share of 44% and numerous large-scale contracts. The trend that has been going on for some time now that companies in the e-commerce sector are increasingly commissioning logistics service providers to handle their business is continuing. This applies above all to companies from the Asian region, especially from China, but also to other online retailers such as Amazon, which are expanding more strongly again," explains Christopher Raabe, Managing Director and Head of Logistics & Industrial at BNP Paribas Real Estate GmbH.
The top logistics markets (Berlin, Düsseldorf, Frankfurt, Hamburg, Cologne, Leipzig and Munich) achieved a combined take-up of 1,018,000 m² by the middle of the year, which corresponds to a decline of almost 6% after the high result of the previous year. Frankfurt achieves 200,000 m²
(-20%), followed by the markets of Hamburg (190,000 m²; -14 %) and Berlin (189,000 m²; -10 %), which are almost on a par. While Düsseldorf with 161,000 m² was only slightly below the previous year (-3%), Cologne achieved the highest increase with 134,000 m² (+58%). Munich also increased take-up by almost 42% to 85,000 m², while demand in Leipzig has so far been relatively moderate (59,000 m²; -32%). In contrast, the polycentric Ruhr region recorded very high market momentum and closed the 1st half of the year with a volume of 280,000 m² (+39%). Outside the major logistics hubs, take-up totals 2.3 million m², which corresponds to a significant increase compared to the same period last year (+42%) and exceeds the ten-year average by 12%.