

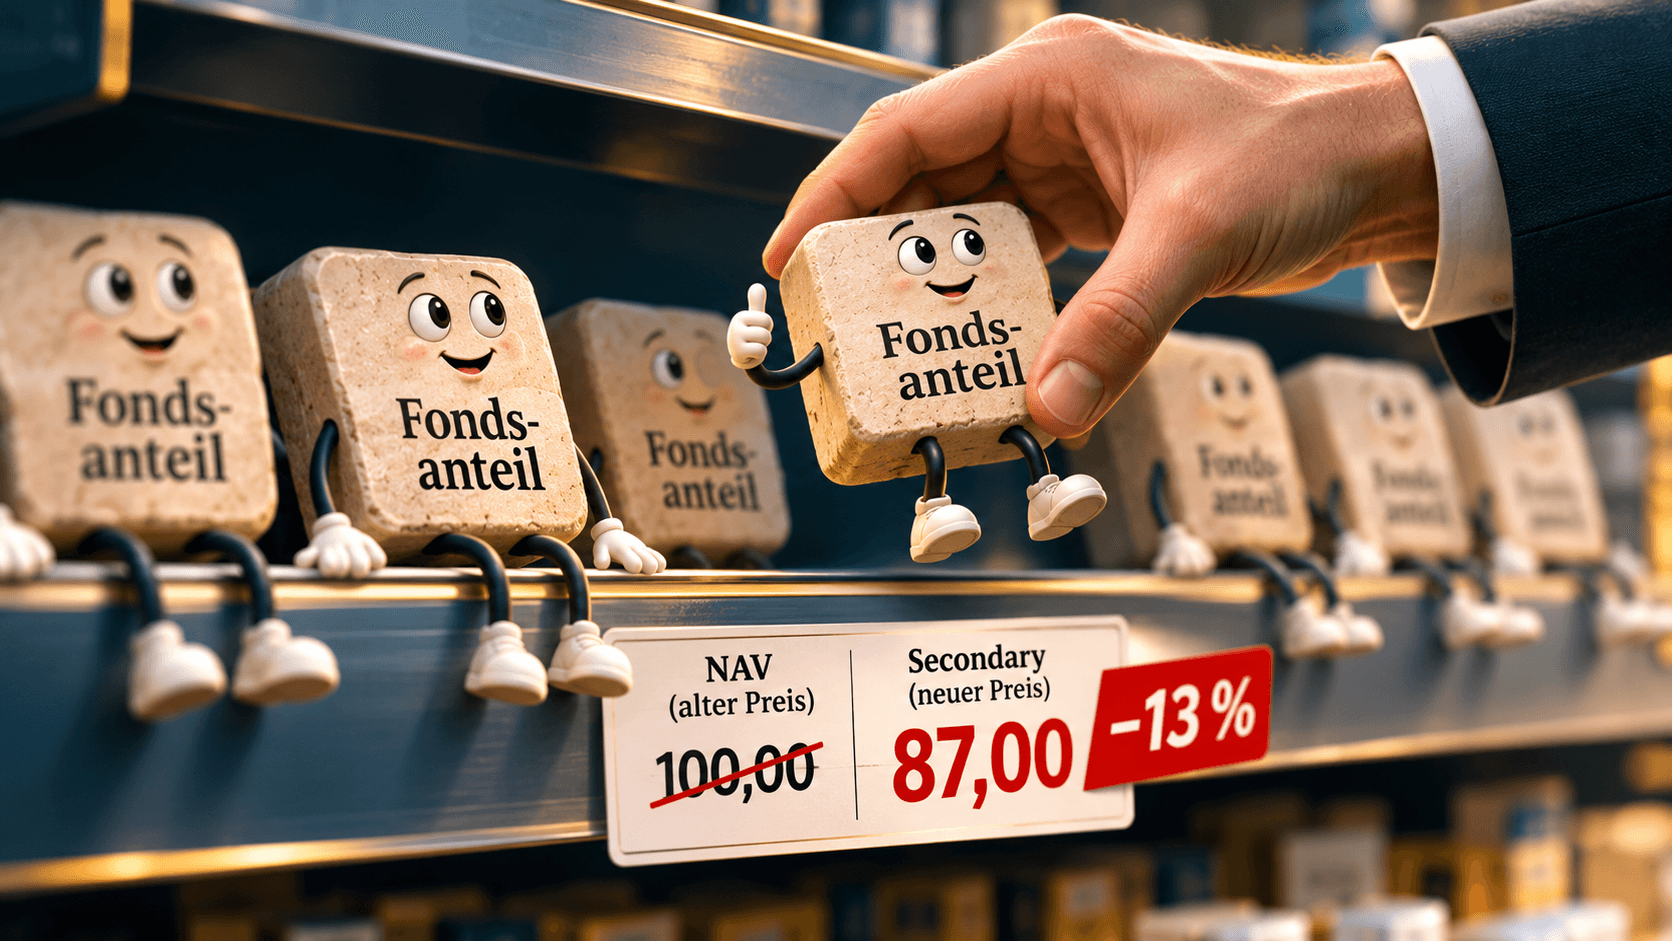
Private-market fund units are often traded on the secondary market at a price below their stated net asset value. There is more to this than just a lack of liquidity.
When the purchase price and NAV diverge
In June 2026, the JPMorgan Private Markets Fund acquired twelve stakes in private equity funds for US$77.4 million. As at the same valuation date, the buyer assigned a fair value of US$94.5 million to these investments. The difference of US$17.1 million represented a calculated premium of just over 22 per cent on the purchase price.
No profit had therefore yet been realised. Nor does the difference represent a discount on the target funds’ previously reported NAVs, as the higher valuation was set by the buyer, albeit possibly using the target funds’ valuations. The transaction does, however, raise a fundamental question: what is a private-market investment actually worth if there is a significant discrepancy between the purchase price and the carrying amount?
According to Jefferies, the global secondary market reached a record volume of $240 billion across various private markets asset classes in 2025, including LP- and GP-led transactions. Traded LP fund interests changed hands on average for 87 per cent of their net asset value (NAV). For buyout funds, the figure was 92 per cent; for venture and growth funds, 78 per cent; and for property funds, just 70 per cent.
Illiquidity premium or valuation discount?
A 30 per cent discount on property funds can hardly be explained in the same way as an eight per cent discount on buyout funds. Sellers may need liquidity in the short term. However, buyers may also take a more pessimistic view of future returns, debt levels or realisable values than the fund managers do.
The NAV is calculated in accordance with established procedures; however, in the case of unlisted investments, it remains dependent on valuation assumptions. The secondary market price arises from a specific transaction and also reflects liquidity requirements, market depth and bargaining power.
A study published in October 2026 by Greg Brown and William Volckmann of the Institute for Private Capital at the University of North Carolina analyses just under 3,000 price observations for private equity buyout funds between 2015 and 2025. Secondary prices were, on average, around eight per cent below NAV and moved in close tandem with the public equity markets – an indication of cyclical market and liquidity conditions.
An earlier study by Nadauld, Sensoy, Vorkink and Weisbach on secondary transactions involving private equity fund holdings – in particular buyout and venture capital funds – found an average NAV discount of 13.8 per cent for the period 2006 to 2014. In the sample analysed, the buyers achieved a market-adjusted return advantage over the sellers. The authors discuss, amongst other things, the provision of liquidity and information asymmetries as possible explanations.
The discount alone therefore reveals little about the attractiveness of a secondary transaction. It may present an additional opportunity for returns if the seller places greater value on liquidity than on the long-term value of their holding. However, it may also simply foreshadow a correction in valuations that will only be reflected in the NAV at a later date.
Who earns the commission – and who bears the risk?
Anyone who ties up capital for the long term expects a higher return in return. If they have to sell early, part of this benefit may pass to the secondary buyer. The latter may get a more favourable entry price, but also assumes the remaining risks.
What is interesting here is the role played by evergreen funds. They can acquire units in closed-end funds at a discount, whilst their own investors do not necessarily have the right to redeem their units at any time. The UNC study identifies evergreen funds in more than a quarter of the secondary pricing instances observed, without demonstrating any robust systematic effect of their involvement on prices.
For investors, therefore, it is not only the reported NAV performance that counts, but also the actual liquidity of their fund units. Those who can wait until the underlying investments are realised do not have to accept a premature secondary market discount. Those who need to exit earlier, however, may well have to.
📌 Conclusion
The illiquidity premium is not necessarily earned by the party who originally tied up their capital. A portion of it may also be received by the party who provides liquidity at the crucial moment. Whether a discount actually represents such a premium or merely prices in economic risks only becomes apparent in the cash flows realised at a later date.
Sources
JP Morgan Private Markets Fund – Consolidated Schedule of Investments, 30 June 2026 (SEC); see page 4 for ‘Secondary Investments’ and, in this regard, only those dated 30 June 2026 in the ‘Acquisition Date’ column.
Jefferies – 2025 Global Secondary Market Review, February 2026