

Este artículo se ha traducido automáticamente.


The Fund Risk Limitation Act (draft bill BMF) sets out until 16. April 2026 will amend EU Directive 2024/927. A transitional period until 2027 applies to existing funds, which was preceded by intensive debates – including at the Financial Stability Board (FSB) and the Organization of Securities Commissions (IOCSO).
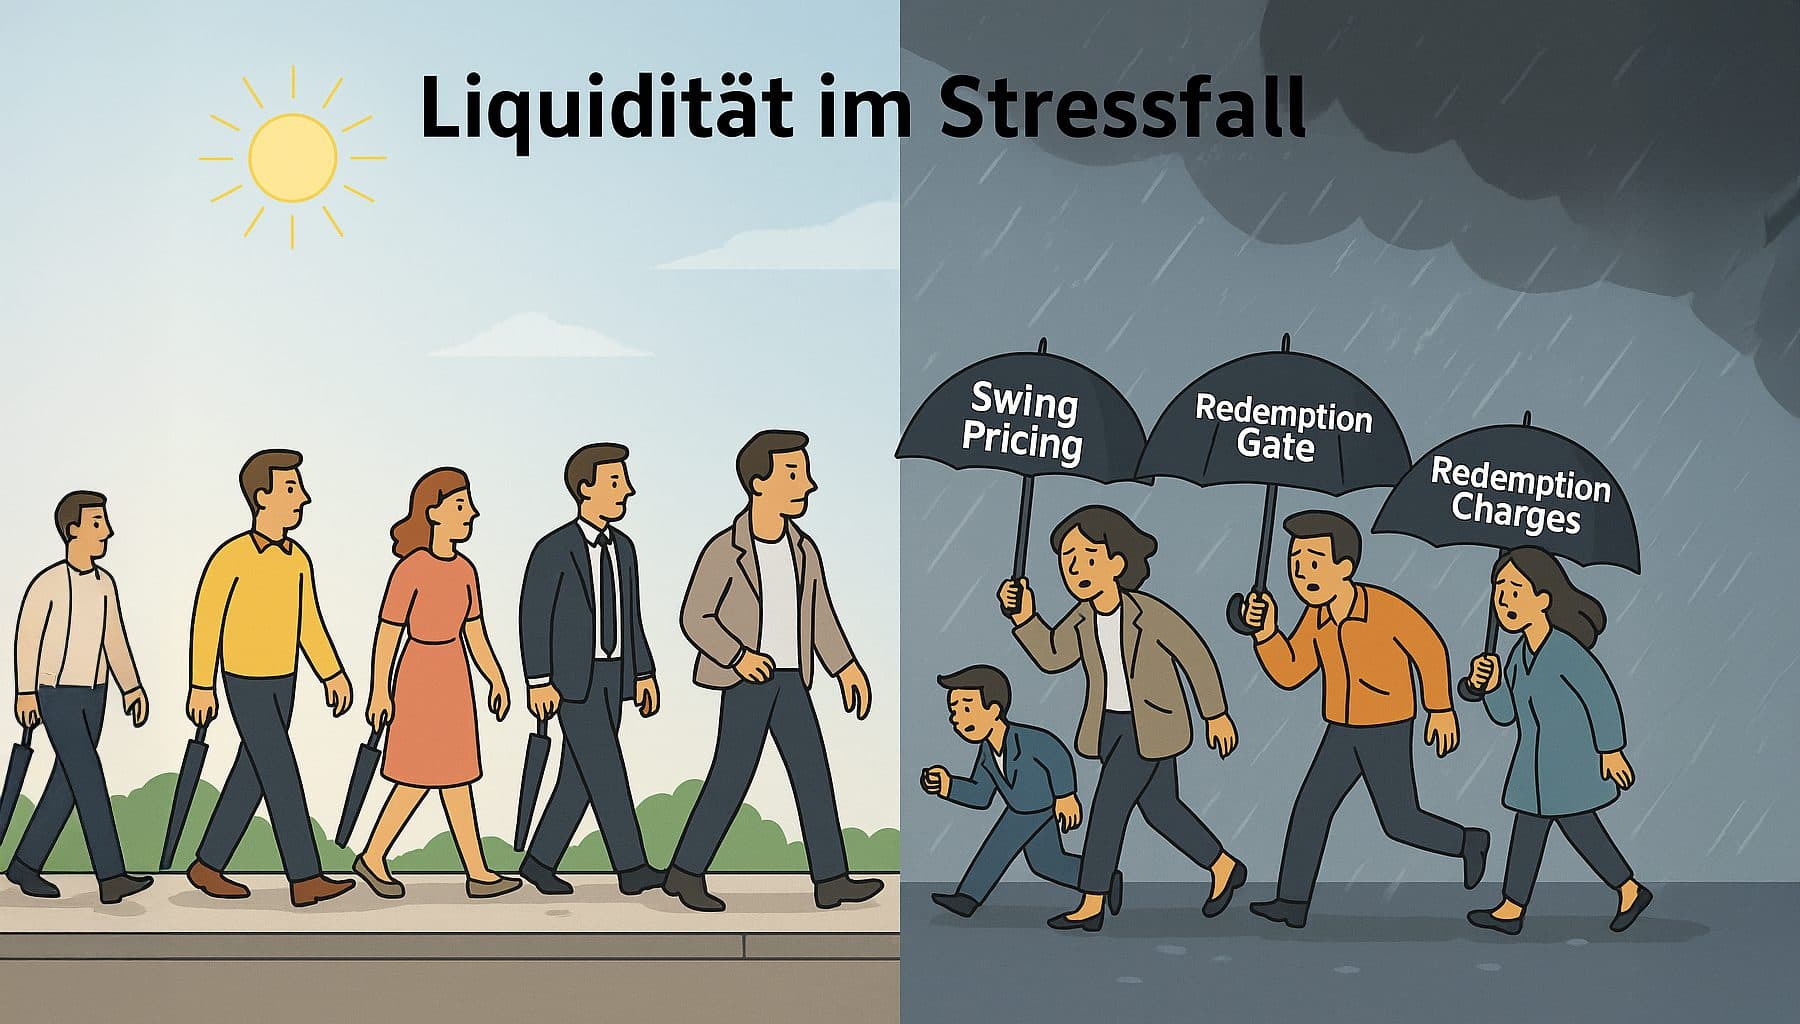
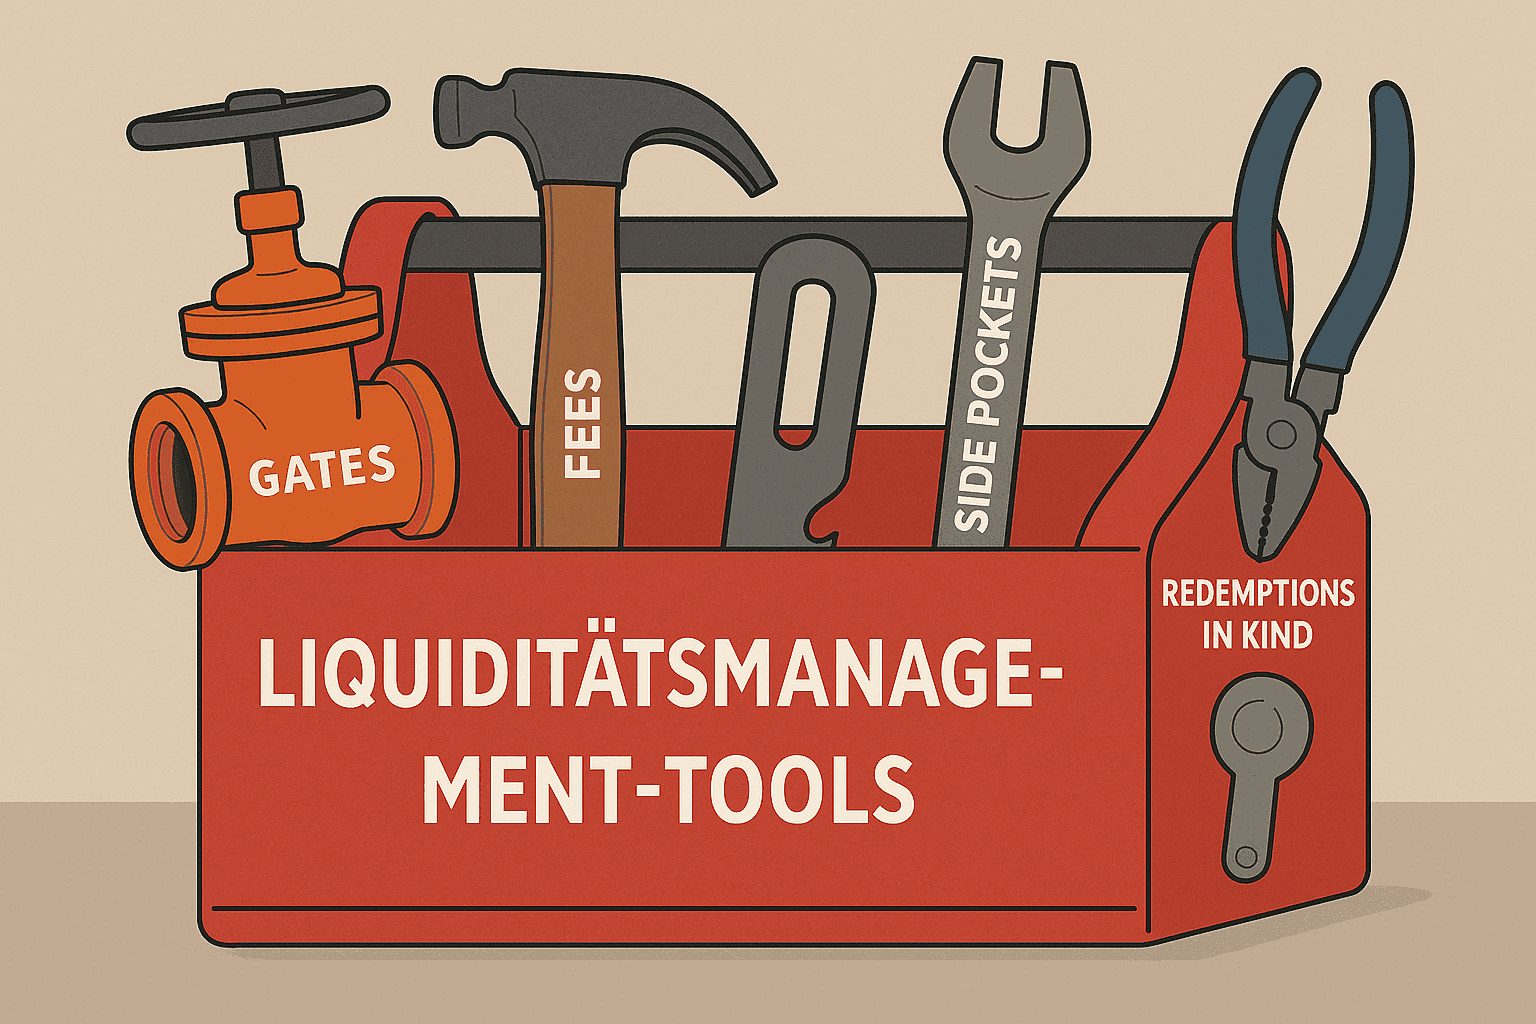
In future, open-ended investment funds – i.e. UCITS and open-ended AIFs – will have to include at least two LMTs in their documents (money market funds: one LMF). The goal is a balancing act:
LMTs have been in practice for some time, but so far voluntarily. Now the selection will be mandatory and monitored by the supervisory authority. In addition to swing pricing, side pockets and anti-dilution mechanisms, the following are particularly relevant for open-ended real asset AIFs:
The AIFMs are quite flexible in the selection of LMTs, with the guidelines set by the Final Report submitted by ESMA to the EU Commission on 15 April 2025 with the Draft Regulatory Technical Standards (RTS) and the guidelines on LMTs .
How effective are LMTs really?