

Following a ruling on Portugal, the Federal Fiscal Court is examining whether the taxation of certain corporate restructuring measures is compatible with European law.
In June, this column reported on a noteworthy judgement by the European Court of Justice under the heading ‘Conflict in share deals: national tax law and the protection of the free movement of capital within the EU’. The Nova Iberomoldes case (C-837/24) concerned the treatment under land transfer tax of a corporate restructuring within a group of companies.
Unlike in a traditional property share deal, the focus here was not on the sale of a property company to a new investor, but on the contribution of a stake in a property-owning company in exchange for shares in that company.
The ECJ has set limits on taxation. The European Capital Accumulation Directive protects certain transactions under company law from indirect taxation. The fact that a company owns property does not automatically justify an exception to this protection.
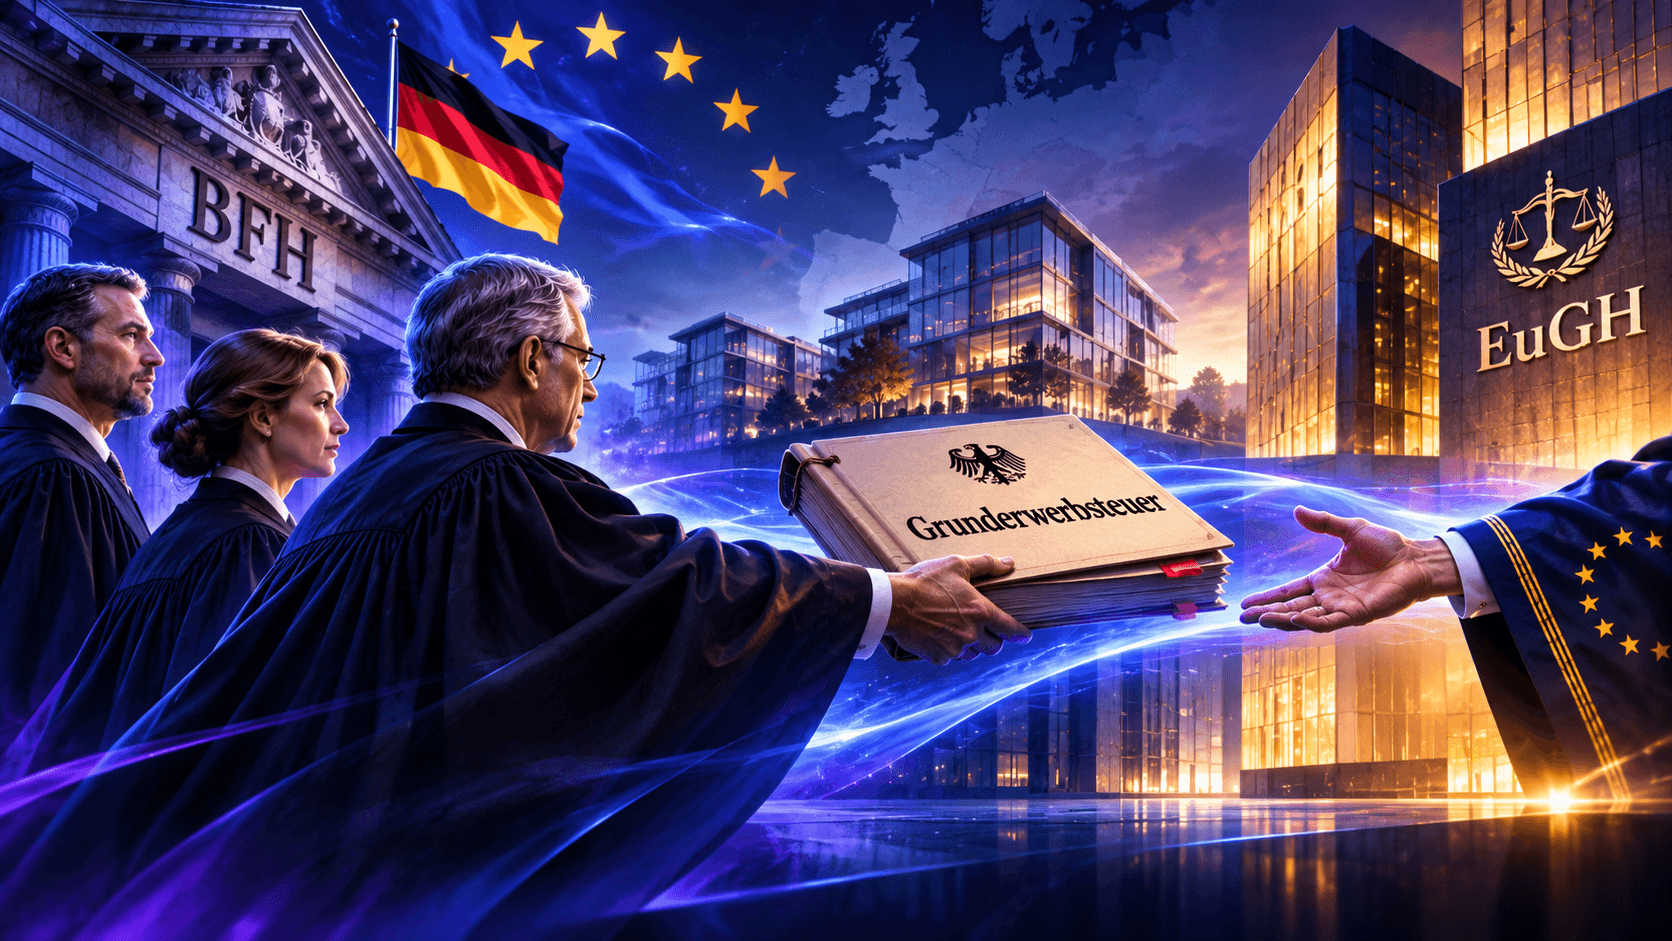
The thinking at the time was: Could this ruling also have implications for the German property transfer tax? And lo and behold: this question has now reached the European Court of Justice – on the initiative of the Federal Finance Court itself.
Two cases, the same conflict under European law
The German case BFH II R 8/23 also concerns a reorganisation within a group of companies. As a result of a cross-border merger, at least 95 per cent of the shares in German property companies were indirectly transferred to another group company. The properties themselves, however, did not change hands.
Nevertheless, the tax office assessed land transfer tax. This was based on a provision of the German Land Transfer Tax Act which treats certain transfers of shares as equivalent to the acquisition of land.
This raises a legal question very similar to that in the Portuguese case: may a Member State impose land transfer tax on an intra-group restructuring under company law, even though the transaction may be protected by the European Capital Accumulation Directive?
The facts of the cases and the national tax provisions are not identical. However, both cases concern the same conflict between national law on land transfer tax and European protection of corporate restructuring.
Noteworthy: In 2024, the Federal Fiscal Court (BFH) saw no reason yet to refer the matter for a ruling
In its judgement of 25 September 2024 (II R 36/21), the Federal Fiscal Court had ruled that the Capital Accumulation Directive did not apply to the relevant German land transfer tax legislation. At the time, it did not consider it necessary to refer the matter to the European Court of Justice.
Following the Nova Iberomoldes judgement of 4 June 2026, the situation has changed. By order of 16 September 2026, the Federal Fiscal Court (BFH) has now referred questions to the European Court of Justice (ECJ) regarding the compatibility of German taxation with the Capital Accumulation Directive.
It stands to reason that the Portuguese judgement was a key catalyst in this regard. However, the referral does not yet entail an explicit departure from its previous case-law.
Austria has already responded
It is worth noting that the Austrian tax authorities have already drawn practical conclusions from the Portuguese ruling.
In an administrative notice updated on 29 July 2026, the Austrian Federal Ministry of Finance clarified that certain contributions, mergers and other restructuring measures may fall within the scope of the European Capital Accumulation Directive.
For transactions that are clearly covered, the tax authorities should therefore not levy land transfer tax. Under certain conditions, it may even be possible to dispense with the tax return or self-assessment. For other scenarios, however, the Ministry continues to regard the legal situation as unclear.
Why this may be significant for property investors
The economic significance is obvious. Even a reorganisation of shareholdings within a group can trigger substantial land transfer tax liabilities for property companies, even though no land is being sold and there is not necessarily a change in beneficial ownership at the group’s top level.
In the case of a property portfolio with a land transfer tax base of, for example, 500 million euros, a tax rate of 6 per cent would theoretically result in a tax liability of 30 million euros. Such a tax can significantly undermine the economic benefits of a restructuring or even prevent it altogether.
For property funds, investment companies and cross-border property groups, the decision is therefore potentially of great significance. Depending on the outcome of the proceedings, certain restructurings that were previously subject to tax may be assessed differently in future.
It is expressly not a question of the general tax exemption of property share deals. The sale of a property company to a new investor is not automatically covered by the protective provisions under European law discussed here. Nor are intra-group transactions tax-exempt solely on the grounds that they take place within a group.
📌 Conclusion
In June, the potential implications of the Portuguese ECJ ruling for Germany were still an open question. Austria has since already drawn tax consequences for certain restructuring measures, whilst the Federal Finance Court in Germany has itself referred the question of European law to Luxembourg as part of pending legal proceedings. It remains to be seen whether the ECJ will in fact limit the German land transfer tax in relation to the restructuring measures in question. However, the proceedings are already demonstrating just how far-reaching the consequences of a decision under EU law can be for the structuring and management of property investments.