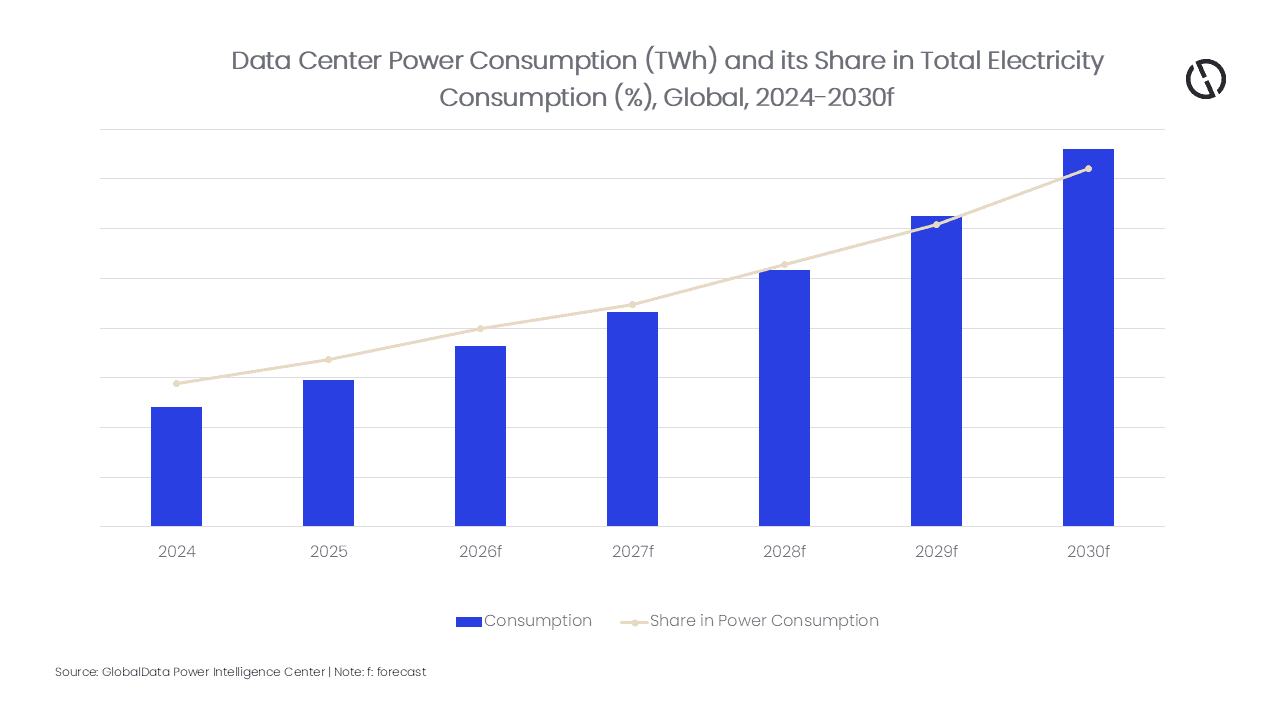
Data centers are rapidly becoming mission-critical digital infrastructure, evolving from back-end IT sites into strategic platforms for cloud, connectivity, and data-driven services. Growth is being driven by cloud and hybrid adoption, surging data traffic, and demand for secure, resilient environments, boosting colocation and hyperscale builds while AI is supercharging expansion with high-density graphics processing unit (GPU) workloads. Against this backdrop, data center power consumption is projected to triple, at a compound annual growth rate (CAGR) of 21.1% from 2024 to 2030, according to GlobalData, a leading intelligence and productivity platform.
GlobalData's latest report, "Powering Data Centers Market Report: Power Consumption, Capacity, PUE and Project Pipeline Analysis and Country Ranking Forecast to 2030," reveals that the US and China remained the largest markets, accounting for 38% and 24.2%, respectively, of the global data center power consumption in 2024 due to their concentration of hyperscale and colocation capacity and strong digital and AI ecosystems. This balance is expected to shift by 2030, with China projected to surpass the US, reaching about 30.1% and rising further to 33.6%.
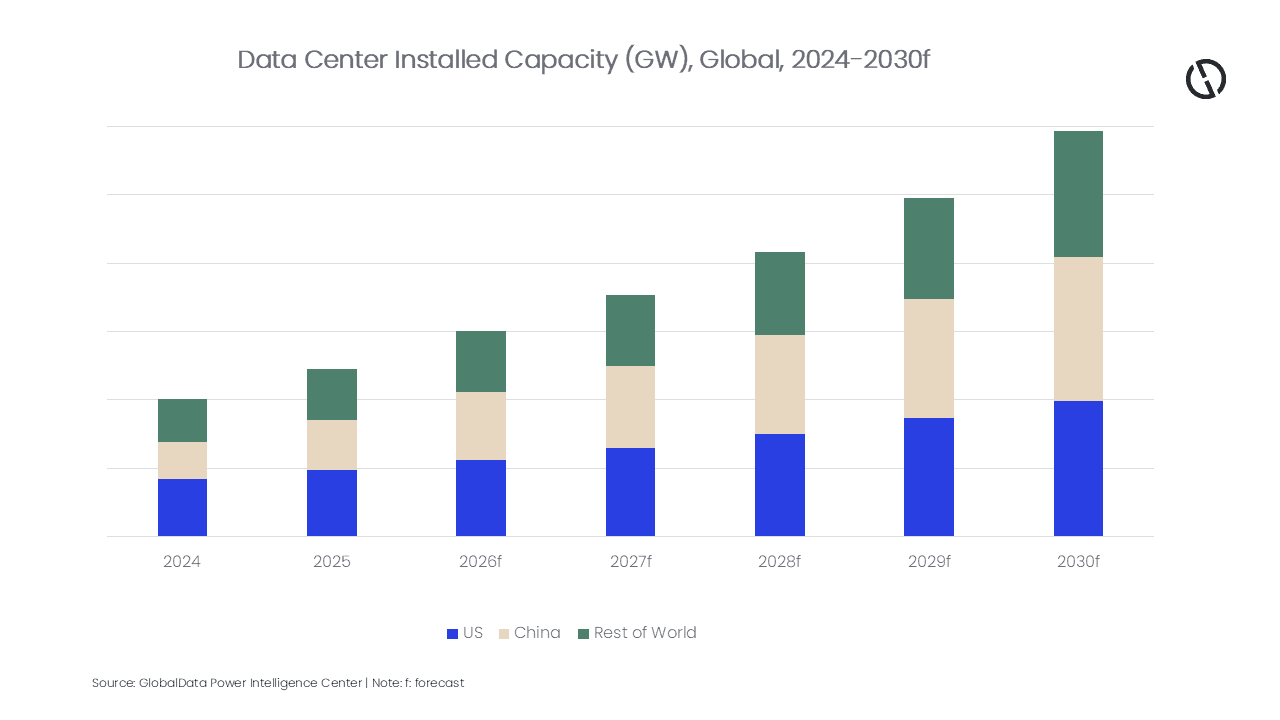
Rehaan Shiledar, Power Analyst at GlobalData, comments: "The global data center installed capacity is projected to surge by 2030, delivering nearly a threefold expansion within just six years. China is expected to lead this growth engine, scaling from 27% in 2024 to 35% by 2030. While the US is projected to remain the second-largest market, currently at 42%, its share is expected to decline to 34% by 2030. Even in 2030, China and the US together account for about 69% of the market, implying that global data center capacity will remain heavily concentrated in two geographies."
Installed data center capacity across the rest of the world is projected to hold steady at approximately 31% from 2024 through 2030. The Asia-Pacific region (APAC) is expected to outpace other geographies, supported by accelerating digitalization, cloud adoption, and sustained infrastructure investment. Markets including India, Russia, Japan, South Korea, and Australia have sizeable project pipelines, with developments spanning the full lifecycle from planning and permitting through construction and commissioning.