BNP Paribas Real Estate publishes market figures for Q3 2026
The picture in the retail investment market after the first three quarters of 2026 is mixed: on the one hand, an above-average number of transactions was recorded compared with the last three corresponding periods. This is according to an analysis by BNP Paribas Real Estate.
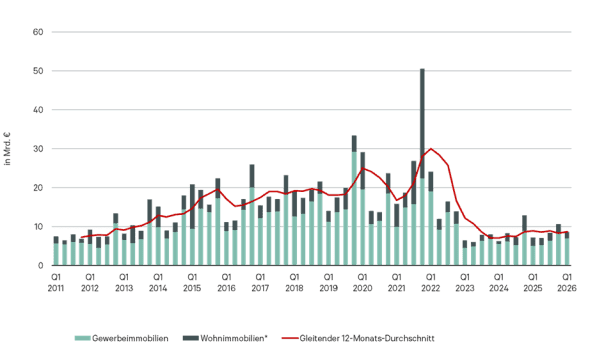
“However, part of the truth is also that this is not reflected in investment turnover – which, at just under €3.1 billion, has fallen by just under 25 per cent compared with the same period last year – due to a historically low average deal size of only €17 million. This was due to very subdued market activity over the last two quarters, which, at €892 million in Q1 and €829 million in Q2, were both well below the €1 billion mark. “However, the Retail division was pleased to demonstrate right at the start of the year that quarterly turnover of almost €1.5 billion is still possible even in the current market climate,” explains Christoph Scharf, Managing Director of BNP Paribas Real Estate GmbH and Head of Retail Services. In Q1, this figure stood at around €1.37 billion.
The largest sales in the current year continue to have been recorded in the first half of the year: in the portfolio sector, the sale of the Powerfood portfolio – comprising 37 food shops and retail parks – is particularly noteworthy, whilst in the individual deals segment, the prestigious high-street properties Alsterhaus in Hamburg, the Alte Akademie in Munich and the Höfe am Brühl shopping centre in Leipzig are worth mentioning. In addition to the Alte Akademie, a total of around 50 mostly smaller commercial property investments were recorded, and an increase in profit was achieved (25 per cent). However, the food and specialist retail sector remains clearly dominant, accounting for over 45 per cent of the volume and 57 per cent of the deals. Shopping centres also recorded a good number of transactions and account for just under 18 per cent of the total, whilst department stores currently make the smallest contribution to earnings at almost 12 per cent.
A-class cities with higher turnover and individual high-value deals; net prime yields are rising across all segments
A-grade locations have recorded a significantly stronger first three quarters this year compared with 2025: with around €1.14 billion, they have achieved a 37 per cent increase in turnover compared with the same period last year (€832 million), driven mainly by smaller investments. Overall, almost all top investment markets recorded higher results in the first nine months.
The southern and northern metropolises of Munich (€349 million) and Hamburg (€247 million) top the list – led by the two major high-street deals involving the Alte Akademie and the Alsterhaus. Düsseldorf (€212 million) and Berlin (€202 million) have also generated significant contributions to turnover. Whilst the capital of North Rhine-Westphalia has seen the sale of the Carsch-Haus and a series of smaller, often luxury-anchored high-street properties, the assets in the Powerfoods portfolio located in the capital are making a significant contribution. By contrast, the markets of Frankfurt (€79 million), Stuttgart (€42 million) and Cologne (€7 million) contributed only marginally to the result.
Net prime yields showed changes across all property types over the course of the year: DIY stores (+60 basis points; 6.40 per cent) and shopping centres (+30 basis points; 6.10 per cent) have seen the most significant increases since the end of 2025. However, yields for retail parks (4.75 per cent), individual food retailers (5.00 per cent) and high-street properties (3.50 per cent) also had to be adjusted upwards by between 5 and 10 basis points.
Outlook
Although the retail investment market was characterised by relatively subdued activity in both the second and third quarters, the high number of deals and the relatively broad distribution of turnover across the various property sectors, in particular, give cause for optimism. This is also evident in a comparison of asset classes, where the retail sector holds its own against the other two leading segments – office and logistics properties – in terms of the number of transactions.
Furthermore, it should be noted that, in the retail sector in particular, the deal pipeline is considerably larger and market sentiment is noticeably better than the investment volume would suggest: in this context, both the marketing initiatives already underway and those recently launched harbour very good revenue potential in the short to medium term. This applies not least to food and specialist retail investments, which – given the numerous transaction processes currently in the preparatory phase – could at any time make the difference between a moderate and a strong final quarter. Alongside the momentum in the food portfolios that have been placed, the high-street segment is also repeatedly in the spotlight, with retail properties housing internationally renowned luxury retailers in particular being able to generate strong demand.
“Further upward trends are evident in prime yields, meaning that the current figures for the various property types and cities could well rise again by the end of the year,” said Christoph Scharf.
Link to the market report: https://www.realestate.bnpparibas.de/marktberichte/retail-investmentmarkt/deutschland-report