This article is translated automatically.


Under the question "How do you assess the influence of current developments on your company?", the participants were able to choose from the same spectrum of possible effects for their company as in the previous surveys, whereby multiple answers were possible. These include:
The biggest concern, namely a reduction in new business, has fallen continuously since summer 2023 from 79% at the time to 48.7% in the summer of 2025. In the current winter survey, the figure has now risen again to 52% for the first time.
In second place are fears of a slowdown in sales momentum. Here, too, there is a trend reversal: While the proportion of survey participants in the summer of 2025 fell significantly by around 14 percentage points to 38.2% compared to winter 2024/25 (56%), the value in the current survey has now increased moderately again by around two percentage points to 40.4%.
The proportion of those expecting bad debts has risen more significantly, namely by around nine percentage points to 27.0% (summer 2025: 18.4%).
The strongest increase is with regard to concerns about the loss of regular customers: While the proportion of survey participants here was only 2.6% in the summer of 2025, the figure in the current survey has more than quadrupled to around 11.5%.
This is accompanied by growing fears among survey participants regarding staff reductions in their companies: While their share fell to 9.2% in the summer of 2025, the figure has now risen again to 13.5%.
Falling values can only be observed in the expectation of increased costs due to previously uncalculated restart investments (25% = -2.6 percentage points), while the value for feared sales of previously necessary real estate, including to strengthen equity, remains almost unchanged at 3.8% (summer 2025: 3.9%).
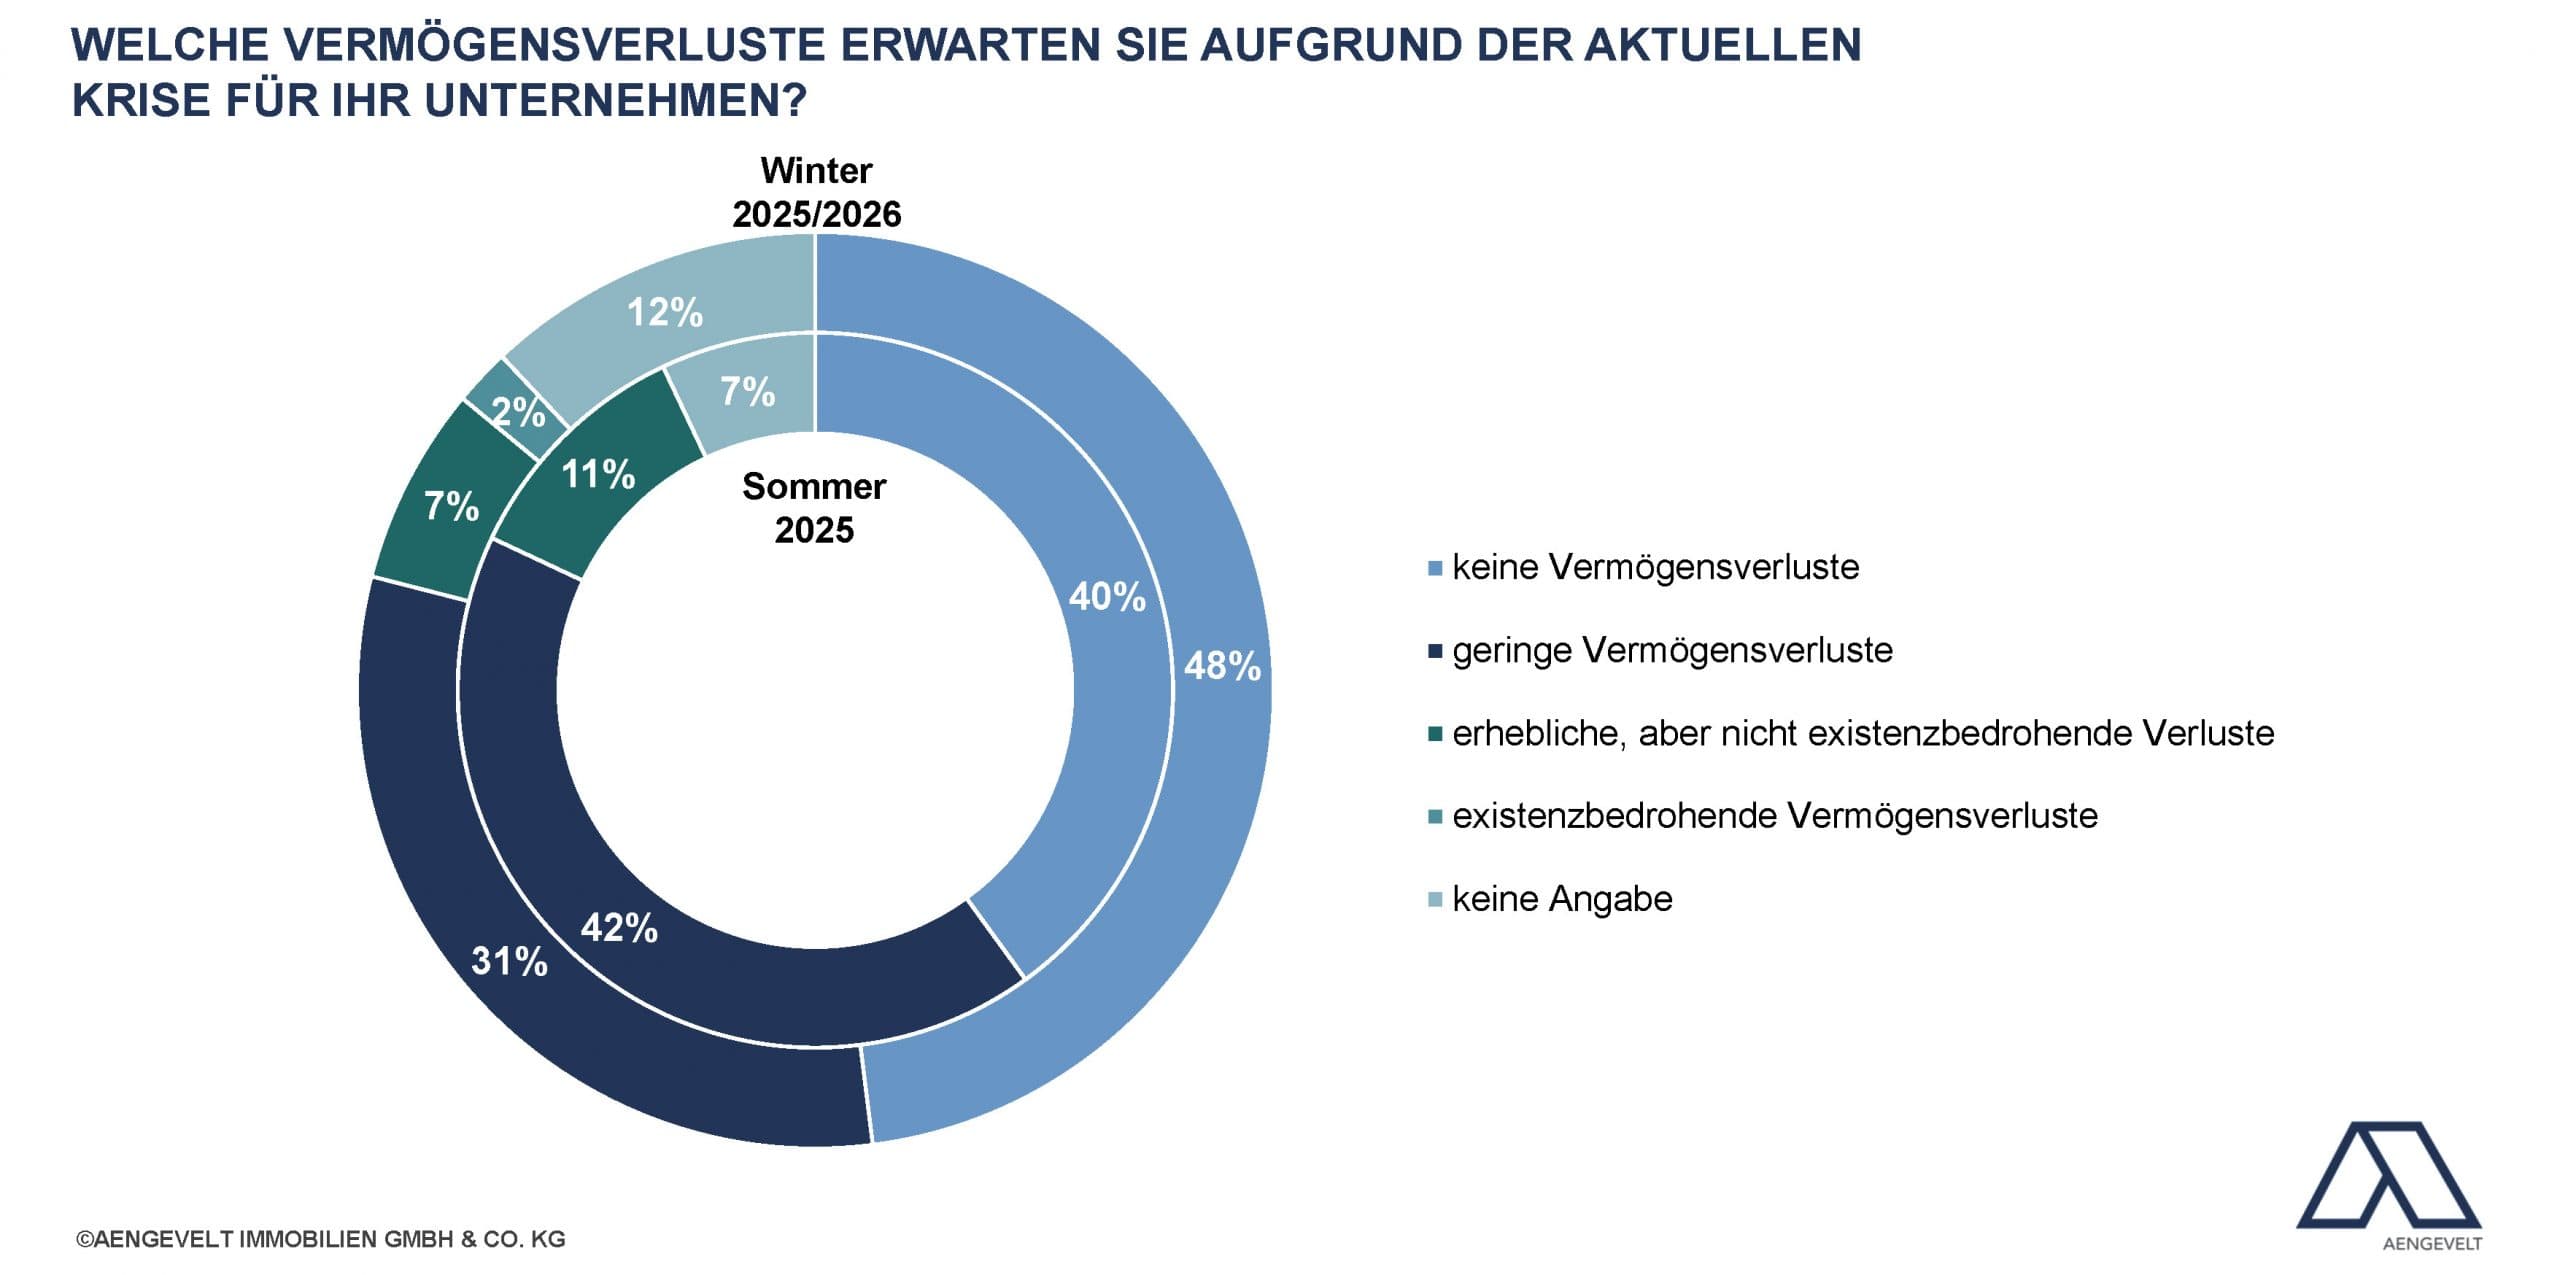
After the survey was launched in winter 2022/2023, the survey was asked for the sixth time what asset losses the survey participants expect for their company. Results of the winter survey 2025/2026:
Die aktuelle Befragung zeigt, dass die Krise für die Wohnungswirtschaft noch nicht überwunden ist, sondern die Sorgen zumindest teilweise sogar wieder zunehmen. Überraschend ist dabei, dass einerseits erschwerte Geschäftsbedingungen erwartet werden und dennoch die Befürchtungen hinsichtlich Vermögensverlusten sinken.
Dazu Magdalena Kolak, Senior Analystin Aengevelt Research: „Die aktuellen Umfrageergebnisse zeigen, dass ungeachtet moderat steigender Baugenehmigungen nach wie vor Verunsicherung herrscht und zukünftige Marktentwicklungen kaum zuverlässig abzuschätzen sind. Bestätigt wird das durch rückläufige Transaktionsvolumina am deutschen Wohninvestmentmarkt im letzten Jahr. Das liegt nicht zuletzt an den vielfältigen Verknüpfungen und Abhängigkeiten innerhalb der Wohnungswirtschaft. Dazu zählen z.B. rechtliche Rahmenbedingungen, die Bereitschaft von Banken zur Finanzierung von Wohnbauprojekten und die damit verbundenen Zinskonditionen, die Platzierbarkeit von Wohnungsprodukten bei Nutzern und Investoren, erzielbare Verkaufspreise in Korrelation zu den Baukosten etc. Und auch die Wohnungspolitik der Bundesregierung setzt bislang noch zu wenig Impulse für den längst überfälligen nachhaltigen Wachstumsschub im Wohnungsneubau. Kurz: Es fehlt (noch) an Planungssicherheit in Kombination mit Anreizen für Investoren und Bestandshalter, um die Dynamik gerade auch im wohnwirtschaftlichen Bereich nachhaltig zu steigern.“