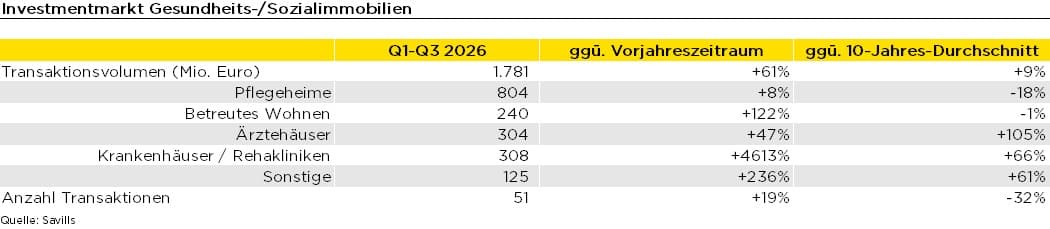


According to Savills, the transaction volume for healthcare and social care properties in the first three quarters of 2026 totalled almost 1.8 billion euros. This means that the current year will see by far the highest transaction volume since 2022. A major factor in this was Aedifica’s acquisition of a majority stake in Cofinimmo, as well as TPG Real Estate’s acquisition of a portfolio of medical centres from Northwest Healthcare Properties in the first quarter; together, these accounted for just over half of the transaction volume.
The prime yield for care homes rose by 10 basis points in the third quarter for the second consecutive quarter, reaching 5.4 per cent. The prime yield for medical centres also rose by 10 basis points to 4.8 per cent, whilst the prime yield for sheltered housing increased by 20 basis points to 4.7 per cent.
Max Eiting, Director and Head of Healthcare Capital Markets at Savills in Germany, comments on market developments as follows: “In the third quarter, the investment market for healthcare and social care properties saw predominantly smaller transactions, and overall slightly fewer deals were completed. Nevertheless, we are observing a high level of market activity, particularly on the owner side, and expect supply to grow in the coming quarters. One reason for this is that more funds are reaching the end of their planned terms. Whilst investors from Germany continue to adopt a predominantly selective approach, foreign investors are currently showing a much greater appetite for purchases, particularly in the care home segment. It is striking that, in many successful care home transactions, a change of operator was part of the investment strategy. This is being facilitated by the return of some operators to a growth trajectory, as well as the ongoing consolidation of the operator market, which is creating opportunities for certain portfolios. Against the backdrop of rising interest rates, prime yields increased across all property types in the third quarter. Core transactions, however, remain rare, and across the market as a whole, the price-to-earnings ratio generally ranges from 14 to 15 times.”
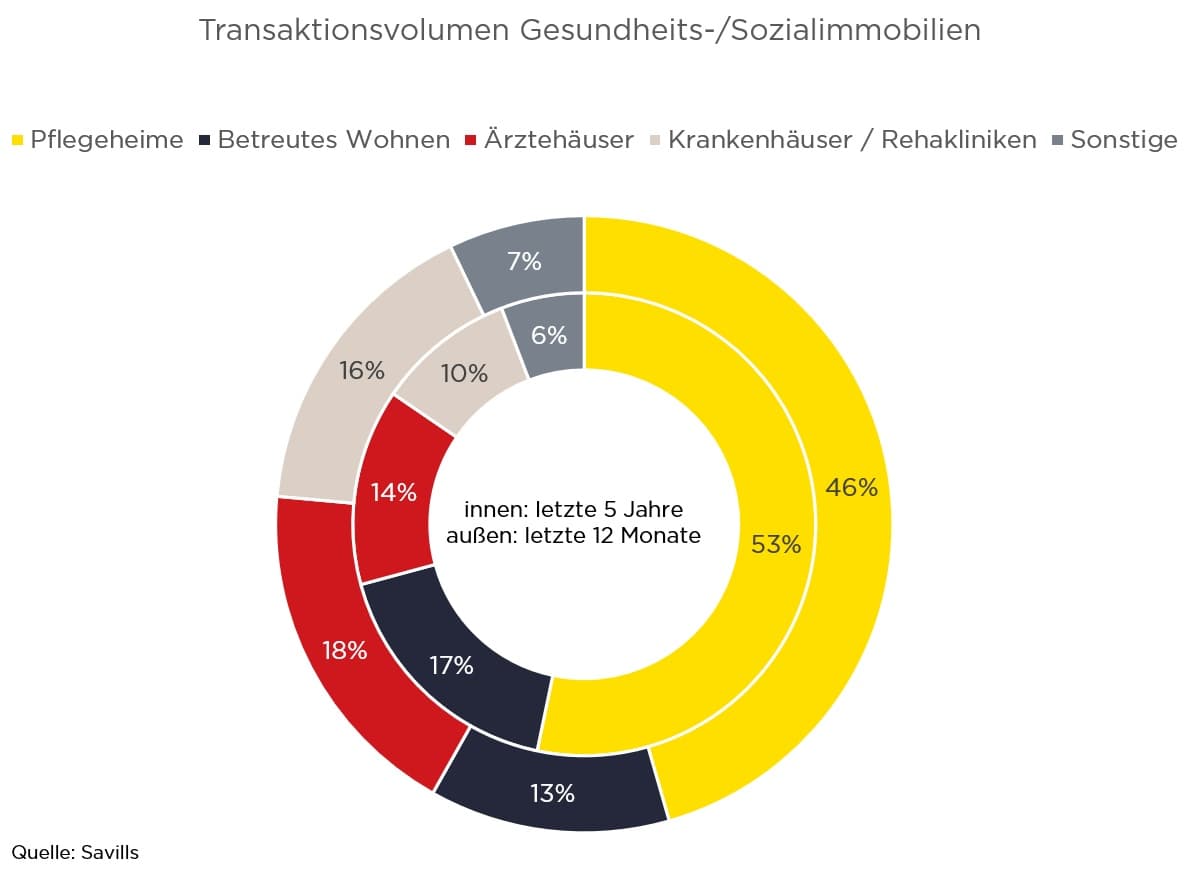
In terms of transaction volume, care homes dominated the market from January to September, partly due to Cofinimmo’s acquisition of a majority stake. These accounted for €804 million, or 45 per cent of the total volume. These were followed by medical centres, with a volume of €304 million (17 per cent of the total volume). Hospitals and rehabilitation clinics together accounted for €308 million, or 17 per cent of the total volume – this high figure can be explained, amongst other things, by rehabilitation clinics that were traded as part of the Cofinimmo acquisition and by conversion projects involving hospitals. Assisted living accounted for €240 million, or 13 per cent of the volume.
In terms of the number of transactions, however, medical centres came top, whilst care homes took second place.