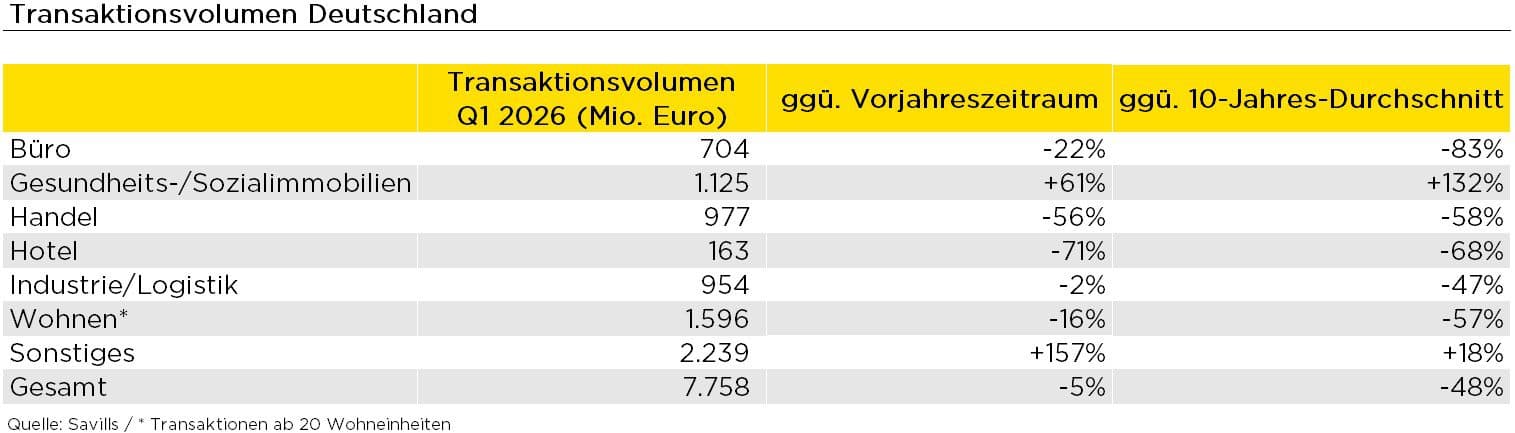


In an environment that continues to be characterised by high uncertainty and volatility, activity on the German investment market for commercial and residential real estate* remained subdued at the beginning of 2026. In the 1st quarter, properties worth approx. 7.8 billion euros changed hands. Compared to the same quarter of the previous year, this corresponds to a decrease of 5%. This volume is spread over around 270 transactions, the number of which was slightly higher than in the same quarter of the previous year. Karsten Nemecek, Deputy CEO Germany and responsible for Capital Markets, comments on the market as follows: "The long list of crises of recent years, in which the Iran war and its economic upheavals are now being added, are putting the real estate investment market under considerable stress. In the short term, the conflict could slow down the transaction dynamic, because some investors will probably wait for further developments. At the same time, the renewed rise in interest rates and the weaker economic outlook are increasing the pressure to act for those owners who had hoped for more favourable sales conditions. In the medium term, the recent crisis could therefore cause the number of sales to rise considerably."
Prime yields still stable, but with upward pressure
In the wake of the Iran war, long-term interest rates and bond yields have risen significantly and have reached long-term highs. If this level becomes entrenched, it is also likely to be reflected in real estate prices. According to Savills experts, prime yields remained unchanged in the 1st quarter for all but one use: the prime yield for logistics properties rose by 10 basis points to 4.5%.
Non-profit-driven purchases are on the rise
"The environment for the real estate asset class remains difficult. This is also reflected in the buyer structure: many purchases are not profit-driven, but are made by the public sector or owner-occupiers. At the same time, the proportion of private investors remains high," says Matthias Pink, Head of Research Germany at Savills. An example of this is the largest single property sale in the 1st quarter: The construction and real estate company of the state of North Rhine-Westphalia acquired the new building of the state tax administration in Kaarst from Landmarken AG for a mid-three-digit million amount. Overall, 14% of the purchase volume was accounted for by the public sector. In addition, 8% are attributable to 'other non-real estate companies', most of which are owner-occupiers. "Around one in five real estate purchases is currently not a capital investment," says Pink. Nevertheless, asset/investment managers remained the largest group of buyers, with a volume share of 33% in Q1. In addition to the public sector, project developers also achieved a double-digit share (11%).