

Transaction volume after three quarters just below the previous year’s figure
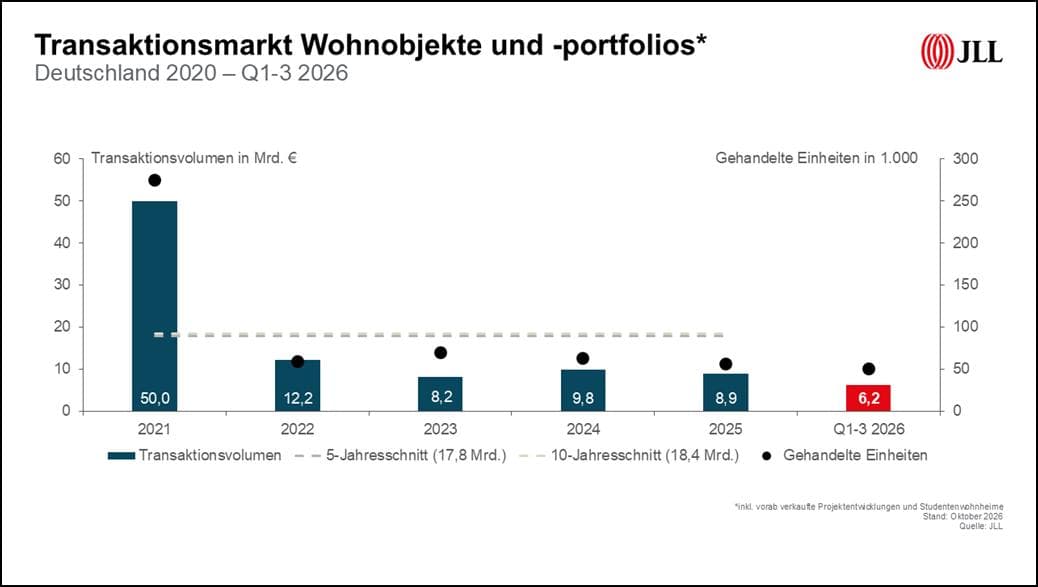
The commercial residential investment market in Germany is holding its own at a stable level in a market environment characterised by geopolitical tensions, rising financing costs and high uncertainty. Following a transaction volume* of around 1.9 billion euros in the third quarter (previous year: 2.02 billion euros), the total for the first three quarters of 2026 stands at around 6.2 billion euros, which is only slightly below the previous year’s figure of 6.4 billion euros.
With 53 recorded transactions, market activity in the third quarter was lower than in the corresponding period of the previous year, which saw 65 deals. A total of around 50,000 units were traded (previous year: 41,600). The average deal size rose to 36 million euros, compared with 31 million euros in the same quarter of the previous year.
According to Michael Bender, Head of Residential at JLL Germany, the market is thus continuing to demonstrate a high degree of resilience. “The operating environment is challenging, yet the volume of investment remains close to last year’s figure. Whilst the market is operating at a lower level than in previous years, it is still at a level that reliably generates transactions. Demand remains strong, particularly in the core and core-plus segments,” comments Bender.
Large-scale transactions continue to form a key pillar of market activity. In the first three quarters, eleven deals in the three-digit million range were recorded, which together accounted for around 2.2 billion euros, or 35.1 per cent of the total investment volume (previous year: 36.8 per cent). Inter-regional portfolio transactions also maintained their significance, accounting for a market share of 38.7 per cent (previous year: 40.4 per cent) or around 2.4 billion euros.