Between 2019 and 2026, the share of studios offered for rent rather than for sale fell from 47% to 8%, according to the Bien’ici portal: small areas are deserting the rental market at the same time as student demand is reaching record highs. As of January 1, 2026, more than 180,000 requests for accommodation in university residences remained unanswered, and the tension is no longer limited to large cities, it is spreading to medium-sized university cities. Faced with this demand, Valorissimo, a B2B marketplace that connects real estate developers and specifiers, notes a paradox: individual investors are present, but the offer of investment products has become scarce, pushing the prescription towards the main residence. With Bouygues Immobilier’s My Campus / My Work programmes, deployed in some fifteen conurbations from Angers to Avignon and from Niort to Clermont-Ferrand, the platform intends to give advisors a product that is clear, financeable and meets immediate rental demand.
The movement described by Bien’ici reflects first of all the arbitrations of established landlords, who sell old lots rather than rent them out. It says nothing about a lack of interest on the part of new entrants: rental demand has never been so tense. According to the study published at the end of August by PAP, the student rental supply increased by 4% over one year. In Paris, an 18 m² studio can attract more than 1,600 contacts in less than a week, and more than seven out of ten students describe their search for accommodation as a source of anxiety. The waiting list of the Crous network exceeded 180,000 unmet requests on 1 January.
“Demand from individual investors has never disappeared: they are looking for controlled tickets, legible locations and quick rentals. What has changed is the supply. The end of the Pinel, two successive reforms of the furnished accommodation sector and a still new Jeanbrun scheme have made the sourcing of the investment product much more demanding. Our partners have not deserted this market: they were waiting for products to commit to. »
Emma Leca – Managing Director of Valorissimo
But tension is no longer the prerogative of large cities. Rennes, Grenoble, Angers and Montpellier, long considered to be valves, are seeing their rental stock decline in relation to the growth of their training offer. Angers, voted “students’ favourite city” by L’Étudiant, welcomes 46,000 students and has gained an average of 1,000 each year for the past ten years. Clermont-Ferrand has more than 40,000 students.
The volumes processed by the platform reflect this post-Pinel recomposition: non-professional furnished rentals now account for 41% of bookings (23% unmanaged and 18% managed) while the new Jeanbrun scheme, which came into force in February 2026, already accounts for 6%.
My Campus / My Work: a network of medium-sized university towns
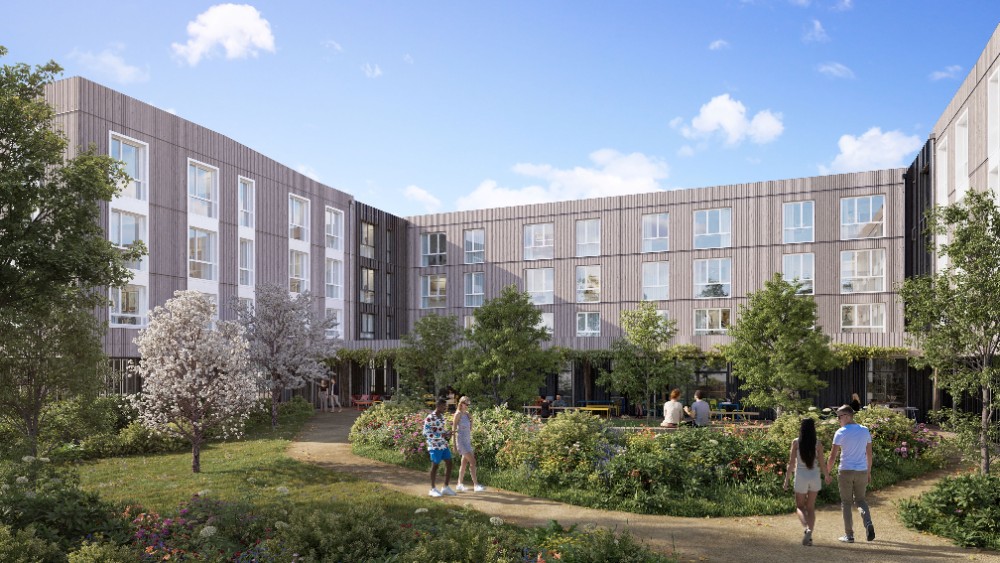
Developed by Bouygues Immobilier and distributed exclusively on B2B on Valorissimo, the My Campus / My Work residences are designed for students and young professionals: functional studios, T1 and T2, delivered ready to rent with kitchenette, fitted bathroom and storage, complete with secure common areas (cafeteria, study or coworking room, laundry, bicycle room) and a manager present on site.
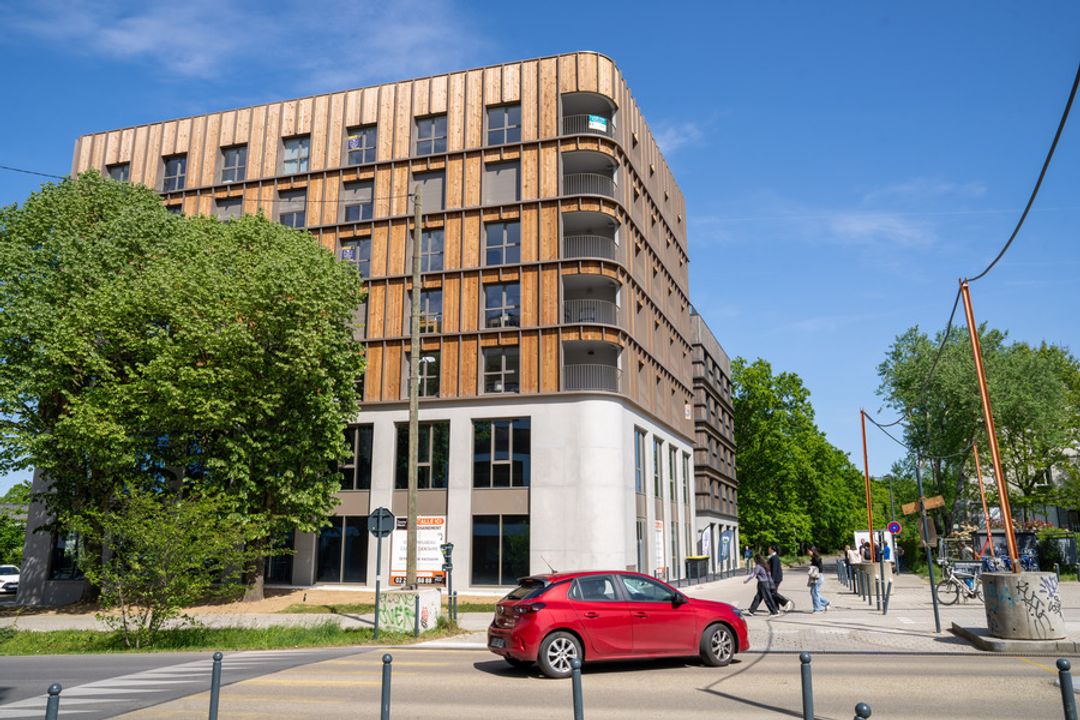
The geography of the concept is precisely that of the new tension. Born in Rennes, where it has several residences, the brand has expanded into medium-sized university towns: Angers/Trélazé, Niort, Vannes, Lorient, Tours, Saint-Jean-de-Braye, Metz, Évreux, Dreux, Clermont-Ferrand, Avignon, as well as Échirolles and Gières in the Grenoble conurbation, in direct contact with the university sector. The latest residence delivered, My Campus Metz Technopôle, opened in the summer of 2026, just before the start of the school year. In other words, about fifteen cities where the training offer has expanded faster than the private rental stock.
The concept has three characteristics that distinguish it from traditional service residences:
0 1
An accessible entrance ticket. At My Campus Anjou (Trélazé, Angers agglomeration), the 20 m² studios range from around €120k in 20% VAT, or €100k in the event of VAT recovery, for a furnished rent of around €425 excluding charges.
0 2
An unmanaged residence. The investor is not bound to a single operator by a nine-year commercial lease: he retains control of his property, its rental and its exit. Rental management and concierge services can be entrusted to the residence’s partners (Foncia, Citya) without this choice being imposed.
0 3
A furnished rental with services. Reception, linen supply and cleaning allow, under certain conditions, to opt for VAT recovery and to charge rents higher than those of an equivalent bare rental.
“Our job is to absorb this sourcing and qualification work upstream, so that our partners find the same level of information and security for rental investment as for the main residence. The student residence is the best way to demonstrate this: rental demand is documented, the product is standardised, the ticket is financeable, and the network of cities makes it possible to offer a credible alternative to a client who cannot find anything within his budget in mainland France. »
Emma Leca – Managing Director of Valorissimo
The Valorissimo platform, which brings together more than 10,000 partner prescribers and has generated nearly 30,000 reservations in ten years, relies on a team of facilitators present in all regions, a simulator integrated into the lot catalogue and a conversational assistant dedicated to prescribers. According to the AFII, 58% of retail investors have used a prescriber for their last real estate purchase, compared to 35% in 2019.