The Düsseldorf investment market has achieved a volume of €963 million up to Q3 2026 – the best result since the interest rate turnaround in 2022. Q2 was driven by major deals (including the Dreischeibenhaus at over €200 million), whilst Q3 fell to €214 million. Office property dominated (46 per cent), with prime yields up 10 basis points.
The Düsseldorf office market recorded around 200,000 m² of take-up, 8 per cent above the five-year average and just under 28 per cent higher than the previous year; Q3 fuelled this momentum. Uniper leased approximately 37,000 m²; the average rent rose to €24/m², with prime rents at €46/m². By the end of the year: 250,000–300,000 m² is a realistic figure.
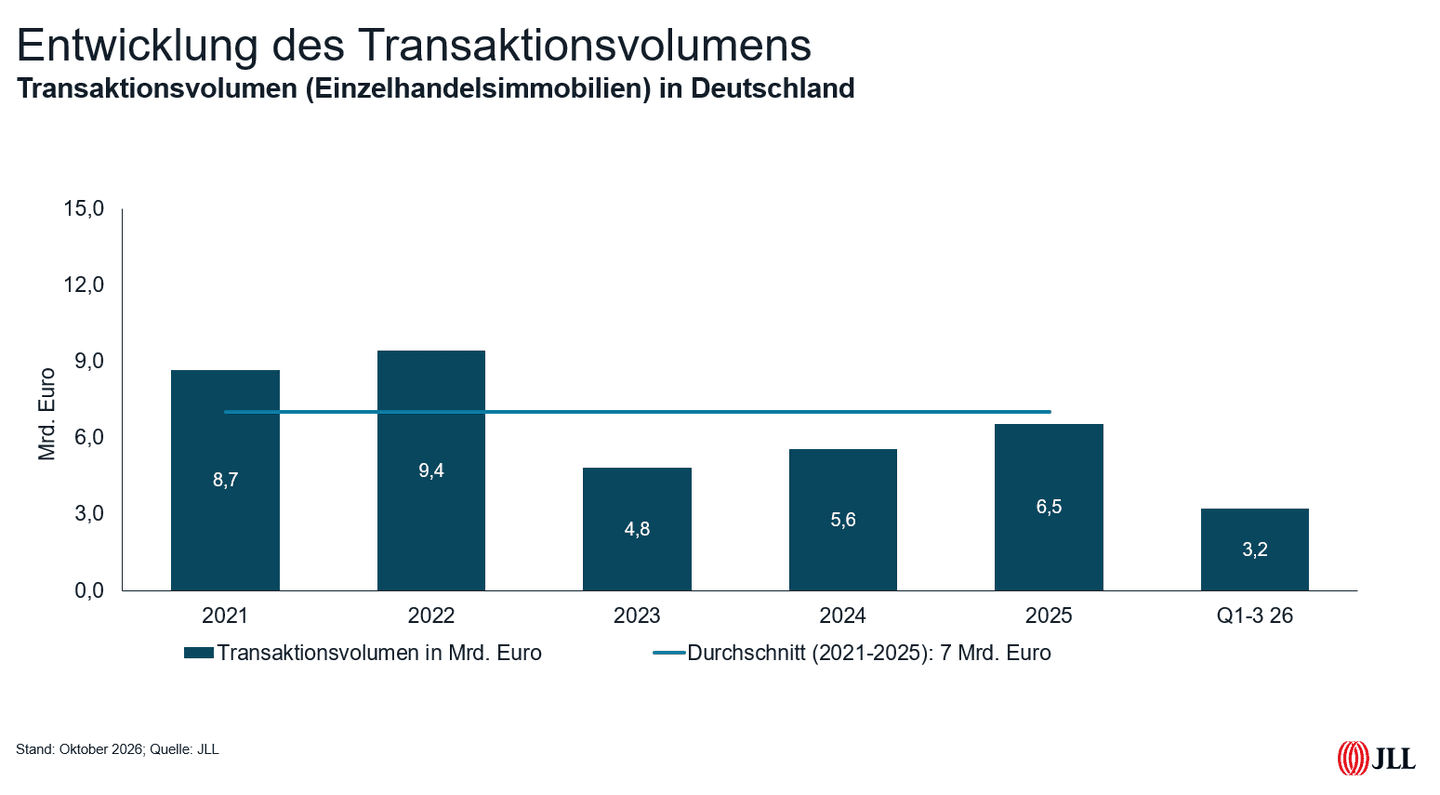
After nine months of 2026, the German retail property market has recorded a total of around €3.2 billion across 169 transactions. Q3 accounted for just under €900 million. JLL expects a total of €6–6.5 billion for 2026 and anticipates a broader distribution of deals as well as growing investor interest.
By the end of Q3 2026, the Berlin investment market will have raised around €1 billion, trailing behind Munich (€1.7 billion) and Hamburg (€1.2 billion). There is a lack of major deals (only one worth over €100 million and one worth over €50 million); the picture is characterised by many smaller transactions, with prime yields rising by 10 basis points.
The ‘Germany City Centre Study 2026/27’ confirms that restaurants and cafés are key strengths and attractions in city centres, scoring top marks and enjoying stable demand. The DZG is calling for better framework conditions to support this: flexible employment, less red tape and planning certainty.
A global Clearwater study of 250 senior executives at asset management firms reveals a sharp rise in risks: market, credit, liquidity and concentration risks are on the increase. The biggest concern for the next 12 months is technology/cyber risk. Reputational, ESG and competitive risks are also rising.
Rohrer Immobilien continues to view Munich as a stable property market. In the residential sector, value-add properties and conversions are in demand; in the commercial sector, the wheat is being separated from the chaff, with adjusted prices opening up opportunities. Quality, location and ESG compliance remain crucial.
The DAVE Market Report 2026/2027 shows that the German property investment market is recovering, with transaction volumes rising in many cities and across many asset classes. Residential property acts as an anchor of stability; in the office sector, quality is key. Austria is still lagging behind in the recovery.
BNP Paribas Real Estate reports a hotel transaction volume of around €1 billion (–27 per cent) for Q1–3 2026, whilst the number of deals rose by 27 per cent – the highest since Q1–3 2022. Foreign investors accounted for approximately 48 per cent (≈€500 million). A total volume of around €1.5 billion is expected for 2026.
The German hotel investment market recorded a transaction volume of €1.01 billion (−33 per cent) in Q1–Q3 2026. Smaller transactions dominated, with value-add deals accounting for around 49 per cent. The prime yield stood at 5.25 per cent; stable demand (223.8 million overnight stays) is underpinning the market.
At EXPO REAL 2026, industry representatives paint a realistic picture: financing remains challenging, transactions are stalling, and the focus is shifting to the existing property portfolio. At the same time, many report constructive discussions and opportunities relating to energy, digitalisation and infrastructure.


 Analysis
 Article
 Comment
 Discussion
 Forecast
 Infographic
 Interview
 Monthly
 News
 Podcast
 Quarterly
 Report
 Survey
 Video
 Weekly
 Whitepaper