Quarterly

All content in this category

RICS: Sentiment in the construction sector is weakening across all regions, and the outlook for credit conditions is also deteriorating / Germany ranks second amongst the European markets surveyed
AnalysisQuarterlyReportSurvey

RICS: Sentiment in the construction sector is weakening across all regions, and the outlook for credit conditions is also deteriorating / Germany ranks second amongst the European markets surveyed

The RICS Global Construction Monitor Q3/2026 reports a slowdown in construction activity across all regions of the world; the CSI has fallen to +4 globally. Lending conditions are deteriorating. In Europe, France is the main drag, whilst Germany ranks second across Europe.

AnalysisQuarterlyReport

RICS: Global investment demand is losing momentum amid tighter financing conditions

The RICS Global Commercial Property Monitor Q3/2026 reports weaker sentiment worldwide: the CPSI has fallen to -4, driven by the investment side. Lending conditions have slipped into negative territory globally. Germany is at the bottom of the table with a CPSI of -26 and lending conditions at -71 per cent; the majority foresee a downturn.

LIP Invest publishes its “Logistics Property in Germany” market report for Q3 2026
AnalysisQuarterlyReport

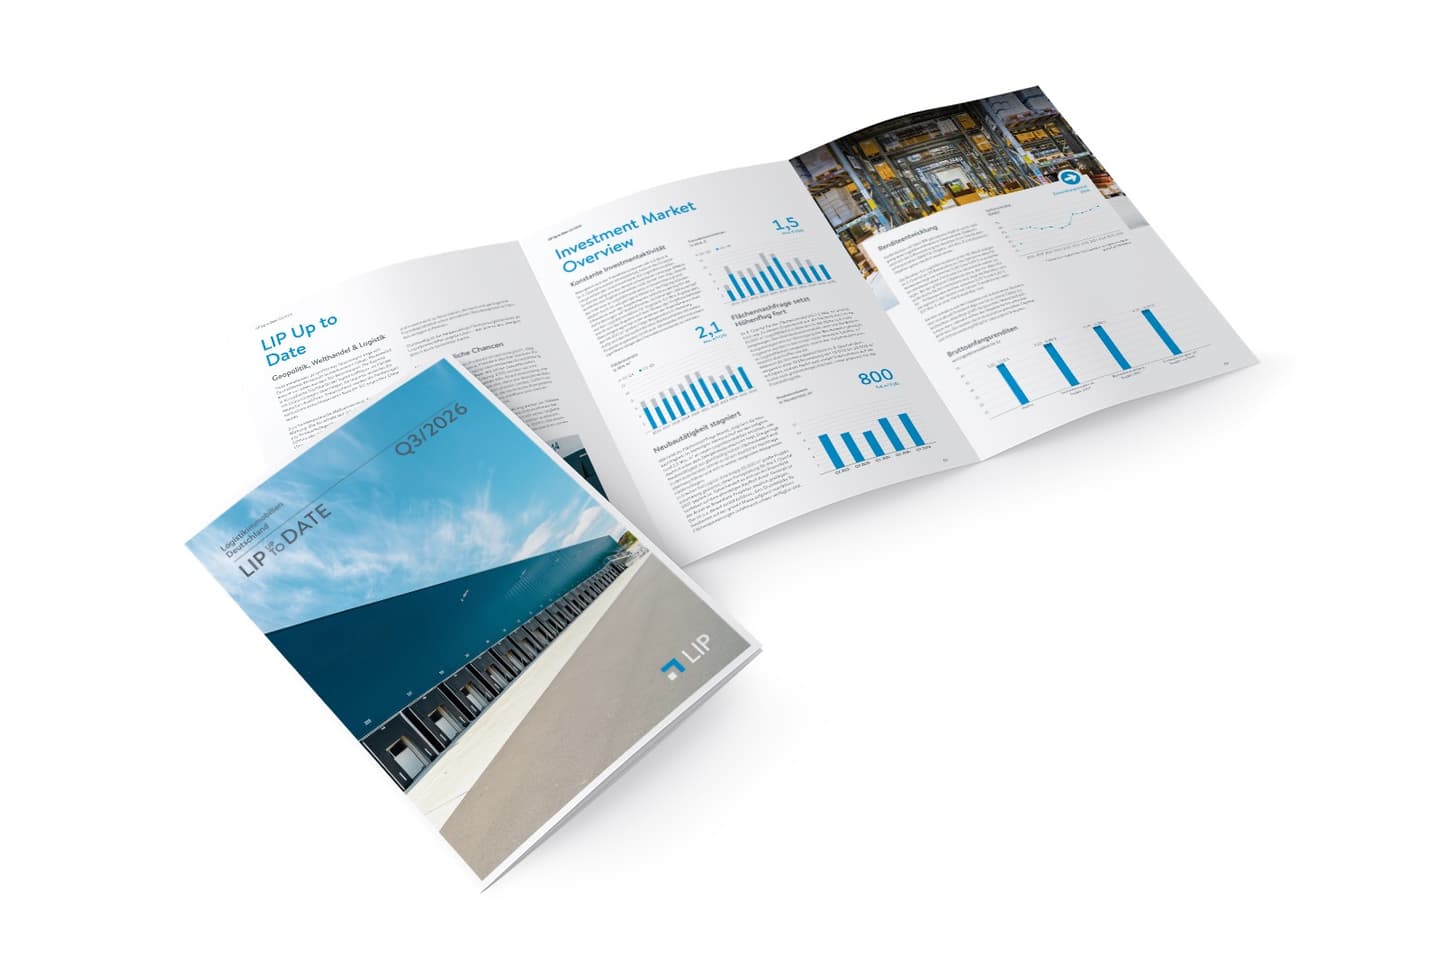
LIP Invest publishes its “Logistics Property in Germany” market report for Q3 2026

LIP Invest has published the market report “Logistics Property in Germany” for Q3 2026. Yields continue to diverge; +20 basis points for smaller properties, 5.70–6.20 per cent for large assets. Investment volume in Q3: €1.5 billion; strong take-up, weak new-build activity.

Europe’s property markets are performing unevenly – Germany is investing selectively
AnalysisCommentQuarterlyReport

Europe’s property markets are performing unevenly – Germany is investing selectively

Colliers reports mixed performance across Europe’s property markets in 2026: Spain, Poland and Ireland are seeing significant growth, whilst Germany remains cautious due to difficulties with pricing and financing. Data centres, residential and logistics properties are in demand. A gradual recovery is expected from 2027 onwards.

NAI apollo: The logistics property market in the Rhine-Main region continues to recover despite challenging conditions
AnalysisQuarterlyReport

NAI apollo: The logistics property market in the Rhine-Main region continues to recover despite challenging conditions

In the Rhine-Main logistics market, space take-up rose to 167,400 m² in Q3; after nine months of 2026, 393,400 m² had been achieved. Existing properties dominate, with new-builds accounting for 13.7 per cent; large-scale spaces (>10,000 m²) are driving growth. Transport, warehousing and logistics companies account for around 60 per cent, whilst rents of up to €9.00 per m² are rising.

AnalysisQuarterlyReport

JLL: Logistics market boosts letting volume by 1 million m²

The German logistics market saw take-up rise by 23 per cent to around 5.36 million m² in Q1–Q3 2026. The growth is being driven by companies in the transport, logistics and warehousing sectors; take-up of 7 million m² is possible by the end of the year. Outside the major cities, the market is growing more strongly, with prime rents on the rise.

AnalysisQuarterlyReport

Retail market records its strongest quarter to date in terms of space take-up

BNP Paribas Real Estate reports an inner-city retail space take-up of around 385,000 m² for Q1–3 2026, of which 150,000 m² was recorded in the strong Q3 (40 per cent). 57 per cent of this was accounted for by lettings exceeding 1,000 m²; shopping centres (≈110,000 m²), former department stores (≈50,000 m²) and tier-one cities are driving this momentum.
AnalysisQuarterlyReport

Leipzig’s logistics property market shows the first signs of recovery

The Leipzig logistics property market is showing the first signs of recovery: in the first nine months of 2026, approximately 180,400 m² were let, just 2 per cent below the previous year’s figure. A high supply of space is holding back rents (peak €5.90/m², average €5.50), whilst there were no transactions on the investment market. Stronger rental growth is expected from 2027 onwards.

AnalysisQuarterlyReport

Stuttgart’s logistics property market sees a 142 per cent increase in take-up

The Stuttgart logistics property market grew strongly in the first nine months of 2026: space take-up rose to around 168,200 m², up 142 per cent on the previous year, driven by small and medium-sized lettings. Prime rents climbed to €8.90 per m², whilst the average rent stood at €7.90 per m²; the investment volume fell by 40 per cent to €116 million.

AnalysisQuarterlyReport

Cologne’s logistics property market sees an exceptionally strong rise in turnover

The Cologne logistics property market grew strongly in the first nine months of 2026: take-up rose to around 292,000 m², more than doubling. High demand from international logistics companies drove up rents; the investment volume climbed by 133 per cent to €145 million. Prime rent: €8.40/m²; average: €6.80.

AnalysisQuarterlyReport

Supply of space in Berlin’s logistics market is growing

Newly built space and expiring leases are increasing supply in Berlin’s logistics lettings market. Demand is recovering but remains below the levels seen during the boom years; large-scale deals are less common. Space is scarce in the city centre, whilst vacancy rates are higher in the surrounding areas; there are few deals in the investment market.

AnalysisQuarterlyReport

Asian users drive Düsseldorf’s logistics market to a record high

Asian tenants are driving demand for large logistics spaces in Düsseldorf; after nine months, space turnover has reached a record high. A low number of new builds is boosting pre-let rates and could fuel further rises in prime rents; the light industrial sector is struggling.

#Newsletter: Stay up to date!

Sign up for our newsletter and receive regular updates on the latest topics.

Register now