

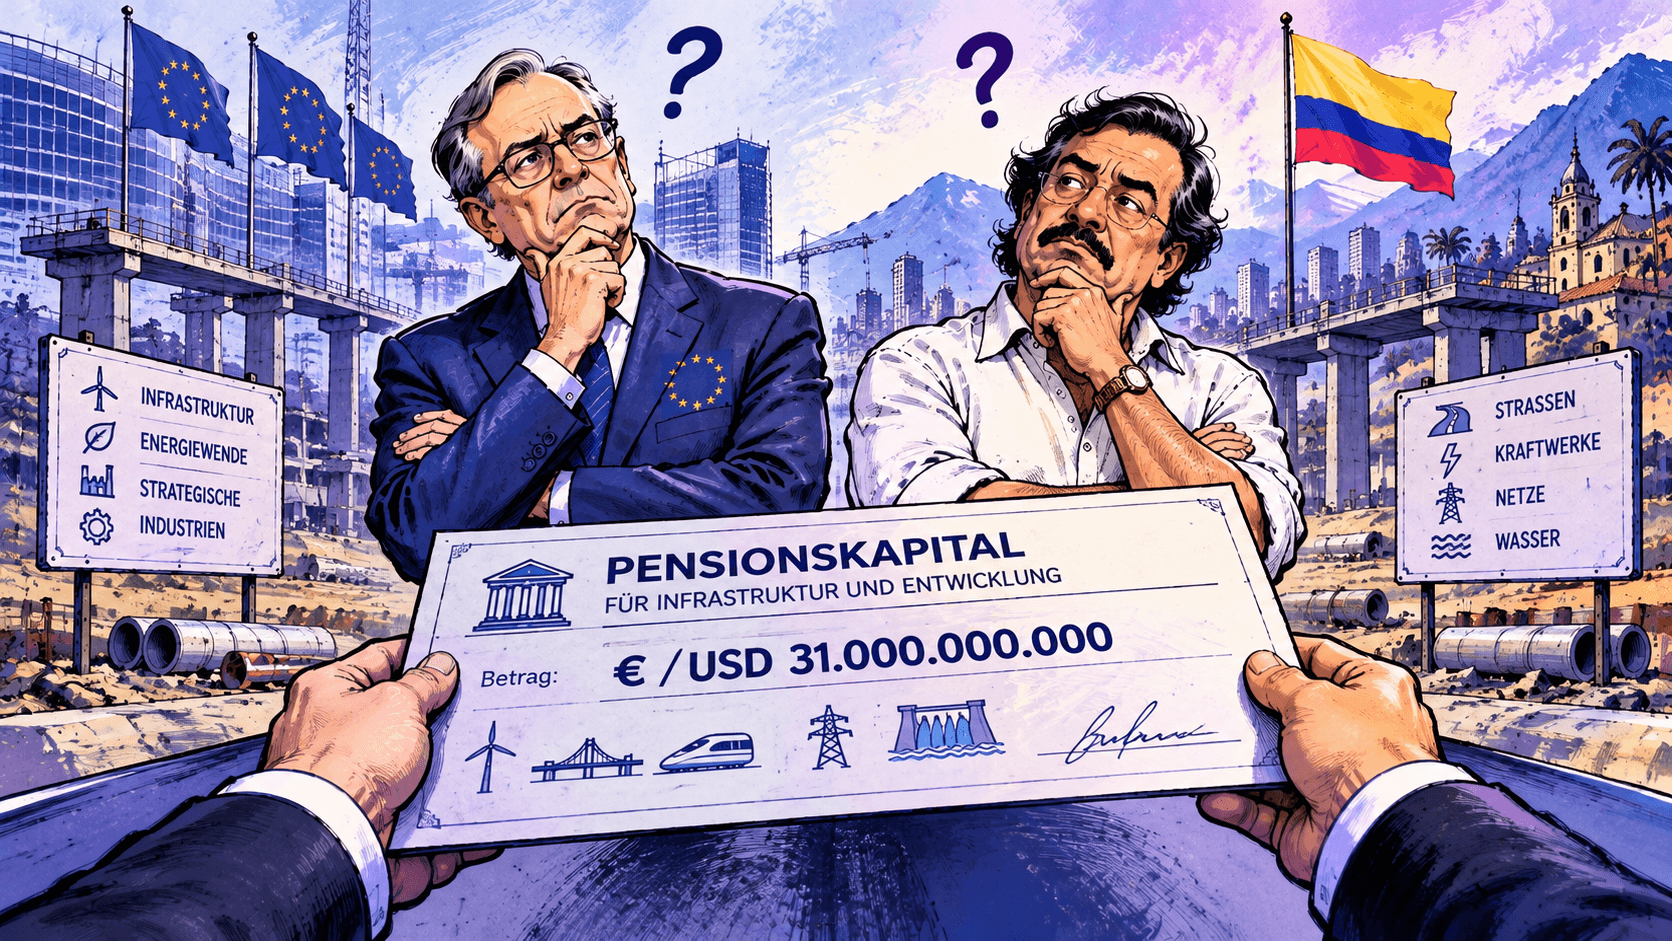
Colombia wanted to channel pension assets into the country by decree. Europe relies on market incentives. Yet both approaches raise the same question: will this generate new investment – or will it simply make existing assets more expensive?
It is a tempting idea: the government needs billions for infrastructure, the energy transition and economic development. At the same time, pension funds manage vast amounts of capital. So why not combine the two?
In Colombia, that was precisely the aim. Colombia’s private pension funds manage around 179 billion US dollars on behalf of just under 20 million policyholders. In April, the government of the time decided to cap foreign investments at a maximum of 30 per cent of the funds’ assets. Until then, this figure had stood at around 48 per cent. The aim was for the equivalent of 31 billion US dollars to be gradually channelled back into the domestic capital market. On 7 October, the new government repealed the regulation. Concerns regarding investment risks and potential price distortions were simply too great.
This story also deserves attention on this side of the Atlantic.
For with its Savings and Investments Union, the European Union is also pursuing the aim of mobilising private savings more effectively for productive investment. There is, however, one crucial difference: whilst Colombia relied on interventionist capital controls, Europe aims to achieve this primarily through integrated capital markets, better investment conditions and the removal of regulatory barriers. This is, admittedly, the far more convincing approach from a market economy perspective.
Yet both models raise the same fundamental economic question: does the mobilisation of additional capital also create additional investment opportunities?
When billions are channelled into a limited number of viable infrastructure projects, this does not automatically result in new electricity grids, bridges or power stations. Initially, the additional capital may simply be competing for the same assets. Prices rise and returns fall. This does not, in itself, create new real investment.
Of course, additional capital can make new projects possible. But for that to happen, these projects must be eligible for approval, economically viable and actually feasible. Money alone does not remove regulatory barriers or resolve the lack of grid connections.
At present, it is clear that stakeholders need to give at least as much thought to the sequence of economic policy measures. The mobilisation of capital and the creation of investable projects must go hand in hand. Where the latter are lacking, there is a risk that the mobilisation of capital will merely drive up the cost of existing assets.