Real Estate

Real estate is the dominant asset class in the real assets sector, but also the most versatile.

Real Estate analysiss

Analysis Quarterly Report

Residential is the strongest asset class in the first half of 2026

BNP Paribas Real Estate reports a residential investment volume of €4.4 billion for H1 2026, driven by more mid-sized deals; Major deals over €100 million account for 34%. Existing portfolios account for 47%, A-cities for 38%. Net prime yields rise by 5-10 basis points.

Balkendiagramm zu Spitzenrenditen im zweiten Quartal 2026 nach Immobilienkategorien: Büro, Geschäftshaus, Fachmarktzentrum, Shopping-Center, Logistik, Mehrfamilienhaus und risikofreier Zins.
Analysis Quarterly Report

Savills examines real estate investment market in Germany: Transaction volume stable, liquidity remains limited

Savills reports a transaction volume of around EUR 14.7 billion for H1 2026 – stable compared to the previous year, with continued limited liquidity and weaker Q2. Healthcare/social real estate is above the 10-year average. Savills expects a transaction volume of around 35 billion euros in 2026.

Deutscher Investmentmarkt in der ersten Jahreshälfte mit leichtem Umsatzplus
Analysis Quarterly Report

German investment market with slight increase in turnover in the first half of the year

BNP Paribas Real Estate reports an investment volume of €16.6 billion (+5%) for H1 2026. Residential remains the strongest asset class at €4.4 billion, commercial €12.3 billion (+8%); office (€3.2 billion). Munich is in the lead (€1.2 billion). Net prime yields rose industry-wide in Q2.

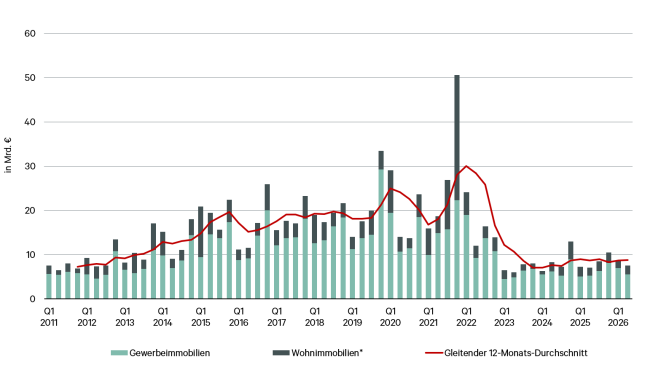
Balkendiagramm und Liniengrafik zum Investmenttransaktionsvolumen in Deutschland für Gewerbe- und Wohnimmobilien, Zeitraum 2016-2026, basierend auf CBRE Research.
Analysis Quarterly Report

Real estate investment market grew in the first half of the year

CBRE reports an investment transaction volume of EUR 16.2 billion (+13%) for H1 2026. Office growth significantly, logistics/industry stimulated the market, the top 7 locations gained in importance; pricing is well advanced, with around 35 billion euros expected for 2026.

Belebung auf dem Wohninvestmentmarkt trifft auf selektive Investorenstrategien
Analysis

Revival in the residential investment market meets selective investor strategies

The German residential investment market is stabilizing: H1 2026 with EUR 3.6 billion (−10% YoY), Q2 increased by 17% compared to Q1. 97 transactions (+8% YoY, +76% vs. H1 2023). Investors focus on cash flow and affordable housing; H2 is likely to become busier.

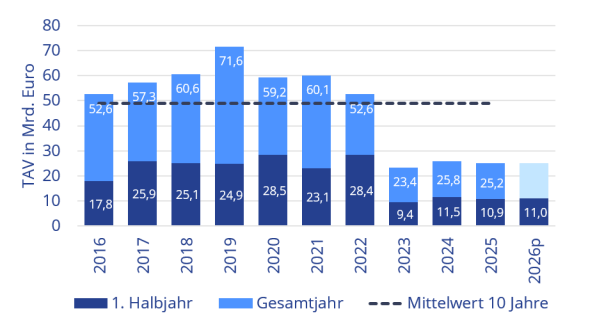
Balkendiagramm zum gewerblichen Transaktionsvolumen in Deutschland von 2016 bis 2026 mit Angaben zum ersten Halbjahr, Gesamtjahr und dem 10-Jahres-Mittelwert.
Analysis Quarterly Report

Four forward, one back – moderate market recovery takes a break

Colliers reports a transaction volume of 15.1 billion euros for H1 2026, almost at the previous year's level. In Q2, the market cooled due to the Iran conflict and stricter financing; Yields are rising. Around 25 billion euros are expected for 2026 and opportunities for active buyers.

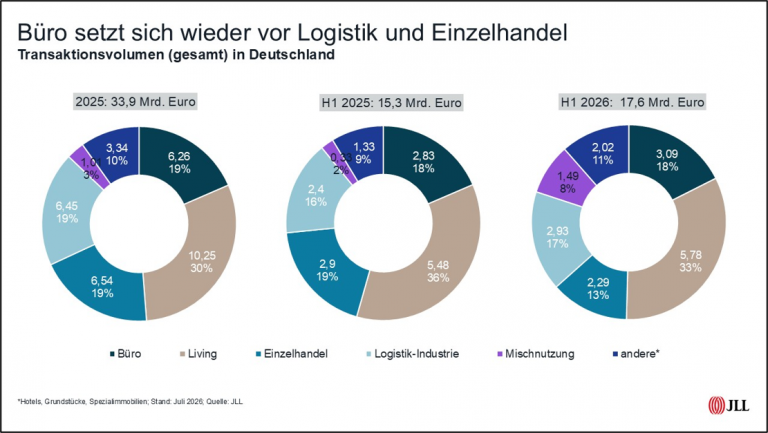
Drei Tortendiagramme zeigen das Transaktionsvolumen nach Immobiliensektoren in Deutschland 2025 und H1 2026: Büro, Living, Einzelhandel, Logistik-Industrie, Mischnutzung und andere.
Analysis Quarterly Report

JLL: The German investment market confirms its moderate upward trend

The real estate investment market in Germany is continuing its moderate upward trend: at the end of the first half of 2026, around EUR 17.6 billion was turnover, around 15 percent more than in the previous year. Individual deals increased, portfolios remained weak; Foreign investors accounted for 44 percent, and prime office yields rose.

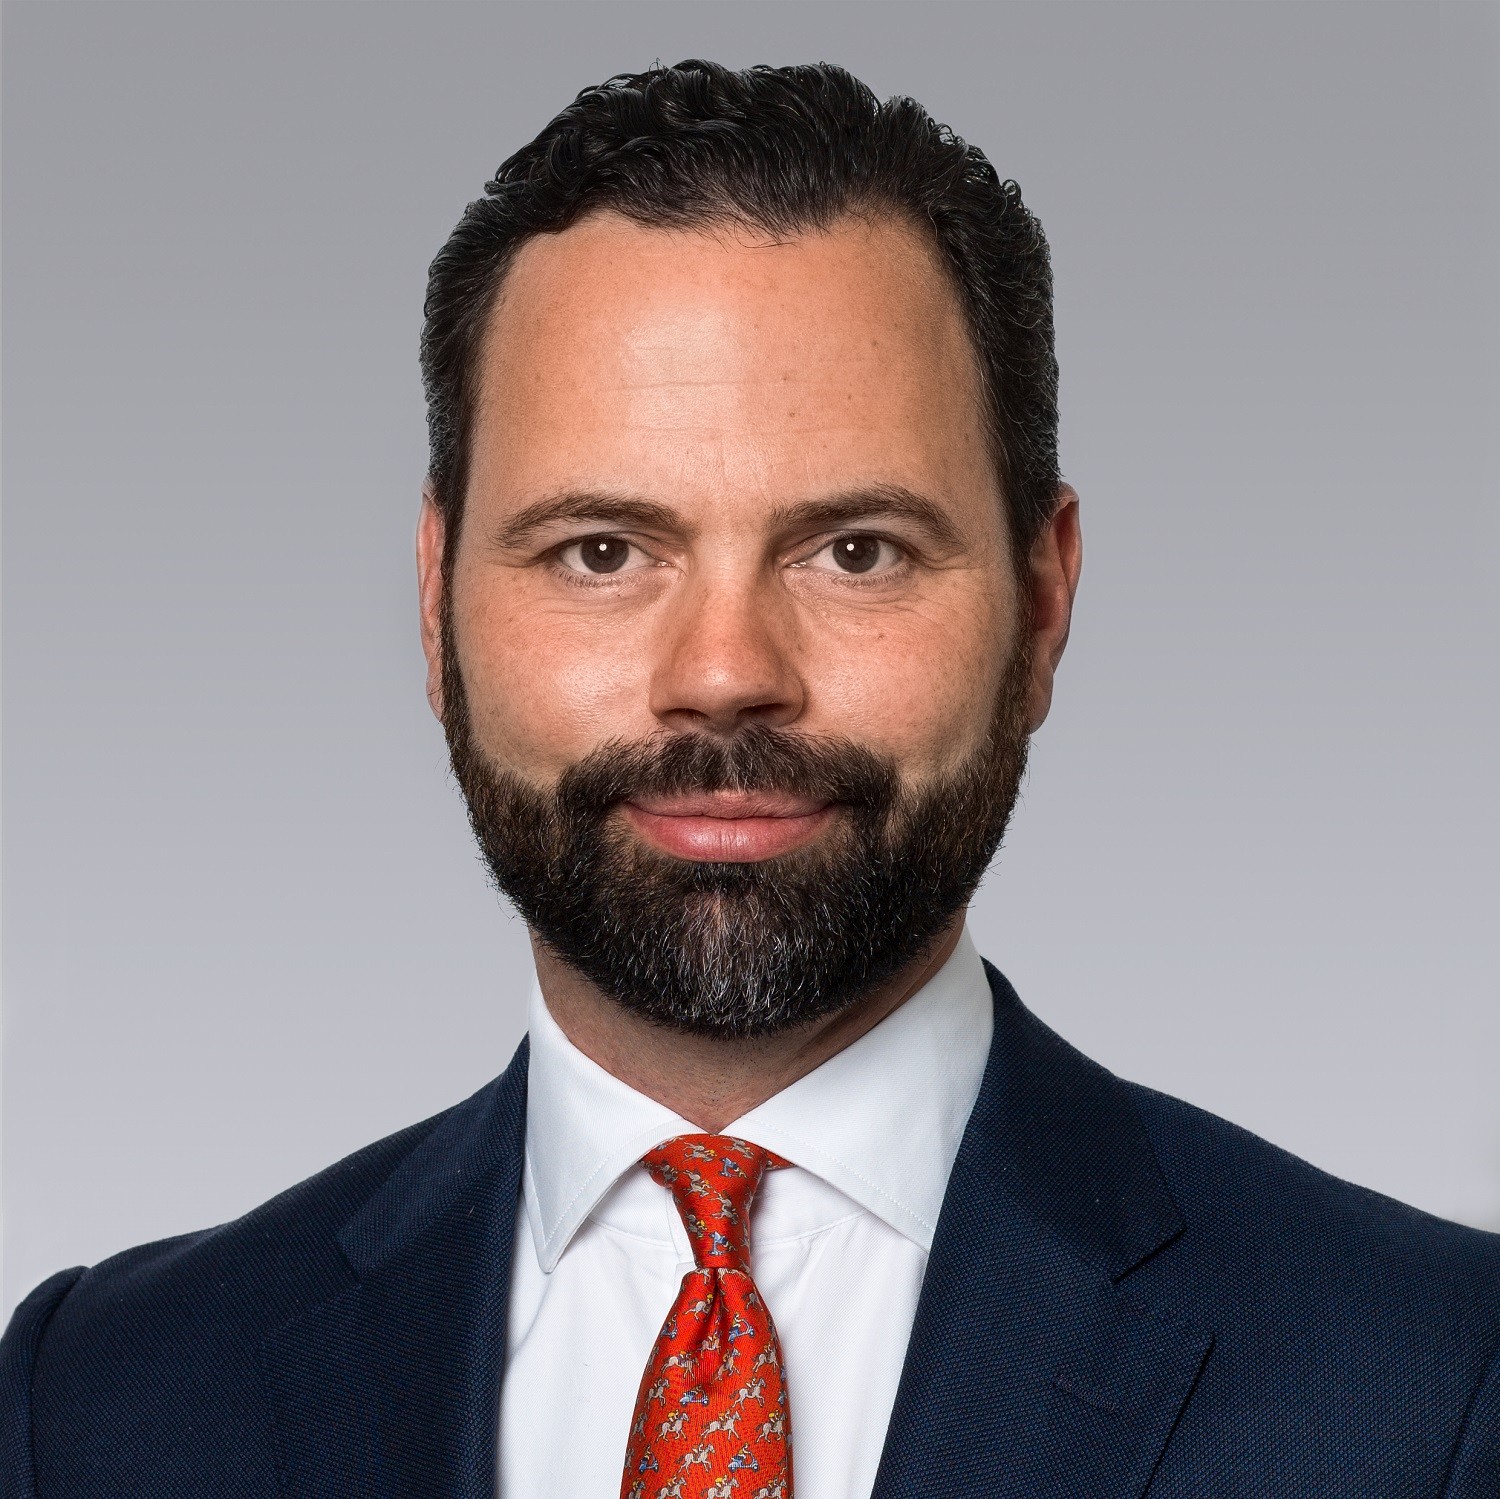
Porträt von Florian Tack, Head of Residential Germany bei Colliers im Anzug
Analysis Quarterly Report

Smaller tickets form the new core foundation in the residential investment market

In the German residential investment market, smaller, more easily financed deals are driving growth. In H1 2026, the volume was EUR 4.2 billion (-3%), individual transactions dominated (64%), top 7 cities 56%. Yields +25-30 bp, financing remains a bottleneck.

#Newsletter: Stay up to date!

Sign up for our newsletter and receive regular updates on the latest topics.

Register now